Insights

How To Communicate and Respond to Government Travel Advice to Customers

How To Communicate and Respond to Government Travel Advice to Customers 800 400 James Hallam

In this post, we will explore your legal and professional duty as a travel agent or tour operator to respond to and communicate this Government travel advice to your customers.

What Travel Advice Does the Government Give?

The UK Government routinely provides travel advice for over 200 overseas countries or territories. This includes updates about the latest entry requirements, safety and security considerations, health risks, and relevant legal differences.

In a tumultuous political climate, this travel advice can differ from one day to the next. A country that was perfectly safe to travel to one week might be completely inaccessible the next.

Why You Need To Communicate Travel Advice to Customers

If the Government suggests that it is unsafe for people to travel to a destination, or if they outline certain precautions that travellers should take, then you may have a duty of care to let your customers know.

You cannot assume that your customers will access this travel advice themselves. If you are selling trips or packages to a certain destination, and the government releases some travel advice about this destination, then you should make every effort to communicate this advice to your customers.

If you do not communicate this travel advice, and something goes wrong during a customer’s trip, then you may be liable for any subsequent loss, damage, or expenses.

Plus, under the Package Travel and Linked Travel Arrangements Regulations 2018, you may have a legal obligation to notify customers of any risks associated with travelling to certain destinations. So, as well as a costly claim from an unhappy customer, and the reputational damages that would follow, you may also face legal action.

How To Stay On Top of Government Travel Advice

You can sign up for email updates featuring the latest travel advice for 226 overseas countries and territories.

Incidents in one country could have repercussions elsewhere. During the recent Middle Eastern conflict, for instance, travellers were advised against journeying to countries that were not directly involved in the fighting.

With this in mind, when registering for updates, it might be best to focus on areas and territories, rather than individual countries.

Sign up for all foreign travel advice updates or you can access each individual country or territory’s page to register for updates relating to that specific location.

How Travel Agents Should Respond to Government Travel Advice

In some cases, a global incident could simply lead to travel delays. But depending on the specific Government travel advice, you may have to:

  • Reroute your customers’ journeys, finding a different way for them to reach the same situation.
  • Cancel their trip entirely. And in the event of a cancellation, you may have to offer your customers’ a full refund, or you could instead offer to make alternative arrangements.

Whichever course of action you decide to take, it is vital that you find a means of effectively communicating both the situation, and what will happen next.

How To Communicate Government Travel Advice to Customers

Verian Group and the Department for Transport drew from behavioural science in an attempt to determine the best way to communicate during travel disruption.

They created a communication toolkit, which offers the following advice to tour operators and travel agents:

Communicate Consistently and Frequently

You should communicate directly with travellers if issues with the Entry/Exit System (EES) and European Travel Information and Authorisation System (ETIAS) will affect a journey they have already booked.

You may have to send multiple updates as the situation develops, and you should ensure your messaging and advice is consistent with the official Government guidance.

The toolkit also advises operators to use trusted sources, and suggests that linking travellers directly to Government information could help them stay informed.

Set Expectations that Information May Change Quickly

Time stamp any information you share, and explicitly state that anything you share may be liable to change. Also make it clear that you will send further updates as the situation develops.

The toolkit suggests that you go for a “factual, professional, and helpful” tone, but that you remain “empathetic and apologetic when [the] impacts are more severe”.

What Should You Communicate?

Above all, it’s important to be specific. If your communications are too generic, travellers may ignore it, or they may be uncertain as to what steps they need to take.

  • “Known” information – Tell them exactly what the Government travel advice is saying, and provide clear explanations for how this might affect their journey. In some cases, they may just have to deal with delays or disruption. But in extreme situations, they may have to cancel their trip outright.
  • “Unknown” information – It is just as important to be clear about any uncertainty. You can emphasise any aspects of the situation that are less clear while remaining as detailed and specific as possible about how the situation might affect your customers. As we mentioned above, you can also promise to provide further updates as the situation develops.
  • Plans and solutions – Tell your customers what actions are being taken, and why. This could include steps you are taking to manage the situation, such as arranging for alternative modes of transport or accommodation. You could also highlight what travellers might expect to happen at transport hubs (longer queues at airports etc.)
  • Steps to take – If the Government travel advice suggests that travellers should take any extra steps when travelling to a location, be sure to advise your customers accordingly. For example, depending on the destination and the situation, they may have to check their documentation, or take out additional travel insurance. 

The Insurance Implications of Government Travel Advice

In extreme situations, the Government advises against all, or “all but essential”, travel to certain locations. If a customer decides to travel to this location despite these warnings, then their travel insurance may no longer cover them for the trip.

You may have to highlight this when communicating with your customers: That if they choose to go ahead with their booking, they do so at their own risk.

Specialist Insurance Services For Travel Agents and Tour Operators

At James Hallam, for over 35 years we have provided dedicated insurance services for travel agents and tour operators. We can advise you on the insurance implications of Government travel advice, and we can also help you get the cover you need at a truly competitive price.

Find out more about our bespoke insurance services for travel agents and tour operators or call us on 0203 967 1923 or email david.mcgregor@jameshallam.co.uk.
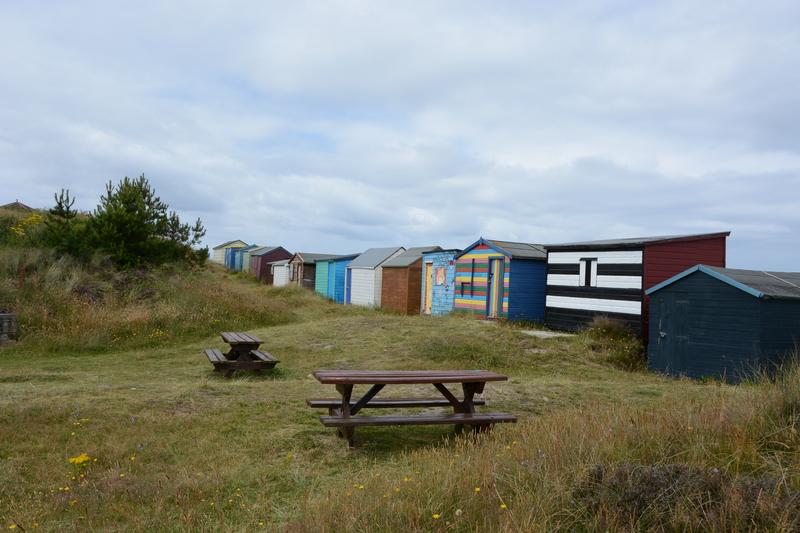
 

First Time Beach Hut Owners: What You Need To Know

First Time Beach Hut Owners: What You Need To Know 800 533 James Hallam

If you are a first time beach hut owner, or you are thinking of buying your first beach hut, this is your essential introduction to the world of beach hut ownership.

We will outline some laws and regulations you need to be aware of, and we will link to some guides and resources that will help you keep your beach hut safe, secure, and in top condition all year round.

Why Are Beach Huts In Such High Demand?

The price of beach huts soared in recent years, rising by over 100% between 2022 and 2023 in popular Dorset hotspots. Though the price of beach huts has fallen across the country since, this does not necessarily mean that there is any less demand.

There are still significant waiting lists across the country. For example, the Bournemouth council waiting list only reopened in 2024, having closed due to excessive demand in 2017.

So, why are beach huts so popular? If you own a beach hut, or you are considering buying one, then you are probably already aware of the appeal: A beach hut is a place to call your own, with fantastic sea views and easy access to the beach and other local amenities.

In the short-term, a beach hut is a peaceful place in which you can spend time with friends and family. And in the long-term, if the prices rise again like they did in recent years, a beach hut may prove to be a good investment.

Leasehold vs Freehole Beach Huts

Whether you have recently bought your first beach hut, or you are looking to purchase a beach hut for the first time, the first question to ask yourself is: Leasehold or freehold?

  • Leasehold – This means you will purchase your hut through the local council, who may set certain restrictions on how you can use the hut.
  • Freehold – This means you will purchase your hut through a private seller. It also means that you will own the land the beach hut is built on, along with the hut itself. This will give you a lot more flexibility in how you use the hut.

Whether your hut is leasehold or freehold will determine the sales process, along with the terms of your ownership. It may also determine how you use your beach hut, depending on the local rules and regulations set out by the council.

You can read our full guide to buying your first beach hut, and the implications of the arrangement, here.

How to Take Care of Your Beach Hut

A beach hut is a significant investment, so you will want to do everything you can to keep it in good condition.

Staying on top of maintenance will help you to ensure your beach hut remains a clean, pleasant, and safe space for years to come. Plus, as we will explain more below, you may be required carry out certain maintenance tasks as a condition of your beach hut insurance.

We have a range of guides that will help you stay on top of your beach hut maintenance throughout the year:

How to Keep Your Beach Hut Safe

As a beach hut owner, you will have to contend with three major threats to your hut:

  • Damage and degradation from extreme weather events
  • Fires, whether as a result of an accident or intentional arson
  • Theft and vandalism

Beach Hut Maintenance: Staying on top of maintenance can help you manage all of these risks. Cleaning and periodically painting your beach hut, for instance, can help protect your beach hut from the elements. Making sure to repair small flaws as soon as you spot them will prevent them from escalating into major structural issues.

Simply keeping your beach hut clean and presentable could also help you to protect it from crime. Thieves, vandals, and even arsonists may be more likely to target beach huts that seem abandoned or unoccupied. They may overlook any beach huts that seem clean and well-maintained.

Beach Hut Insurance: In the event of an incident, whether it is fire, theft, or vandalism, dedicated beach hut insurance can cover you for any damages or other losses. And as we mentioned above, your insurer may outline certain maintenance tasks they expect you to carry out each year, as a condition of cover.

So, get comprehensive cover and keep up with the essential maintenance tasks, and you should protect your beach hut against most, if not all, risks.

Specialist Beach Hut Insurance From James Hallam

James Hallam is an independent Lloyd’s broker with a dedicated team of experienced insurance professionals who are committed to protecting your beach hut.

We provide a specialist beach hut insurance scheme at a competitive price. We are experts in the market, and we can help you get full cover for your hut, no matter its size or location, and no matter how you use it.

Learn more about our specialist beach hut insurance or get a free quote today. For more information, you can call any of the team on 01473 343390 or email huts@jameshallam.co.uk


What is Errors and Omissions (E&O) Insurance & Who Needs It?

What is Errors and Omissions (E&O) Insurance & Who Needs It? 800 534 James Hallam

Errors and Omissions (E&O) insurance is a specific type of professional indemnity insurance that protects you for certain types of liability claims. In this post we will outline what E&O insurance covers and explore which professions could benefit from this type of insurance.

What is Errors and Omissions (E&O) Insurance?

E&O insurance will cover you for claims involving allegations of errors, omissions, or professional negligence. It will also cover you for claims that your services did not meet your client’s expectations, resulting in financial loss.

If a client makes such a claim against you, E&O insurance can cover your legal fees, along with any settlements or compensation payments that may arise.

What is the Difference Between E&O Insurance and Professional Indemnity Insurance?

Professional liability insurance – or professional indemnity insurance as it is known in the UK – is very similar to E&O insurance. In fact, as many professional indemnity insurance policies cover for errors and omissions, some might even use the terms interchangeably.

Both professional indemnity and E&O policies will cover businesses for financial losses arising from errors, or allegations of negligence. E&O insurance policies, though, may be specifically designed to meet the cover requirements of businesses in the technology, finance, and consultancy sectors.

What Does E&O Insurance Cover?

If you provide consultancy services, or if you manage your clients’ finances, then your clients will put a lot of trust into your insights and expertise. If something goes wrong, and your clients make a financial loss, then they might make a claim against you.

This is where your E&O insurance will prove invaluable. If the client’s claim is successful, then your insurance will cover any settlements or compensation they may be due. But crucially, E&O insurance will also cover your legal fees throughout the proceedings.

Even if the client’s claim is unfounded, and even if the court rules in your favour, legal fees can soon ramp up. E&O insurance will give you peace of mind that everything will be covered in the unlikely event of a liability claim from a dissatisfied client.

What Types of Errors and Omissions Are Covered?

An E&O insurance policy might cover claims involving allegations of:

  • Errors or Omissions – As the name suggests, the policy can cover alleged mistakes or oversights that result in financial losses.
  • Negligence – This might include allegations of poor work or misrepresentation, or a failure to meet industry standards. In the creative fields, this could also include cases where you inadvertently breach another business’s intellectual property rights.
  • Defamation – If you make a statement that damages another individual or business’s reputation.
  • Breach of Trust or Contract – If you accidentally break a confidentiality agreement or disclose sensitive information. Or, if you miss deadlines, fail to deliver work, or otherwise breach the terms of your contract.

Who Needs E&O Insurance?

Unlike Professional indemnity insurance, a dedicated E&O insurance policy may be tailored to suit the specific cover and regulatory requirements for businesses in the tech, finance, and consultancy sectors.

This might include any role that involves providing professional services or advice, including:

  • Accountants
  • Financial advisors
  • Software developers
  • Estate agents
  • Law firms
  • Engineers, architects, and surveyors
  • Creative roles, including graphic designers and digital marketers

How To Ensure You Have The Right Level of E&O Insurance Cover

Claims involving allegations of errors and omissions can often prove substantial, especially when you factor in the legal costs.

It is essential to ensure that your E&O insurance policy’s specified limits will cover you for all possible claims. The amount of cover you need will depend on your industry and its regulatory requirements, along with the size of your business, and the types of clients you work with.

James Hallam is an independent Lloyd’s broker with a dedicated team of experienced insurance professionals who care about protecting your business. We can help you get exactly the right level of E&O insurance cover you need at a competitive price.

Learn more about our professional risks services, or for more information call us on 0207 977 7842 or email paul.mcnally@jameshallam.co.uk

Everard Supports All-Women Sea Survival Course

Everard Supports All-Women Sea Survival Course 2048 1536 James Hallam

At Everard, part of James Hallam, we are proud to support initiatives that help strengthen safety, skills and opportunities across the marine industry. As specialist marine insurance brokers with deep roots in the maritime sector, we understand the importance of practical training and ongoing professional development for those working at sea.

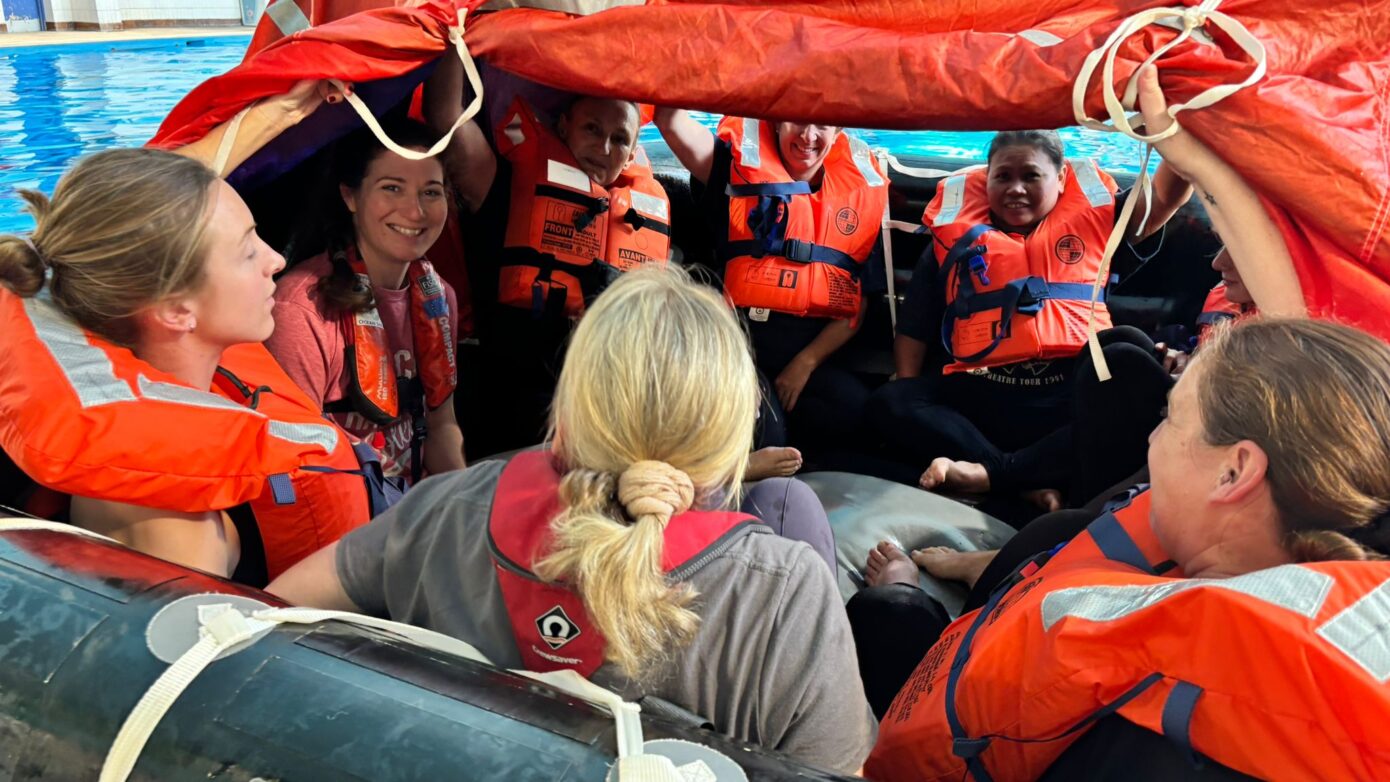
We were delighted to sponsor three spaces on the recent all-women sea survival course organised by Women in Fisheries, helping participants gain vital emergency safety training and confidence at sea.

The course was another successful step forward in supporting and encouraging more women into the fishing and wider maritime industries, while reinforcing the importance of safety awareness and preparedness for everyone working on the water.

Read more about the All-Women Sea Survival course.

As a dedicated marine insurance broker, Everard remains committed to supporting the communities and industries we work alongside every day.

Loss of Hire Insurance: Why It Matters in Commercial Shipping

Loss of Hire Insurance: Why It Matters in Commercial Shipping 1000 667 James Hallam

In commercial shipping, vessel availability is directly tied to revenue generation. When a vessel is unable to trade due to physical damage, the financial consequences can be immediate and significant.

While Hull and Machinery (H&M) insurance covers the cost of repairing physical damage, Loss of Hire insurance protects shipowners against the commercial impact of lost income during periods when a vessel is off-hire.

For owners operating in volatile freight markets, this coverage can play a critical role in protecting cash flow and maintaining operational stability.


What Is Loss of Hire Insurance?

Loss of Hire insurance provides financial protection when a vessel is taken off-hire due to physical damage that is recoverable under an underlying Hull and Machinery policy.

Common triggering events include:

  • Collision
  • Grounding
  • Machinery breakdown
  • Fire
  • Other insured marine casualties

When a valid claim arises, the policy indemnifies the assured for lost daily income during the repair period, subject to agreed policy terms, including deductibles and indemnity limits.


How Does the Loss of Hire Excess Work?

Unlike many insurance policies where deductibles are based on monetary amounts, a Loss of Hire excess is time-based. This means the policy only begins responding after a vessel has been off-hire for a specified number of days.

Key features include:

  • The excess represents the initial off-hire period retained by the assured
  • A common excess period is 14 days, although this varies based on risk profile and underwriting terms
  • The policy responds only once downtime exceeds the agreed excess period
  • Claims are typically paid on a daily indemnity basis
  • Most policies include an annual aggregate limit on claimable days

Example: 14/60/180

A common structure may be written as 14/60/180, which means:

  • 14 days excess – the owner absorbs the first 14 days of downtime
  • 60 days indemnity per claim – maximum payable for any one incident
  • 180 days annual aggregate limit – total maximum claimable days in a policy year

This structure helps shipowners balance premium costs against risk tolerance.


Why Loss of Hire Insurance Is Commercially Important

For many shipowners, lost earnings during downtime can exceed the actual repair costs of a casualty.

Even when a vessel is not trading, fixed costs continue, including:

  • Crew wages
  • Insurance premiums
  • Technical management fees
  • Loan repayments
  • Mortgage servicing costs

Loss of Hire insurance helps businesses:

  • Maintain cash flow stability
  • Reduce earnings volatility
  • Protect profitability during market peaks
  • Improve financial resilience after unexpected incidents

This is particularly important during strong freight markets, where the opportunity cost of downtime can be substantial.


Why Lenders Often Require It

Marine lenders and mortgage providers often require shipowners to maintain Loss of Hire insurance as part of financing agreements.

This helps ensure:

  • Debt repayments continue during downtime
  • Vessel financing risk is reduced
  • Lenders have greater confidence in operational continuity

For highly leveraged fleets, this cover can be an important component of broader risk management.


Why It Matters for Charterers

Loss of Hire insurance can also be relevant for charterers, especially when contractual obligations rely on the continuous availability of a specific vessel.

An insured casualty may result in:

  • Replacement vessel costs
  • Delayed cargo delivery
  • Contractual disruption
  • Increased operational expenses

This makes downtime risk a commercial concern for both owners and charterers.


Key Benefits of Loss of Hire Insurance

  • Protects revenue during insured repair periods
  • Improves cash flow resilience
  • Supports financing and lender requirements
  • Reduces the impact of unexpected downtime
  • Helps stabilise earnings in volatile markets


Specialist Marine Insurance

In commercial shipping, downtime can quickly translate into lost revenue. While Hull and Machinery insurance protects physical assets, Loss of Hire insurance helps protect earnings.

For shipowners, lenders, and charterers alike, it remains an important tool for managing operational and financial risk in an unpredictable maritime environment.

Everard Insurance Brokers are the specialist marine trading division of accredited Lloyd’s brokers James Hallam Limited. We can help you access the specialist cover you need at a competitive price, including Loss of Hire insurance.

Find out more about our dedicated marine insurance services.

Most Common Small Business Insurance Claims Expected in 2026

Most Common Small Business Insurance Claims Expected in 2026 1000 527 James Hallam

Every year, small businesses must contend with a wealth of new and emerging threats, while also safeguarding their operations against the sort of risks that never go away. In this post we will look at some of the most common small business insurance claims that insurers expect to deal with in 2026.

What Claims Are Expected This Year?

In the current climate, insurers are expecting to be dealing with claims relating to:

  • Cyberthreats using AI
  • AI risks relating to data and intellectual property
  • Property damage from extreme weather
  • Property damage and business interruption as a result of deferred maintenance
  • Liability claims

We’ll explore each of these in more detail below, and what you can do to help protect you and your business.

AI Brings Both Internal and External Threats

Cyber threats from AI tools

There is no question that your business needs cyber insurance. One study found that around 96% of all cyberattacks target SMEs. And as artificial intelligence (AI) tools get more powerful and accessible, it has never been easier for cybercriminals to target your business for phishing, ransomware, and other cyberattacks.

Data security, IP and reputational risk from AI use

But AI brings internal threats, too. Many businesses, eager to join the “AI revolution”, have started using off-the-shelf tools to create content, draft proposals, and process their data. This may expose some SMEs to certain unexpected risks.

Without proper governance, through using an AI tool a business may inadvertently:

  • Breach intellectual property laws
  • Leak private or confidential data
  • Provide clients with bad advice or poor services

All of this could lead to costly claims, financial losses, and significant reputational damage.

While AI can help businesses move faster while saving time on admin, you must never take these tools for granted. Never lose sight of the importance of privacy and data confidentiality, and never release or share any AI-created content without first performing a thorough human review process.

And if a client ever makes a claim against you, make sure you have adequate professional liability insurance to cover any legal fees and other expenses that may arise.

Property Damage From Extreme Weather

Extreme weather events, such as storms, high winds, and flash floods, appear to be on the increase. Whether that is the case, the fact remains that property damage from adverse weather is an ongoing risk for any business that operates out of a brick and mortar premises. Regardless of whether that is a retail shop, an office, a bar, a restaurant, or a warehouse.

From backing up your business data to installing flood defences and sprinkler systems, there are many things you can do to help mitigate the damages from any possible incident. Yet it may prove impossible to prevent certain incidents, which is why your small business insurance should give you all the cover you need to make a full recovery.

Business buildings insurance can help you cover the costs of repairs following an incident. But you should also invest in business interruption insurance, which can cover your overheads during an extended period of downtime. And as recovery from an adverse event can take much longer than expected, you should aim to make your business interruption insurance liability period as long as possible.

Read our full guide to how small business insurance can provide vital peace of mind.

Deferred Maintenance: A Disaster Waiting To Happen?

In recent years, high inflation rates and ongoing supply chain issues have resulted in higher labour and material costs, along with longer lead times, for all maintenance, repair, and renovation projects. As a result, many SMEs may have deferred some essential maintenance tasks.

While deferring maintenance can save money in the short-term, in the long-term it could expose your business to a greater risk of fire, flood, subsidence, and downtime as a result of broken or faulty tools or equipment.

In the coming years, insurers may face more claims for repairs or business interruption as all of this deferred maintenance finally catches up with SMEs.

While it is understandable that SMEs will look to save money during uncertain economic periods, it pays to think in the long-term. Switch to a preventative maintenance schedule. The savings you make on deferring maintenance will pale in comparison to the eventual cost of repairs or replacements, or the higher insurance premiums that could follow claims.

Liability Claims – A Perennial Risk For All SMEs

Finally, all SMEs should protect themselves against potential liability claims. This is when an individual or an organisation makes a claim against your business on the grounds of negligence, professional misconduct, or similar.

Here are some situations that could result in a liability claim for your SME:

  • An employee injures themselves on the job, or contracts an illness through their work.
  • A member of the public, such as a customer, a contractor, or a delivery driver, trips or falls while on your premises.
  • A client is dissatisfied with your work, and claims you have breached your contract or acted dishonestly.

In each of these cases, liability insurance can cover any compensation payments that may be due, along with any legal fees that may arise.

Public liability insurance can cover you for any claims arising from incidents involving members of the public, while professional liability insurance can cover you for any claims arising from clients relating to your work or conduct.

You also have a legal requirement to get employer’s liability insurance, which will cover you for any claims arising from your employees.

Talk To James Hallam About Your Small Business Insurance Needs

James Hallam is an independent Lloyd’s broker with a dedicated team of experienced insurance professionals who are committed to getting you the cover you need at a price you can afford, no matter what challenges the next few years may bring.

Get in touch for a free quote today.

What Licences Does a Newsagent Need?

What Licences Does a Newsagent Need? 1000 667 James Hallam

The specific licences you need to run a newsagent will depend on whether or not you choose to sell certain regulated products, such as alcohol and tobacco.

In this post we will list the various licences you may need as a newsagent.

When Does A Newsagent Need a Licence?

Most, if not all, newsagents will need to register for licences to undertake a number of activities and sell different types of products. You will need licences if you wish to:

  • Sell food – registering will give you a licence to store, sell, or prepare food on your premises, as long as you meet all relevant food safety laws.
  • Sell alcohol
  • Sell tobacco products
  • Sell fireworks
  • Sell lottery tickets
  • Play music
  • Employ young people to deliver newspapers

We’ll explore some of these licences in more detail below.

What Licence Does a Newsagent Need to Sell Alcohol?

In the UK, there are two types of alcohol licence: Premises licences, and personal licences. If you want to sell alcohol in your newsagent, you will need both types of licence.

  • A premises licence will give you the legal right to sell alcohol from a specific location – in this case, your newsagent.
  • A personal allowance will give you the legal right to sell alcohol, through acting as your newsagent’s Designated Premises Supervisor (DPS).

If you sell alcohol without the relevant licences, you will face a personal fine of up to £1,000. You may also get a criminal conviction, which could lead to up to six months’ imprisonment.

As part of your licence to sell alcohol, you will be required to implement and enforce age verification policies. Once again, you will face fines and legal sanctions if you fail to do so.

What Licence Does a Newsagent Need to Sell Tobacco?

If you want to sell cigarettes and other tobacco products in your newsagent, you will need an economic operator ID, along with a separate facility ID for your newsagent. If you run more than one newsagent, you will need a separate facility ID for each store.

The Government intends to introduce a new vape licensing scheme by the end of 2026. Under this plan, Trading Standards could issue instant fines of up to £2,500 for any stores caught storing or selling vapes without an appropriate licence.

The vape licensing laws are likely to be similar to the alcohol licensing laws, meaning you will need both a personal and a premises licence if you want to sell vapes at your newsagent.

What Licence Does a Newsagent Need to Sell Fireworks?

You must notify your local fire authority, along with the relevant trading standards departments, if you wish to sell fireworks in your newsagent.

However, you only need a licence if you intend to sell fireworks all year round. You do not need a licence if you are selling fireworks during the Bonfire Night, New Year, Chinese New Year, or Diwali periods – though you will need a licence to store fireworks during these times.

Learn more about the UK’s firework licensing laws.

What Licence Does a Newsagent Need to Sell Lottery Tickets?

If you want to sell lottery tickets in your newsagent, along with other gambling products such as scratchcards, you will need a lottery retail licence from the Gambling Commission.

You can learn more about the current lottery licensing laws.

Specialist Insurance For Newsagents

Selling alcohol, tobacco, vapes, and fireworks from your newsagents may expose your business to additional risks. Thieves may be more likely to target your store for theft, and some products carry a strong fire risk.

You need to make sure your business insurance will cover you for the risks associated with storing and selling these regulated items.

James Hallam is an independent Lloyd’s broker with a dedicated team of experienced insurance professionals who care about protecting your business. We can help you ensure that your specialist newsagent insurance meets all of your cover needs at the right price.

Find out how we can help you today.

Tool Insurance: How Much Is It, and Is It Worth It?

Tool Insurance: How Much Is It, and Is It Worth It? 1000 667 James Hallam

Tool insurance is essential cover for anyone who works in construction, or any related trades. Or indeed anyone who owns and uses tools as part of their work.

In this post we will outline what tool insurance is, and what it covers. We will also give a ballpark figure for the amount you might expect to pay for this cover.

What is Tool Insurance?

Tool insurance is cover for your tools and equipment. This can include handheld tools, including hammers, screwdrivers, and saws; and power tools, including drills, angle grinders, and nail guns. A tool insurance policy can cover your equipment whether you own it, lease it, or use a hire-purchase arrangement.

A policy may be extended to cover any plant machinery you might use as part of your work, such as excavators and bulldozers. Though some insurers may offer dedicated plant and machinery insurance instead.

It’s also possible to include cover for tools as part of a Contractor’s Policy or a Trades & Professions Policy, both of which provide broader cover for the business as a whole.

What Does Tool Insurance Cover?

Most tool insurance policies will provide cover for:

  • Damage, theft, or loss (whether this is accidental damage or intentional vandalism or theft)
  • Tools in transit
  • Toolbox cover (i.e. cover for the equipment you use to store your tools)
  • EU cover (for overseas jobs)
  • Hired-in plant cover, for any equipment you hire, or buy on hire purchase

In addition, your tools insurance may extend to cover any other equipment you use as part of your job, such as ladders, your smartphone, your laptop, and so on.

What Does Tool Insurance Not Cover?

Usually, tool insurance will not cover ordinary wear and tear, or any deliberate damage caused by employees. Plus, if you need to replace a tool because it becomes faulty, this should be covered by your warranty, as opposed to your tool insurance.

Finally, while your tool insurance may cover tools you occasionally leave out of sight in a van overnight, it may not cover tools you keep in a van indefinitely. The policy may specify that the cover will not extend to any tools you keep in a van for 48 hours or longer.

How Much Is Tool Insurance?

The amount you pay for your insurance will vary from insurer to insurer. Some insurers may charge as little as less than £10 a month for tools insurance. But your premiums may be much higher, depending on your personal circumstances.

The more tools you need to cover, and the more expensive these tools are to begin with, then the more you will have to pay. You may also have to pay a higher premium if you routinely work in urban areas, or other locations with comparatively high crime rates.

How to Keep Your Tools Safe

If you take steps to keep your tools safe, it can help to bring down the cost of your tool insurance:

  • Never store tools in a van for any longer than you have to. Try to keep them somewhere extra secure overnight and over weekends.
  • Get extra security features for your vans and other vehicles, including alarms, locks, and immobilisers, to keep your tools safer both in transit and in storage.
  • Register your tools’ serial numbers online, so that police can attempt to track them, and potentially recover them, following a theft.
  • Try not to keep your tools unattended. Someone may steal them when you are not looking, or they may get exposed to hazardous conditions that could lead to damage or loss.

Is Tool Insurance Worth It?

If you work in construction or own high-value tools in your business, then tool insurance is a business necessity.

According to figures from Met Police, nearly 45,000 tools are stolen every year in the UK. Typically, each individual instance of tool theft costs construction businesses between £1,000 and £3,000, which does not include the costs associated with the disruption and delays that could arise from tool theft.

Plus, beyond theft, there is also the chance you could lose or accidentally damage your tools. It is no exaggeration to say that your construction projects simply will not be able to continue without the necessary tools of the trade. Repairs and replacements can be expensive, which is why tools insurance can provide vital financial support for construction businesses of all sizes.

Get The Specialist Construction Cover You Need From James Hallam

At James Hallam, we can help you protect your construction business with specialist risk management and insurance support.

We are an independent Lloyd’s broker with a dedicated team of experienced insurance professionals who are committed to getting you the specialist construction insurance you need at a competitive price, which can include comprehensive tools insurance.

Find out how we can help you today.

Charity Trustee Responsibilities and Duties

Charity Trustee Responsibilities and Duties 1000 666 James Hallam

UK law outlines a number of legal responsibilities and duties for charity trustees. In this post we will take a closer look at what these duties entail, and explore how specialist trustee insurance can help you stay safe and compliant in your role as a trustee.

What is a Charity Trustee?

A charity trustee is anyone who has overall control of a charity and its operations. Trustees are chiefly responsible for ensuring that the charity is run effectively, and that it stays true to its mission and goals.

As well as dedicated trustees, a charity’s directors, board members, governors, and committee members may also take on trustee roles and responsibilities.

Charity Trustee Eligibility Laws

The UK Government sets the following eligibility criteria for charity trustees:

  • You must be at least 16 years old to be a trustee at a charity that is a company, or a charitable incorporated organisation (CIO). To be a trustee at any other kind of charity, you must be at least 18 years old.
  • The charity must appoint you following the procedures and restrictions in their governance documents.

What Can Disqualify You From Being a Charity Trustee?

The UK Government also lists some criteria that will disqualify you from acting as a trustee:

  • Bankruptcy, or an individual voluntary arrangement (IVA)
  • Unspent conviction for certain criminal offences, such as those involving dishonesty or deception.
  • Being on the sex offender’s register.

There are additional restrictions concerning any charities that work with children or adults at risk. You can read a full guide to the trustee eligibility laws.

You can apply for a waiver from the Charity Commission if any of these disqualifying criteria apply to you.

Main Duties of Charity Trustees

There are six main duties that charity trustees are expected to carry out:

  1. Ensure that the charity is carrying out its purposes, and no other purposes, for the public benefit.
  2. Comply with the charity’s governance documents, along with all applicable laws, including preparing and submitting annual returns.
  3. Act in the charity’s best interests. This means making adequately informed decisions, avoiding conflicts of interest, and refusing all benefits from the charity unless they are properly authorised, and clearly in the charity’s interests.
  4. Manage the charity’s resources responsibly. Among other things, this means ensuring that the charity’s assets are only used to support or carry out its purposes.
  5. Act with reasonable care and skill.
  6. Ensure the charity is accountable. As well as meeting all statutory accounting and reporting requirements, you should be able to evidence how your charity is run, and how it complies with all relevant legislation.

Specialist Trustee Roles: Chair and Treasurer

Some trustees, such as the chair and the treasurer, take on specialist roles. They are known as officers, and though they do not automatically have any additional legal duties, there should be specific provisions in the charity’s governance documents concerning their responsibilities.

But even if one trustee works as a treasurer, it does not mean that this trustee takes sole responsibility for the charity’s finances. Plus, while a chair of trustees might coordinate meetings, they will not take sole responsibility for anything that happens to the charity.

In short, regardless of whether or not the charity appoints officers, all trustees will always remain jointly responsible for the charity.

Can Charity Trustees Be Personally Liable for Issues?

If a charity trustee fails to comply with these duties and responsibilities, then they may be held personally liable for any financial losses the charity suffers. They may also be held personally liable for any claims made by a third party against the charity.

For example, if a trustee spends a charity’s funds on the wrong purposes, then they may ultimately be required to reimburse the charity personally. Plus, if the charity faces any fines or other penalties as a result of not meeting certain accounting or reporting requirements, then once again, the trustees may be held responsible for these expenses.

Make Sure You Are Covered For All The Risks You Face as a Trustee

Bespoke charity insurance can include cover for trustees who may be held personally liable for claims involving dishonesty or mismanagement.

At James Hallam, we have supplied dedicated insurance and risk management solutions to charities and other third sector organisations since 1982. We are an independent Lloyd’s broker, and charity trustees across the UK rely on us for expert advice and market-leading solutions at a competitive price.

Find out how we can help you manage all of the risks you face as a charity trustee.

What Boat Safety Equipment and Requirements Do I Need?

What Boat Safety Equipment and Requirements Do I Need? 1000 667 James Hallam

Whether you own and operate a boat, or you run a marina, the right safety equipment and procedures are vital for preventing and effectively responding to incidents on the water.

In this post we will list all of the essential safety equipment that every UK boater should have onboard.

For further information about keeping yourself, your passengers, and your vessel safe on the water, take a look at our guide to boat safety certificates.

What are the Most Common Boating Safety Risks?

There are a number of common risks to be aware of in and around boats, in particular:

  • You, a crew member, or a passenger falls overboard
  • Someone sustains an injury while onboard your vessel
  • A fire breaks out
  • Collisions with other vessels
  • Your engine breaks down, leaving you stranded

Essential Safety Equipment For All UK Boaters and Marinas

In the UK, the specific safety regulations that apply will depend on the size of the vessel, and its crew. In short, the bigger your boat, the more safety regulations you will have to meet.

Below we will list the essential safety equipment that all vessels of all sizes should consider having onboard, including:

  • Lifejackets
  • First aid kit
  • Navigational tools
  • Communication tools
  • Maintenance equipment

We’ll explore each of these in more detail below.

Lifejackets

Everyone onboard should have a properly fitting lifejacket, which should meet ISO 12402 safety standards. A good lifejacket will have additional safety features including lights and whistles for attracting attention.

You should also ensure your vessel has a lifebuoy or throwing line, in case someone falls overboard.

First Aid Kit

You should also routinely check your first aid kit to ensure that all materials are still in date, and you should replace or replenish items whenever necessary.

Navigational Tools

You will need charts, navigation books, a compass, binoculars, and a GPS device for navigating unfamiliar waters.

All vessels should be equipped with navigation lights too, even if you do not intend to sail after dark. At the very least, you will need a green starboard light, a red port light, and a white centre light, all of which should be visible from at least a mile away.

Communication Tools

A VHF radio is necessary for staying in touch with the shore, and with other vessels. For this, you will also need an MMSI number and an Ofcom licence.

If you do not have the means for a radio, you should still stock flares and other distress signals, so you can attract attention in the event of an emergency.

Maintenance Equipment

Depending on the type of boat you operate, you may need a toolkit for basic repairs, cleaning supplies, spare engine parts, and a bilge pump for removing excess water.

Ongoing maintenance can help you recover from engine failure and other incidents, while keeping everything clean can help prevent faults and fires.

How to Check Your Boat is Compliant With Safety Regulations

The specific safety regulations will also depend on the type of waterway in which you will be operating. Different organisations govern different waterways, and local regulations and restrictions also apply to some areas.

The following organisations govern UK boat safety equipment regulations:

When planning an excursion, check first what regulations apply to the waters you will be navigating. And remember that regulations will only list the minimum safety standards. For total peace of mind, and to prepare you for any situation, it pays to go beyond the minimum safety standards.

Boat Safety Equipment and Insurance

Finally, your insurer may also specify some essential safety equipment you need to keep onboard as a condition of your cover. If you are involved in an incident, they may reject your claim if they find you did not have certain items onboard, or if it transpires that you did not keep on top of essential cleaning or maintenance tasks.

Everard Insurance Brokers are the specialist marine trading division of accredited Lloyd’s brokers James Hallam Limited. We can help you ensure your boat meets all relevant safety standards, and we can help you access the specialist cover you need at a competitive price.

Find out more about our dedicated marine insurance services.