Insights

Cruise Ship Piracy: How to Prevent and Protect Vessels and Passengers

Cruise Ship Piracy: How to Prevent and Protect Vessels and Passengers 1000 660 James Hallam


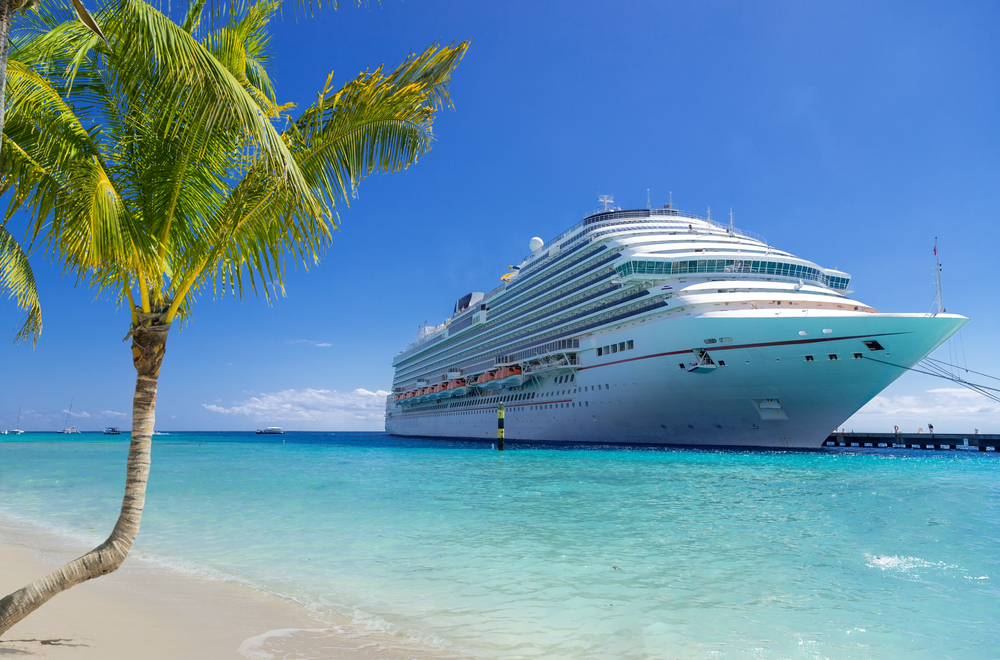
Pirate attacks on cruise ships are relatively rare, but they remain a threat no cruise ship operator should ignore.

In this post we will list some examples of cruise ship piracy, before exploring how you can prevent pirate attacks and keep your vessel and your passengers safe.

How Common Are Pirate Attacks Against Cruise Ships?

Though pirate attacks against cruise ships do happen, they are relatively rare. Pirates are unlikely to target cruise ships for a number of reasons. They are large, they travel at high speeds, and they tend to travel through waters that are patrolled by naval forces. Plus, cruise ships tend to have advanced radar systems, meaning they would be able to detect any approaching pirates with ease.

In addition, pirates know that cruise ships tend to have multiple anti-piracy systems onboard, which would make an attack too risky. In 2011, the Spirit of Adventure was approached by pirates off the coast of Tanzania. The pirates seemed to observe the ship, but they left before taking any action. A spokesperson later said that, most likely, the pirates thought better of attacking once they got a good look at the ship’s security systems.

But pirates can be opportunistic. And if they suspect that a cruise ship will be unable to defend itself, they may attempt an attack. This is why all cruise ship operators should put measures in place to prevent and respond to pirate attacks, no matter how low the risk may be.

Examples of Cruise Ship Pirate Attacks

  • The hijack of an Italian cruise ship, the MS Achille Lauro, with with 97 passengers and hundreds of crew on board.
    Find out more about the Achille Lauro hijacking, Mediterranean Sea, 1985
  • The pirate attack of the Seaborn Spirit cruise liner, with 300 crew and passengers targeted off the Somali coast.
    Find out more about the Seabourn Spirit, Somalia, 2005
  • The attack on a German cruise ship sailing from Eygpt to Dubai with 492 passengers and a number of crew.
    Find out more about the MS Astor, Gulf of Oman, 2008
  • The pirate attack of an Italian cruise ship with almost 1,000 passengers on board, resulting in gunfire.
    Find oure more about the MSC Melody, Somalia, 2009

The pirates’ motives and methods varied in each of these cases. But usually when it comes to cruise ships, pirates will attempt to hijack the ship, using the passengers and crew as hostages.

However, most pirate attacks against cruise ships tend to be thwarted before the pirates can even get onboard. This means it is hard to gauge the pirates’ motivations: Whether they wanted to take control of the ship, or simply to steal valuables from guests.

How Do Cruise Ships Protect Themselves and Passengers Against Pirates?

Crew and Passenger Drills

Everyone onboard should know exactly what steps to take in the event of piracy. You can arrange for specialist training for your crew, and you can outline your piracy response procedures as part of your mandatory passenger safety drills.

Safety Procedures

When sailing through waters where there is a risk of a pirate attack, cruise ships should temporarily move all outdoor activities indoors. They should also aim to darken the ship’s lights at night, to make them less of a visible target for pirates.

In the event of an attack, all passengers should stay below decks, ideally in their cabins with their doors locked, until further notice.

Detection and Communication

Cruise ships should make use of their advance radar systems to detect potential piracy attacks as early as possible. You should also stay in constant communication with all other ships in the area, including the naval forces, and notify them of any emerging risks.

If all the ships in a body of water coordinate in this way, pirates will find it harder to approach vessels without warning, and to isolate vulnerable vessels for attack.

Onboard Deterrents

Cruise ships often make use of water cannons and acoustic weaponry to ward off attacks. During the attack on the MSC Melody in 2009, crew members also used pistols that were stored onboard to deter a pirate attack.

Certain maritime officials criticised this approach, saying that non-lethal weaponry would have been just as effective. Any cruise ship using live ammunition will need to ensure that all onboard firearms are registered, and that only trained and authorised crew members have access to them.

Is Your Cruise Ship Covered For The Risks of Piracy?

If your cruise ship will be travelling through a location with a risk of piracy, then you must ensure that your maritime insurance covers you for the increased risk. Your policy should include war risk insurance, which can protect against losses from acts of piracy, along with kidnap and ransom insurance (K&R) for you, your crew, and your passengers.

Everard Insurance Brokers is the specialist marine division of accredited Lloyd’s broker James Hallam Limited. We can help you secure comprehensive protection against piracy and related risks, to help you respond effectively to any incident at sea.
Learn more about our dedicated marine insurance services.

Beach Hut Spring Clean Checklist

Beach Hut Spring Clean Checklist 1000 666 James Hallam

A good spring clean will help you get your beach hut ready for the season. It will also help you stay on top of any maintenance or repairs that might be necessary following the winter.

In this post we will list the beach hut spring clean essentials. Be sure to check out our guides to keeping your beach hut safe and clean throughout the rest of the year too:

Why Regular Beach Hut Cleaning and Maintenance Matters

With the high winds, heavy rains, and low temperatures, winter can be a punishing time for beach huts. The sooner you take care of any repairs or renovation jobs, the less likely it is that you will have to face more serious repairs in the future.

Keeping your beach hut in good shape may also be a condition of your beach hut insurance. Your insurer may specify that you need to keep your hut in good condition. Failure to do so could ultimately invalidate your cover.

But above all, ongoing maintenance will help you ensure that your beach hut remains a clean and pleasant place to be all year round.

Beach Hut Spring Clean Checklist

Step 1: Look For Signs of Damage

First, you should thoroughly inspect your beach hut, inside and out, for any signs of damage from the winter.

Check the roof, doors, joints, hinges, and windows. Look for any signs of leaks, pests, or structural damage, and address all repairs, no matter how minor, as soon as possible.

Step 2: A Deep Clean Checklist

Now it is time to get your beach hut ready for the season:

  • Open all windows and doors to let the air in.
  • Sweep out any sand that may have found its way in, and dust all surfaces.
  • Wash all the walls, along with any fixtures or fittings.
  • Consider a fresh coat of paint, if it has been a while.
  • Add fresh coats of wood stain or sealer to any outdoor decking, if necessary.

Spring is also a good time to declutter. Look through all the furniture, fixtures, and other equipment you keep in your beach hut. Recycle or donate anything you no longer want or need, and consider getting some fresh items for the new year.

Step 3: Beach Hut Safety Checks For Spring

Finally, you could take the time to perform some essential beach hut safety checks:

  • Make sure all of the hut’s locks work, and replace or repair any components if you need to.
  • If your hut has any heating or electrical equipment, consider getting an official safety check to ensure that you will be able to rely on everything over the coming season.
  • Restock your hut with all the essential safety equipment, including a first-aid kit, a fire extinguisher, and sunscreen.
  • Add a smoke alarm or a burglar alarm, to help prevent losses from fires or break-ins.

Specialist Beach Hut Insurance From James Hallam

Finally, the start of the new year could be a good opportunity to review your beach hut insurance, to ensure you are still getting all the cover you need at a competitive price.

James Hallam is an independent Lloyd’s broker with a dedicated team of experienced insurance professionals who are committed to protecting your beach hut.

We provide a specialist beach hut insurance scheme at a competitive price. We are experts in the market, and we can help you get full cover for your hut, no matter its size or location, and no matter how you use it.

Learn more about our specialist beach hut insurance and get a free quote today.

How Travel Destinations are Changing Amid the Middle Eastern Conflict

How Travel Destinations are Changing Amid the Middle Eastern Conflict 1000 646 James Hallam

There has been ongoing conflict in the Middle East for some years now, but things escalated significantly in the first quarter of 2026. The entire region faces considerable unrest for the foreseeable future, which will obviously have an impact on the global travel industry.

However, rather than cancelling their travel plans outright, the majority of travellers instead seem to be switching their destinations.

In this post we will examine how travel destinations are changing amid the Middle Eastern conflict.

Behavioural Shifts Among Travellers Following the Middle East Conflict Escalation

The latest Globetrender Executive Travel Pulse survey provided some insights into how the Middle Eastern Conflict is changing travel preferences.

Among the travel industry executives they surveyed:

  • 34% reported cancellations
  • 12% reported shorter booking windows
  • 44% reported destination switching as the most pronounced behavioural shift among their customers

Please note that Globetrender surveyed North American travel executives. The most recent figures we could find referring to UK and EU travellers predated the latest Middle Eastern conflict. However, the trends among travellers across the world will likely tell a similar story, with travellers choosing new destinations rather than cancelling their trips outright.

How Are Travel Destinations Changing Amid the Middle Eastern Conflict?

What Qualities are People Looking for in Travel Destinations?

With the uncertainty of the conflict, travellers are looking at destinations that are:

  • Safer
  • Accessible
  • Reliable

In particular, they’re looking for destinations where there is less risk that a trip will be cancelled or delayed due to flight routing.

Which Destinations are Becoming More Popular?

The same survey also revealed the sort of destinations travellers are choosing over previously popular destinations:

  • 59% of travel executives have seen an increased demand for European destinations, particularly in Southern Europe.
  • 32% have seen increased demand for Latin American and Caribbean destinations.
  • 27% have seen an increased demand for UK and Ireland destinations.
  • 24% have seen an increased demand for North American destinations.

What Types of Travel Will be Most Affected?

Travel executives also believe that some segments will prove more resilient than others. The majority (76%) believe that luxury travel will prove largely unaffected by the conflict, followed by domestic travel (51%) and cruises (22%).

Budget travel, however, may take a hit. Only 2% of executives believe that the budget sector will be resilient, perhaps worrying for the future of all-inclusive resorts in Egypt, Turkey, and other countries.

How Travel Agents and Tour Operators Should Respond to Conflict in the Middle East

Travellers are not frantically cancelling or curtailing their trips in the face of conflict. However, they are looking for safer and more reliable destinations. As a travel agent or tour operator, you should simply continue to do what you always do: Give customers the trips and the experiences they are looking for.

  • Rethink Your Destinations – Southern Europe. Latin America. The Caribbean. Prioritise areas where your customers will feel safe, and where they can rely on as little disruption as possible.
  • Go Local – It is likely that some travellers will choose to avoid flying outright. 27% of travel executives reported an increased demand for UK and Irish destinations. Could you cater for this demand?
  • Be Aware of Wider Trends – The Middle Eastern conflict is not occurring in a vacuum. It is just one of many trends currently shaping the global travel industry. For example, another recent survey revealed that around 75% of travellers are looking for more sustainable travel experiences.

Specialist Insurance Services For Travel Agents and Tour Operators

At James Hallam, for over 35 years we have provided dedicated insurance services for travel agents and tour operators. Our tailored services can help you get the cover you need at a truly competitive price.

Find out more about our bespoke insurance services for travel agents and tour operators.

What is a Retroactive Date on Professional Indemnity Insurance?

What is a Retroactive Date on Professional Indemnity Insurance? 1000 664 James Hallam

If you are looking for a professional indemnity insurance policy, then it is vital to ensure that your insurance will cover you for any claims that may be brought against you. The policy’s retroactive date can determine whether or not you are covered for certain claims.

In this post we will explain what a retroactive date is on a professional indemnity insurance policy, and why it matters.

What is a Professional Indemnity Insurance Retroactive Date?

This is the date from which your insurer has agreed to cover you. A professional indemnity insurance policy should specify a retroactive date. Usually, the policy will cover you from the date you took out the insurance. However, some policies may specify an earlier retroactive date, or a later one.

How Does Your Retroactive Date Affect Claims?

Your policy will only cover you for claims arising from work you have undertaken, or advice you have given, after this specified retroactive date. So, when you are taking out a professional indemnity policy, it is crucial to ensure the retroactive date either includes the date you started your business, or the date on which you started a project or contract which may arise in a claim.

Different Types of Retroactive Dates on Professional Indemnity Insurance Policies

Your insurer may refer to your retroactive date in a number of ways:

  • Unlimited Retroactivity – This means that your policy will give you full retroactive cover. You will have cover for any claim you report during your policy period, even if the claim relates to work you carried out, or advice you gave, before you took out the policy. Unlimited retroactivity cover may also be referred to on your policy as “retroactive date: none”.
  • Specified Retroactive Date – Alternatively, your policy may include a specific retroactive date. As we mentioned above, this means you will only have cover for claims arising from work you have undertaken, or advice you have given, after this specified date. You will not be covered for any work you undertook before this date.
  • Retroactive Date Inception (RDI) – This simply means that your cover will commence from the date you took out the policy. You will not be covered for any work you began before you took out the policy.

Why Retroactive Dates Matter For New or When Switching Policies

You should be able to rely on your professional indemnity insurance policy to cover you for any claim your clients may make against you. A specified retroactive date, or an RDI policy, will be fine if your business is just starting out, or if you are getting cover for a specific contract or project.

However, if you are switching policies, or if you are purchasing PI insurance for the first time, then it is important to ensure that there are no gaps in your cover.

Alternative Retroactive Clause, and Avoiding Gaps in PI Cover

Some insurers are a bit more specific with their retroactive date clauses. They may specify that the retroactive date is the earlier date of:

  1. The date you first purchased this specific policy.
  2. The retroactive date specified on the PI insurance policy you had previous to taking out this specific policy.

In short, this means that the insurer expects you to provide evidence that you had professional indemnity insurance in place since you started trading. If you cannot provide this evidence, then your retroactive date will simply be the date you took out insurance from your current provider. This means they will not cover you for any claims arising from before this policy period.

You can contact your previous providers for evidence of your previous policies. But if this is your first PI policy, or if there are gaps in your cover, you can ask your current provider for an earlier retroactive date, or for unlimited retroactivity. Just bear in mind that this may result in higher premiums, and there may also be a one-off premium payment for this policy adjustment.

We Can Help You Ensure Your PI Insurance Covers You For All Claims

James Hallam is an independent Lloyd’s broker with a dedicated team of experienced insurance professionals who care about protecting your business.

Whether you are just starting out, or you are looking to switch providers, we can help you ensure that your PI insurance covers you for any claim that may be made against you, even if the claim is relating to work you commenced before you took out the insurance.

Learn more about our professional risks insurance services.

silver jewellery

Plated, Polished and Potentially Underinsured: What Jewellery Market Changes Mean for High-Net-Worth Individuals

Plated, Polished and Potentially Underinsured: What Jewellery Market Changes Mean for High-Net-Worth Individuals 1000 667 James Hallam

When Pandora announced its shift away from sterling silver towards platinum-plated collections, the story made retail headlines. For high-net-worth individuals, the more pressing question is what that signals about the insurance value of what’s already in your jewellery box.

As materials change, prices shift and collections evolve, insurance arrangements that once provided adequate cover can quietly fall short, often without the policyholder realising it.

Replacement Value – Not Sentiment or Resale

For many clients, jewellery carries both financial and sentimental value. From an insurance perspective, however, the focus is on the cost of replacing an item like-for-like at today’s market rates.

The distinction between market value and replacement value is widely misunderstood.

Secondary market or auction values rarely align with current retail pricing. A piece that may have modest resale value can carry a significantly higher replacement cost – particularly when brand, craftsmanship or material changes are factored in.

Where manufacturers alter materials, as we are now seeing, the position becomes more nuanced. A piece originally specified in sterling silver may no longer exist in that form. Its modern equivalent, may be platinum-plated and may differ in both cost and availability. If schedules are not updated accordingly, this can create challenges at the point of claim.

Market Volatility and Its Impact on Jewellery Valuations

Precious metal markets have seen sustained volatility in recent years. Silver has been particularly affected, but movements in gold, platinum and palladium have also materially influenced jewellery valuations and replacement costs.

Valuations carried out even two or three years ago may materially understate current replacement costs. The conventional guidance of reviewing every three to five years remains a useful benchmark, but in periods of significant market movement – such as the gold and silver price surges of recent years – earlier reassessment is warranted and often on annually.

Accumulation Risk Within Jewellery Collections

One of the more understated risks we encounter is the gradual accumulation of jewellery. Individually, pieces may appear modest in value, however collectively they can represent a significant exposure.

Standard household policies typically impose low single article limits, requiring individual items above a certain value, for example £2,500, to be separately specified. Equally important, and often overlooked, is the overall position: the total value of a collection can quietly exceed policy assumptions without ever being formally declared.

For high-net-worth clients, specialist policies typically provide broader cover and greater flexibility. However, even within these arrangements, accurate overall valuations remain essential to ensure the integrity of cover.

Branded Jewellery and the Importance of Currency

Established brands such as Tiffany & Co., Cartier or Georg Jensen offer a clearer framework for valuation and replacement. Their documented designs and pricing structures provide insurers with a reliable reference point but this consistency can also create a false sense of security.

Collections evolve, pieces are discontinued, and pricing adjusts, often significantly over relatively short periods. A valuation that was entirely appropriate several years ago may now understate the true replacement cost. For bespoke items, the position is more complex still, particularly where gemstones or unique design elements are involved. In these cases, specialist valuation is critical.

When to Revisit Jewellery Valuations

No single trigger should prompt a valuation review but several circumstances make it particularly timely.

This is particularly relevant where:

  • Items have been acquired or gifted in recent years
  • Existing valuations are more than a few years old
  • Collections have grown gradually over time
  • Or where pieces are materially influenced by precious metal or gemstone pricing

Where any of these apply, the gap between recorded and actual replacement value is likely to be widest. Speaking to your adviser about commissioning an up-to-date valuation is a straightforward step that can prevent significant complications at the point of claim.

The Role of Specialist Valuation

Accurate jewellery insurance relies on more than a broad estimate of worth.

Professional valuations provide a detailed assessment of materials, craftsmanship, provenance and current market conditions. This is particularly important for:

  • High-value individual pieces
  • Branded collections subject to price changes or discontinuation
  • Bespoke or unique items
  • Jewellery incorporating coloured gemstones, where pricing can be especially variable

Without this level of detail, establishing an appropriate replacement value can be challenging — particularly at the point of claim.

Understanding Jewellery as a Dynamic Asset

Jewellery is often viewed primarily through a personal or sentimental lens. From a risk perspective, however, it is better understood as a dynamic asset class.

Values are influenced not only by ownership and acquisition, but by:

  • Commodity price movements
  • Brand positioning and retail strategy
  • Design changes and product availability
  • Broader market demand

Each of these factors can move independently, and their combined effect on replacement cost is not always immediately visible.

Final Thought

The changes underway in the jewellery market – shifting materials, evolving brand strategies and volatile precious metal prices – are a useful prompt to revisit cover, but they are not the whole story. Even without dramatic market events, well-documented collections gradually diverge from their recorded figures.

Maintaining accurate cover is less about reacting to headlines and more about recognising that jewellery, like any high-value asset, is a dynamic holding that requires the same periodic attention you would give to any other significant part of your financial affairs.

escape of water

Escape of Water Insurance: The Most Overlooked Risk in High-Value Homes

Escape of Water Insurance: The Most Overlooked Risk in High-Value Homes 800 533 James Hallam

Escape of water – leaks from internal plumbing, fittings, or heating systems – is the most common cause of insurance claims in the high‑net‑worth (HNW) property market. UK insurers pay out around £1.8 million every day for water damage, yet it remains one of the least appreciated risks.

This guide explains why high‑value homes face a heightened exposure to water damage and highlights the vulnerabilities that matter most, from underfloor heating and basements to swimming pools and smart home systems. It also outlines practical steps owners can take to reduce the likelihood and impact of a claim.

Why High-Value Homes Face a Greater Escape of Water Risk

A standard home with simple plumbing presents a contained risk. Large country houses, London townhouses with basements, and properties with pools or integrated technology have far more complex systems and far more potential failure points.

Multiple bathrooms, hydronic underfloor heating, leisure spaces, and sophisticated building management systems all increase the chance of a leak. In HNW homes, the cost of reinstatement is also higher due to specialist materials, bespoke finishes, and valuable contents.

Escape of water accounts for roughly 30% of UK home insurance claim costs. While the average claim is £5,000–£10,000, losses in high‑value homes can be significantly greater.

Key Vulnerabilities in High-Value Properties

Multiple Bathrooms, En Suites, and Wet Rooms

More bathrooms mean more pipework, seals, and joints. Silicone seals deteriorate over time, often unnoticed, and slow leaks behind tiles or beneath wet room floors can cause major structural damage. Locating leaks behind bespoke finishes can be complex, making comprehensive trace and access cover essential.

Underfloor Heating Systems

Hydronic underfloor heating uses extensive pipe networks hidden beneath flooring. A pinhole leak can spread widely before detection, and finding the source often requires lifting high‑value finishes such as stone or hardwood. Specialist trace and access cover is particularly important.

Basements and Lower Ground Floors

Basements used as kitchens, cinemas, gyms, or plant rooms are especially vulnerable. Water reaching a basement can render a property uninhabitable, with alternative accommodation and specialist reinstatement costs often exceeding the physical damage.

Swimming Pools, Hot Tubs, and Leisure Facilities

Pool plant rooms combine large volumes of water with pumps, heating systems, and chemical dosing equipment. Failures can release significant water into the building. Outdoor pools also face winter risks from frozen pipework.

Smart Home and Building Management Systems

Integrated systems controlling heating, lighting, and security can amplify the impact of a leak. Water affecting a central controller can disrupt multiple systems, requiring specialist contractors and extending repair times.

Second Homes and Holiday Properties

Unoccupied properties are at particular risk. A slow leak can go undetected for weeks, causing extensive damage to structure, finishes, and contents.

Reducing Escape of Water Risk: A Practical Checklist

  • Ensure everyone knows where the stopcock is and that it operates freely.
  • Have pipework inspected annually by an accredited plumber.
  • Lag exposed pipework in unheated areas.
  • Maintain minimum heating in unoccupied properties during cold weather.
  • Install smart leak detection systems for early alerts. Including automatic water shut off valves to prevent any further water from escaping the pipes and apparatus.
  • Inspect and replace silicone seals annually.
  • Prepare pools and spas properly for winter, draining exposed pipework.
  • Have underfloor heating systems checked annually for pressure drops or joint issues.

Taking proactive steps to understand and manage escape of water risk helps protect both the fabric of a home and the peace of mind of those who live in it.

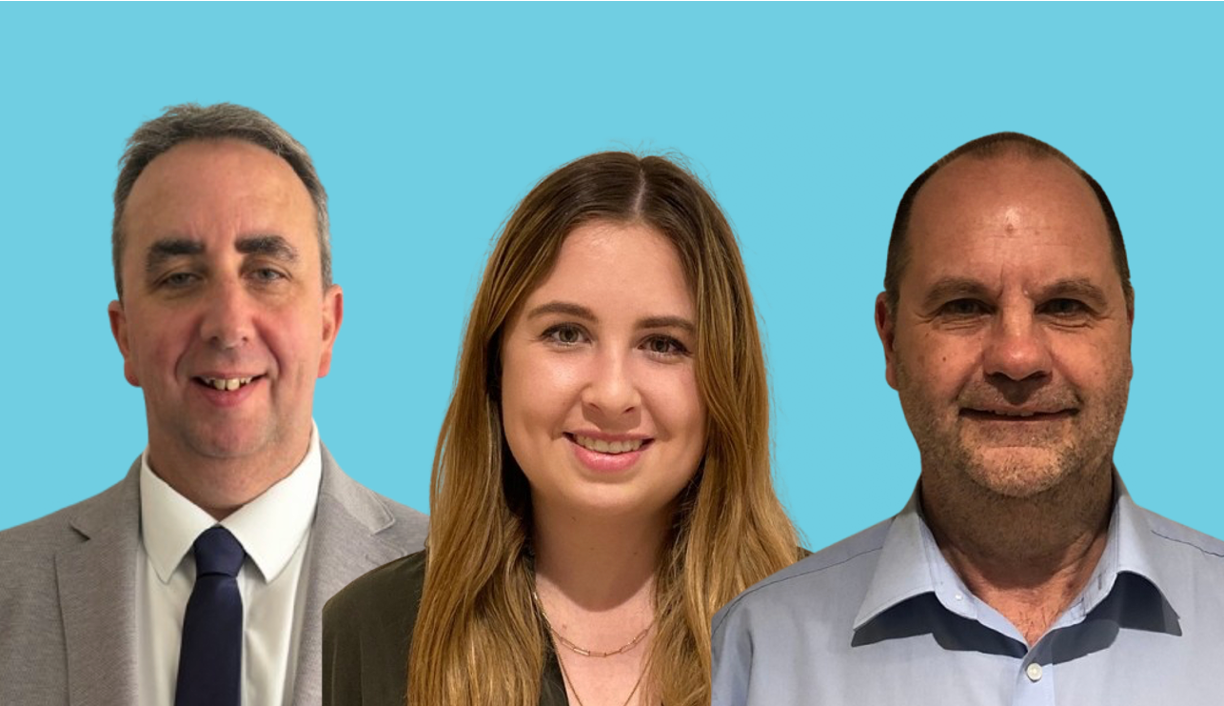
Meet the Team – Paul Brayne, Ellie Blackwell and Jon Grimwood

Meet the Team – Paul Brayne, Ellie Blackwell and Jon Grimwood 1224 706 James Hallam

Paul Brayne – Senior Client Adviser

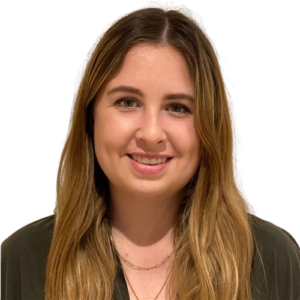
We are delighted to spotlight Paul Brayne, one of our highly experienced Senior Client Advisers within the Private Clients Team. Paul is known for his depth of industry knowledge, meticulous attention to detail, and commitment to delivering tailored solutions for clients with more complex insurance needs.
A bit about Paul

Outside of work, Paul enjoys staying active and social. He is a keen golfer and footballer, and also enjoys playing padel, walking, and spending quality time with family and friends. A fun claim to fame – Paul once appeared on Who Wants to Be a Football Millionaire, hosted by Chris Tarrant, as part of a Carling promotion!

What Paul does at James Hallam

Paul specialises in providing a bespoke service to clients, focusing on expert risk management and delivering true peace of mind. He works closely with clients who have more complex requirements, ensuring their insurance arrangements are carefully structured and fully aligned to their individual circumstances.

Experience & journey so far

Paul brings a wealth of experience to the team, having spent five years as an insurance underwriter with Eagle Star, Zurich, and Drake Insurance, followed by 25 years as a Private Clients insurance broker. This extensive background gives him a well-rounded perspective and the expertise to navigate even the most specialist areas of the market.

Since joining James Hallam just over a year ago, Paul has successfully placed cover for a number of highly unusual risks, further demonstrating his ability to find solutions in more challenging scenarios.

Making a difference

Paul’s experience and attention to detail enable him to approach each client’s needs with precision and care. His ability to understand complex risk profiles and translate them into effective insurance solutions makes him a trusted adviser to his clients.

A word from Paul

I see myself as a dedicated advisor who navigates the complexities of the specialist insurance market to create bespoke solutions that offer true peace of mind, not just a standard product.


Ellie Blackwell – Client Adviser

We are delighted to spotlight Ellie Blackwell, one of our valued Client Advisers within the Private Clients Team. Ellie is known for her positive attitude, strong communication skills, and dedication to delivering a smooth and supportive experience for every client she works with.

A bit about Ellie

Outside of work, Ellie has a passion for singing and has successfully completed up to Grade 5 Singing examinations with Trinity College London. Her commitment and creativity outside the office reflect the same enthusiasm she brings to her role each day.

What Ellie does at James Hallam

Ellie’s role focuses on renewals and ongoing client management, ensuring policies remain accurate, up to date, and aligned with clients’ needs. She works closely with clients to provide clear guidance and support throughout the renewal process, helping to make what can often be a complex area feel straightforward and well-managed.

Experience & journey so far

Before joining James Hallam, Ellie gained valuable experience at MarkerStudy, where she worked in Broker Support. This background has given her a solid foundation in the insurance industry and a strong understanding of client service and operational processes.

What Ellie brings to the team

Ellie brings a consistently positive approach and excellent communication skills to the team. She is focused on building strong relationships with clients and colleagues alike, and takes pride in ensuring queries are handled efficiently and professionally.

A word from Ellie

I thrive on delivering client-focused solutions and take pride in resolving complex insurance queries with clarity and care.


Jon Grimwood – Senior Client Executive

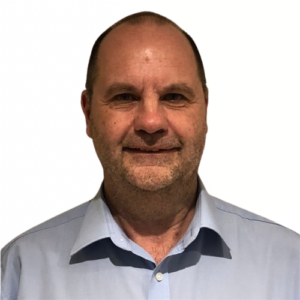
We are delighted to spotlight Jon Grimwood, one of our experienced Senior Client Executives within the Private Clients Team. Jon is known for his personable approach, strong relationship-building skills, and decades of experience in the insurance industry.

A bit about Jon

Jon has a great sense of humour and a memorable claim to fame – while he hasn’t ticked off bucket-list adventures like bungee jumping or climbing Mount Everest, hehasbeen in Dame Judi Dench’s kitchen while she was wearing pyjamas! Outside of work, Jon enjoys keeping life balanced and values the connections he builds both professionally and personally.

What Jon does at James Hallam

Jon focuses on building and maintaining strong client relationships, while also maximising new business opportunities. His approachable style helps clients feel at ease, making conversations about insurance straightforward and stress-free.

Experience & journey so far

With 40 years of insurance broking experience (a milestone he describes as “scary!”), Jon brings an exceptional level of knowledge and insight to his role. His long-standing career has equipped him with the expertise to support a wide range of clients and situations with confidence.

Making a difference

Jon prides himself on being relaxed and approachable with clients, recognising that insurance isn’t always an easy topic to engage with. By creating a comfortable and friendly environment, he has built lasting relationships and trust over the years, which continues to benefit both his clients and colleagues.

What Jon brings to the team

Jon contributes charisma, stability, and a strong sense of responsibility to the team. His experience and personality make him a valued and dependable presence within the business.

A word from Jon

After many years in the industry, I’ve learned that being yourself, building genuine relationships, and delivering consistent service are what truly earn clients’ trust.

Meet more of our experienced high net worth team here.

Sanctions Challenges in Marine Insurance: The Impact on Insurers, Brokers, and Maritime Clients

Sanctions Challenges in Marine Insurance: The Impact on Insurers, Brokers, and Maritime Clients 1000 563 James Hallam

Sanctions have become one of the most significant compliance challenges confronting the marine insurance industry. As global political pressures intensify and maritime trade continues to connect jurisdictions with conflicting regulatory frameworks, insurers and their maritime clients must navigate an increasingly complex environment. The marine sector is uniquely exposed: vessels cross borders daily, ownership and management structures frequently span multiple countries, and the financial ecosystem underpinning global shipping relies heavily on international banking channels.

In this context, sanctions risk is no longer a peripheral compliance matter—it is a central operational concern for underwriters, brokers, and shipowners.

The Compliance Burden on Marine Insurers

Marine insurers face substantial risk when dealing with sanctions, as even an inadvertent breach can result in severe penalties and lasting reputational harm. The challenge is compounded by the rapid pace at which sanctions evolve. A vessel, cargo owner, or charterer considered compliant at policy inception may become prohibited overnight. In a market characterised by long-tail policies and multi‑party supply chains, insurers must continuously monitor changing lists, advisories, and regulatory interpretations to ensure both legal compliance and contractual validity.

Payment flows pose another significant pressure point. Marine claims often involve international settlements between insurers, reinsurers, brokers, shipping companies, banks, and ports. Even when all insured parties are compliant, payments may still be blocked if a correspondent bank in the chain is sanctioned or if the transaction involves US dollars, which triggers US jurisdiction. This does not merely slow operations—it can temporarily or permanently prevent claim settlement, eroding trust between insurers and maritime clients who rely on timely recovery to maintain liquidity in vessel operations.

Screening processes, while essential, frequently generate excessive false positives. Variations in transliterated ship names, common surnames, or similar vessel identifiers often trigger alerts requiring human review. Marine insurers—who routinely handle complex submissions involving fleets, multiple assureds, and layered reinsurance structures—face significant workflow disruption as underwriting and claims teams sift through irrelevant alerts.

Another critical challenge arises from the opaque ownership structures typical in shipping. Vessels are frequently held through single‑purpose vehicles, flags of convenience, or offshore corporate arrangements designed for commercial flexibility rather than transparency. These structures can obscure the true identity of the ultimate beneficial owner (UBO) or controlling party. As regulators increasingly scrutinise indirect ownership and control, insurers must undertake deeper due‑diligence assessments than ever before, often across several layers of corporate entities.

The Impact on Shipowners, Charterers, and Maritime Clients

For shipowners and charterers, the consequences of sanctions compliance are immediate and operational. Insurance cover may be withdrawn with little notice if a ship, management company, or trading route suddenly becomes subject to sanctions. Even when the assured has no involvement with a sanctioned party, their ability to enter or exit certain ports, carry particular cargoes, or work with specific charterers may be curtailed, leaving them exposed to uninsured operational risk.

Maritime clients also face significant exposure through their trading partners. A fully compliant shipowner may find themselves unable to complete a voyage if a consignee, bunker supplier, or cargo owner becomes sanctioned mid‑transit. As sanctions regimes increasingly target sectors such as energy, metals, and maritime logistics, indirect exposure has become a routine business risk in shipping.

Financial transactions represent another area of vulnerability. The dominance of the US dollar in global shipping means that sanctions administered by OFAC can affect vessel operators even when no US entity is directly involved. A single US‑based intermediary bank can block a freight payment, charter hire, premium, or claim purely due to perceived sanctions risk. Delays in receiving freight or hire have immediate operational consequences for vessel owners, many of whom rely on predictable cash flow for bunker purchases, crew wages, and port fees.

The administrative burden on maritime clients has grown sharply as well. Insurers, brokers, and banks now require detailed information about ownership, management, voyage patterns, counterparty relationships, and cargo interests. While these checks are intended to protect parties on all sides, they lengthen underwriting timelines and may increase premiums where perceived sanctions exposure elevates the insurer’s operational risk.

Conflicting International Sanctions and the Marine Context

Marine insurance is inherently international, and the conflicts between different sanctions regimes create significant ambiguity. A vessel may legally trade under UK or EU rules but become immediately problematic if it enters a US port or requires a USD‑denominated settlement. Charterers, cargo owners, and insurers may be subject to different regulatory regimes based on domicile, creating complex compliance considerations with no universal interpretation.

This mismatch places marine insurers in a challenging position. Policy wordings must accommodate multiple legal systems, reinsurers may operate under different regimes, and claims handlers must assess the legality of a payment from the perspective of several jurisdictions simultaneously. As sanctions become more targeted—often focusing on specific ship types, cargo categories, or regions—these conflicts are likely to intensify.

Strengthening Risk Mitigation in Marine Insurance

To navigate this environment, marine insurers and clients must adopt proactive and rigorous compliance frameworks. Continuous monitoring of vessels, cargo interests, and corporate structures is essential, supported by technology capable of screening ship registries, AIS data, ownership records, and counterparty information in near real time. Enhanced due diligence—particularly around UBO identification—should be a standard component of underwriting and broking workflows rather than an occasional exercise.

Contractual clarity is equally important. Marine policies must articulate what happens if sanctions become applicable during the policy period, including implications for claims, coverage continuity, and termination rights. Clear drafting protects both insurer and assured and reduces the risk of disputes arising from sanctions‑triggered exclusions or cancellations.

Ultimately, effective sanctions compliance requires strong leadership engagement. In the marine sector—where commercial pressures can conflict with regulatory obligations—insurers, brokers, and shipowners must ensure that compliance is embedded at a strategic level. This not only mitigates legal risk but reinforces trust across the insurance value chain and strengthens market resilience in an increasingly complex geopolitical landscape.

Everard Insurance Brokers is the specialist marine division of accredited Lloyd’s broker James Hallam Limited. We can help you navigate the challenges of sanctions to ensure you get the marine insurance you need for your maritime operation.

Learn more about our dedicated marine insurance services.


Navigating the Superyacht Insurance Market: What It Takes to Place These Exceptional Risks

Navigating the Superyacht Insurance Market: What It Takes to Place These Exceptional Risks 1000 563 James Hallam

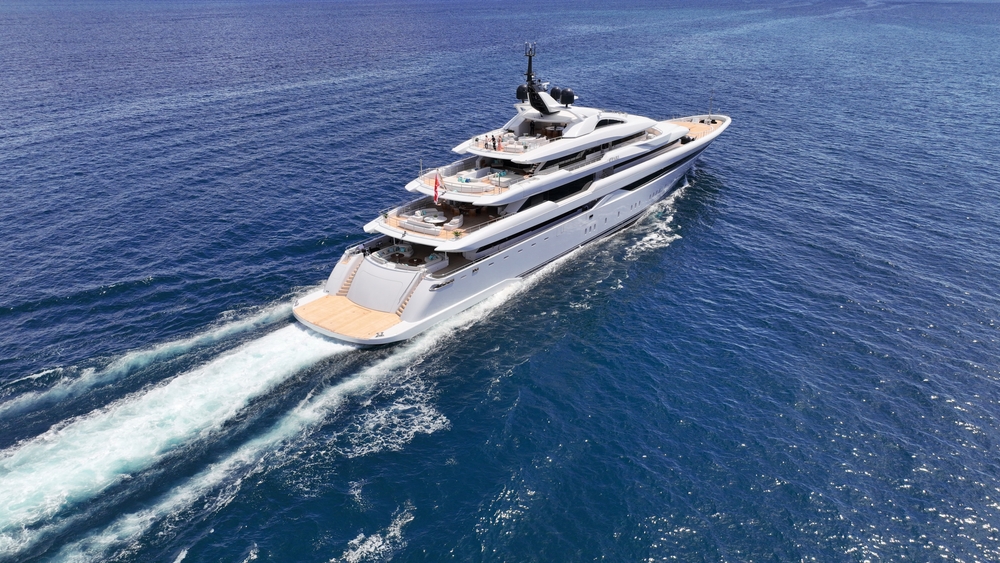
At Everard Insurance Brokers, we understand that the world of superyachts is one of the most specialised and demanding areas of marine insurance. With vessels frequently exceeding 60 metres, multi‑million‑pound build values, and increasingly sophisticated operational profiles, placing superyachts in today’s market requires technical expertise, precision, and a forward‑thinking approach to risk.

In a landscape shaped by tightening capacity, regulatory developments, and rapid growth in the size and complexity of modern yachts, our role as an independent broker is more important than ever. We advocate for our clients, analyse the market thoroughly, and deliver tailored solutions that reflect how each vessel truly operates.

Understanding the Superyacht Risk Landscape

Superyachts are luxury assets, but their operations often resemble those of commercial vessels; bringing a unique set of risks that require detailed understanding.

High Hull Values

Today’s new builds can exceed £200 million, and annual refit programmes can rival the budgets of small businesses. Insurers expect comprehensive documentation, from build specifications and maintenance histories to shipyard risk assessments.

Global Navigational Ranges

Whether cruising the Mediterranean, Caribbean, or remote expedition regions, each area presents its own challenges:

  • piracy exposure
  • weather‑driven CAT risk
  • differing regulatory and compliance requirements

Complex Crew Structures

Large, rotating crews—including specialist roles such as engineers, chefs, medical staff, and helicopter pilots—introduce significant P&I and employer liability considerations.

High‑Value Third‑Party Risks

Charter operations, VIP guests, and large‑scale onboard events increase liability exposures. Reputational and privacy risks continue to grow as well.

The Superyacht Market: Capacity, Conditions, and Carrier Appetite

Superyachts sit within a niche and specialist segment of the marine market, with London remaining a central hub for underwriting. However, capacity is fluid and influenced by:

  • recent loss activity (particularly fire, machinery, and refit‑related claims)
  • changes in reinsurance cost and availability
  • geopolitical developments impacting global cruising patterns

Underwriters are now more selective, with appetite influenced by vessel age, build yard, ownership structure, management approach, and operational profile. At Everard, we continue to:

  • monitor market appetite across insurers
  • maintain trusted relationships with specialist underwriters
  • anticipate shifts in pricing and capacity to secure the best possible outcomes

Preparing a Robust Submission: The Everard Advantage

A strong submission is essential for competitive pricing and robust coverage. Our focus is on clarity, transparency, and presenting a compelling narrative for each superyacht.

A high‑quality submission includes:

  • key vessel specifications: build details, materials, flag, classification
  • operational profile: cruising patterns, chartering, annual movements
  • crew details: qualifications, experience, training, and retention
  • management & maintenance: ISM compliance, refit schedules, professional oversight
  • claims history: context, lessons learned, and mitigation steps taken

A thoroughly prepared submission reduces underwriting queries and strengthens our negotiating position, ensuring the client’s vessel is represented accurately and favourably.

Risk Mitigation: Demonstrating Proactive Management

Superyacht owners and managers are increasingly focused on risk control—and insurers respond positively when this is evidenced clearly. We work closely with clients to highlight measures that materially influence market appetite, such as:

  • advanced fire detection and suppression technologies
  • professional yacht management structures
  • robust onboard cybersecurity controls
  • weather routing and voyage planning systems
  • structured crew training and competency programmes

Highlighting these measures often leads to broader coverage and more competitive terms.

The Art of Negotiation: Balancing Expectations With Market Realities

Superyacht owners expect a tailored, responsive service. Balancing these expectations with a market that is often cautious requires experienced negotiation and clear communication. This can include navigating:

  • increased deductibles
  • stricter policy wordings
  • heightened scrutiny for older vessels
  • insurer requirements during refits or yard periods

At Everard, we act not only as brokers but as trusted advisors, ensuring that coverage aligns with the vessel’s operational requirements and the owner’s long‑term plans.

Emerging Trends Shaping the Superyacht Market

Several developments are shaping the future of superyacht insurance:

  • Sustainability: hybrid propulsion systems, alternative fuels, and eco‑focused design
  • Expedition yachts: increasing voyages to challenging and polar environments
  • Digitalisation: enhanced connectivity increasing cyber and systems exposures
  • Mega‑builds: rising numbers of yachts over 100m stretching capacity and underwriting comfort

Understanding these trends allows us to provide forward‑thinking guidance and prepare clients for how the market is evolving.

Expertise Makes the Difference

Placing superyachts in today’s marine insurance market demands technical capability, strong insurer relationships, and a clear understanding of how each vessel is operated. As yachts continue to grow in size, complexity, and sophistication, the broker’s role becomes even more critical.

At Everard Insurance Brokers, we combine specialist knowledge with independent, and a client focused service, ensuring that every vessel we place is protected with confidence, clarity, and care, wherever in the world it sails.

Get in touch with our team of experts to discuss your specific superyacht insurance requirements.


How To Prevent Employee Theft in Retail

How To Prevent Employee Theft in Retail 1000 667 James Hallam

We recently published a guide to preventing theft from shops. In that guide, we focused on addressing theft from shoplifters. In this post, we will take a closer look at employee theft – why it happens, and how to prevent it.

Understanding the Impact of Employee Theft in Retail

According to research by Retail Economics and Thruvision, employee theft accounts for around 40% of all thefts experienced by UK retailers, which could account for a loss of about £3.2 billion a year.

But employee theft will have some added costs beyond the financial losses. It can affect morale, and lead to a culture of mistrust and suspicion among staff. It can lead to disciplinary actions and legal procedures, which will disrupt your operations, while increasing staff turnover and recruitment costs.

Plus, if word gets out that your business is having a problem with employee theft, then it could damage your reputation. After all, if you cannot keep your own stock safe, then who knows what else you are overlooking? This could affect your ability to attract suppliers, and it may even make some customers reluctant to buy from you.

Common Causes of Employee Theft

Why would an employee steal from their employer? For any number of reasons, including:

  • Financial Hardships – If an employee is struggling outside of work, they may be tempted to steal from the till, the shop floor, or the stockroom, to help make ends meet.
  • Resentment – If your employees are not happy in their jobs, or if there are poor relationships between staff and management, then employees may turn to theft as an act of protest.
  • Opportunism – Sometimes, the opportunity to steal might just be too great to resist. If an employee is handling a large amount of cash, and they notice that there is nobody around, then they might think: “Who’s going to miss the odd note or two?”
  • External Pressure – If you do not address employee theft in your shop, a negative workplace culture could take hold, and some employees may find themselves driven to theft as a result of peer pressure. Or worse, employees might get pressured by outside forces, such as criminals, to lift cash or stock from the premises.

How To Prevent Employee Theft in Your Shop

There are a number of actions you can take to help prevent theft in your shop including:

  • Employee Screening – Conduct thorough background checks on all of your new hires, particularly if their role will involve handling cash, or if it will give them access to high value stock.
  • Employee Training – During induction, make it clear to staff that you take a zero tolerance approach to theft, but be sure to explain why, highlighting how employee theft harms everyone.
  • Security Measures – All of the systems that can help prevent shoplifting can also help prevent employee theft: CCTV, thorough stock management procedures, mirrors to eliminate blindspots, security tagging, and so on. You should also implement strict controls on who can handle cash, with robust security procedures for doing so.
  • Anonymous Reporting – If a staff spots another employee stealing stock or money, they may be reluctant to report the incident, as they might be wary of reprisals. But if you allow for anonymous reporting systems, staff can report incidents in total peace of mind that they will not face any direct retaliation.
  • Staff Support – Finally, we mentioned above how unhappy or dissatisfied staff may turn to theft. With regular performance reviews, you can identify any possible sources of discontentment as early as possible, while also helping to build trust between managers and employees.

Get The Right Cover For Your Shop

A comprehensive retail insurance policy will not prevent employee theft. But it can give you the cover you need to bounce back from any major disruptions or significant losses.

James Hallam is an independent Lloyd’s broker with a dedicated team of experienced insurance professionals who care about protecting your shop. Whether you run an online store, a single high street shop, or a chain of shops, we can help you get the cover you need at a price you can afford.

Find out how we can help your shop today.