SME

What is Deterioration of Stock Insurance?

What is Deterioration of Stock Insurance? 1000 568 James Hallam

Deterioration of stock insurance can provide essential cover for any business that sells or stores perishable goods.

In this post we will explain what deterioration of stock insurance is and what it covers, along with some common exceptions and limitations to the cover.

What is Deterioration of Stock Insurance?

If an unexpected event causes your perishable stock to spoil or degrade, then deterioration of stock insurance can cover your losses. Specifically, this cover can provide some financial compensation should deterioration make your stock unsuitable for sale.

Business insurance policies generally will not offer cover for stock deterioration as standard. To get the protection you need, you will either need to get a specialist policy, or you will need to add the cover to an existing policy.

Some insurers may specify that you introduce certain measures in order to safeguard your stock, as a condition of cover. This might include installing a failsafe, such as a backup power system, while staying on top of equipment cleaning, servicing, and maintenance schedules.

What Does Deterioration of Stock Insurance Cover?

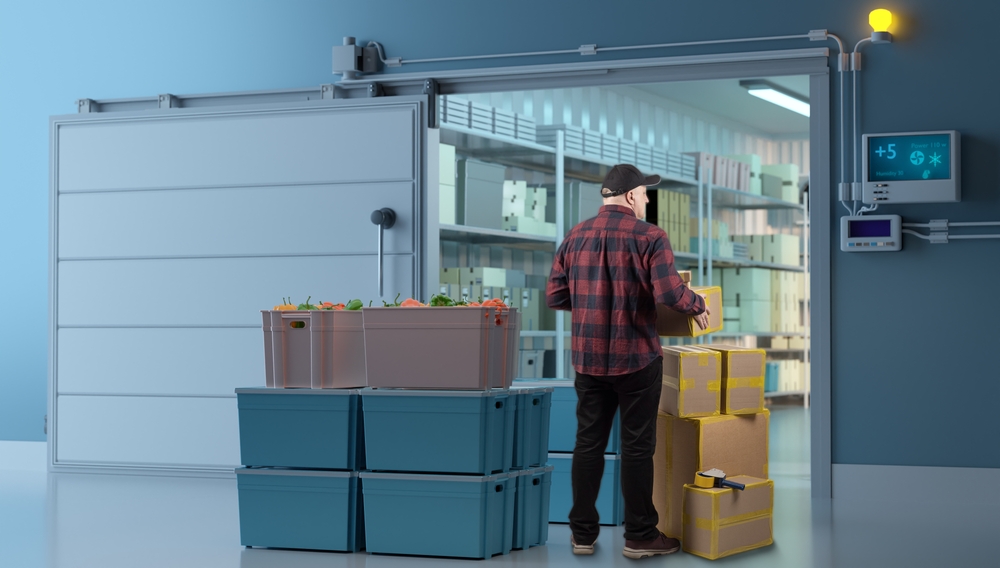
Deterioration of stock insurance covers loss or damage of perishable goods that need to be stored at certain temperatures.

For example:

  • A power failure causing a fridge or a freezer to fail.
  • Water damage from leaks or flooding.
  • Transport issues – for example, a truck transporting temperature-controlled goods is involved in an accident, resulting in equipment failure.
  • Damage from insufficient heating, cooling, or unwanted temperature fluctuations.

Are There Any Exclusions and Limitations to Deterioration of Stock Insurance?

Most deterioration of stock insurance policies will list a number of exclusions and limitations. These might include:

  • Poor Maintenance and Neglect – If a fridge, freezer, or other equipment fails as a result of poor maintenance, your insurer may reject your claim. Stay on top of servicing and cleaning schedules to ensure you get the cover you need.
  • Foreseeable Events – Similarly, your insurer will likely reject your claim if your stock deteriorates as a result of an incident you could have foreseen and prevented. For instance, you might have to take special measures to protect your stock in the event of a heatwave. If you were aware that high temperatures were forecast, but you did not work to secure your stock, then you may not be covered for any loss.
  • Natural Deterioration – Deterioration of stock insurance is designed to cover sudden and unexpected events. It will not cover losses due to slow or gradual decline.
  • Pre-Existing Problems – If your stock was already faulty before you put it into storage, then your insurance probably will not cover you for any unexpected events leading to total loss.
  • Security Issues – If your equipment fails as a result of a break in, your insurer may reject your claim if they find that you did not take adequate steps to secure your premises. Most policies also include standard exclusions for losses due to war, terrorism, riots, and civil unrest.

Who Needs Deterioration of Stock Insurance?

Any business that stores, transports, or sells perishable goods could benefit from deterioration of stock insurance. This might include:

  • Cafes, restaurants, bakeries, butchers, delis, takeaway shops, and any other business that prepares and sells food on the premises.
  • Greengrocers, corner shops, newsagents, off-licenses, wine merchants, and supermarkets.
  • Pharmacies, along with any business that stores or sells cosmetic and beauty products.
  • Florists and other horticultural businesses.
  • Warehouses that specialise in storing any kind of perishable good.

Get The Cover You Need for Your Stock

James Hallam is an independent Lloyd’s broker with access to a hand-picked selection of A-rated insurance providers.

We can help you get the specialist stock deterioration insurance you need to protect your business against unexpected events. We can also advise you on essential risk management procedures that could make stock deterioration less likely, and we can show you how to evidence these measures to your insurer in order to potentially reduce the cost of cover.
Get in touch for a free quote today.

How To Identify Risks in Your Business

How To Identify Risks in Your Business 1000 667 James Hallam

There is more to risk management than identifying possible sources of accidents and injuries. It is also important to identify risks that could lead to inefficiencies, disrupt your operations, increase your overheads, and affect your cashflow.

In this post we will explore how to identify risks in your business, and establish the process for managing, mitigating, or eliminating these risks.

Common Risks for Every Business

When assessing the sources of risk in your business, you should consider:

  • Property Risks – Including damage from fire, flood, subsidence, and other incidents, along with losses from theft, vandalism, and other crimes.
  • Finance Risks – Including cash flow fluctuations, debt management, and economic uncertainty.
  • Operations Risks – Including bottlenecks and inefficiencies that could lead to risks, possible hazards posed by outdated or faulty tech, and poor quality control measures.
  • Cyber Risks – Including financial and reputational damages from cybercrime, and liability costs from data leaks and data loss.
  • Legal Risks – Such as claims involving intellectual property theft, dishonesty, negligence, and fraud.
  • Supply Chain Risks – Including dependencies, issues with transportation, and potential disruption.
  • Stock Risks – Such as losses from theft or spoilage. You will have to consider additional risks if you routinely store or work with hazardous materials.
  • Staff Risks – Including issues with compliance, training, skill gaps, and turnover.

How Create Your Risk Management Process

For every risk that you identify for your business, you should also identify the following:

  • Who is at risk? Who might be affected by a particular risk, and how might it affect them? Consider whether each risk will affect staff, customers, contractors, delivery drivers, visitors, or a combination of the above. Also bear in mind that some people may experience risks differently. Someone with vision or hearing problems, for example, may find it harder to follow evacuation procedures.
  • How likely is the risk? Plus, how severe would the outcome be? This could range from financial or reputational damages to serious injuries and death. After you have quantified your risks in this way, you can prioritise them based on their probability and severity. This will allow you to allocate your risk management resources effectively.
  • How are you going to manage, mitigate, or eliminate the risk? The specific steps you take will of course depend on the risk in question. Though for every action you identify, you should also establish who is responsible for carrying it out, along with a timeframe for completing it, and a process for reviewing the risk assessment.

Managing Your Business Risks

Read our essential guide to risk management for businesses. We also have a number of specialist guides for certain kinds of businesses. Some of these offer general risk management advice, but others focus on specific risks, such as fire, theft, or cybercrime.

General Risk Management Guides

Cyber Risk Management Guides

Fire Risk Management Guides

Get Tailored Insurance For Your Business

James Hallam is an independent Lloyd’s broker with access to a hand-picked selection of insurance providers.

We can help you understand the risks your business is facing, and we can advise you on how to effectively manage these risks. We can then help you access the business insurance you need, and we can show you how to evidence your risk management processes in order to make savings on the cost of cover.

Get in touch for a free quote today.

Why is Retail Theft Rising in 2026?

Why is Retail Theft Rising in 2026? 1000 666 James Hallam

Shops across the UK are reporting a rise in retail theft. According to figures from the Office for National Statistics (ONS), over 500,000 incidents were reported in 2025 – 2026, a rise in 5% compared to the previous year.

In this post we will outline some of the underlying causes of this rise in retail theft, before exploring some ways you can help to prevent theft in your store.

Underlying Causes of Retail Theft Rising

There are a number of factors which affect crime rates, particularly theft. In 2026, we are seeing the following contributory factors:

  • Cost of living crisis
  • Organised crime
  • Staffing issues
  • Rise in self-checkouts

We’ll explore each of these individually below to find out more about the causes and how it may impact target items.

The Ongoing Cost of Living Crisis

The UK has been struggling with high inflation rates for a number of years, which greatly increased the cost of living for millions.

Rising food costs may have contributed to the increase in shoplifting. Baby formula is one of the most commonly stolen items in the UK, and this is likely because it is both essential and expensive.

Organised Crime

Some retail bodies claim that organised crime is driving a rise in retail theft.

Some of this may be relatively small scale, such as the thieves who steal premium cuts of meat to sell to pubs and other establishments. But some retailers have fallen victim to larger gangs that have targeted multiple stores in succession.

Even worse, this form of theft seems to be linked with rising incidents of violence and abuse against frontline retail staff.

Staffing Issues

Rising costs have forced many stores to cut staff hours, and the UK workforce as a whole has shrunk in recent years.

Fewer staff on the shop floor means that there are fewer people to look out for the signs of shoplifting, and more blind spots for thieves to operate in.

The Rise of Self-Checkouts

Many stores have started offering self-checkout services, partially as a way of managing costs, and partially as a way of offering a more streamlined experience to customers.

Some self-checkout areas feature systems designed to prevent theft, such as security cameras, and gates that will only open if the customer scans a code they receive after purchase. But nonetheless, the perceived lack of security around self-checkout areas may be fueling a rise in shoplifting.

Some customers find self-checkout systems confusing, which may mean they unintentionally take some items without paying. And while they may not be shoplifting in the strictest sense, this will still lead to losses for the store.

The Impact of Retail Theft on Stores

How To Reduce Theft in Your Store

We have a number of guides on our site to help you address retail theft in your store:

It is also important to address the risks of employee theft in your store. Read our full guide to understanding and preventing employee retail theft.

Get The Right Cover For Your Retail Store

A specialist retail insurance policy can cover your store for many of the losses you may experience as a result of theft and other incidents, subject to policy terms, conditions and exclusions.

James Hallam is an independent Lloyd’s broker with an experienced team of insurance professionals who care about protecting your store.

Find out how we can help your shop today.

How to Prevent Slips, Trips, and Falls in Your Shop

How to Prevent Slips, Trips, and Falls in Your Shop 1000 667 James Hallam

Slips, trips, and falls are a major issue for retail businesses, and there are severe penalties for shops that do not take the time to address the risks.

In this post we will explore some of the possible underlying causes of slips, trips, and falls in the retail environment. We will also outline how you can address these risks in your store.

What Causes Slips, Trips, and Falls in Shops?

There are a number of different causes for slips, trips and falls in shops, including:

  • Clutter – Any stock or equipment left in walkways can create a trip hazard for both staff and customers.
  • Liquids – A spilled liquid creates a slipping hazard. But customers may also slip on a freshly cleaned surface, particularly if there are no warning signs about, or if staff used too much cleaning product.
  • Mats, Rugs, and Tiles – People may trip over a rumpled mat or rug, or a loose tile on the floor.
  • Environmental factors – People may fail to spot slip or trip hazards if the lighting is poor. Or they may lose their footing if they do not see a step or a ramp.

How To Prevent Slips, Trips, and Falls in Your Shop

To help reduce and prevent slips, trips and falls in your shop, you should consider:

  • Staff Training – Train your staff to spot the risks that could contribute to slips, trips, and falls, and make sure that everyone knows what to do to address these risks. Also make a point of recording and reporting any incidents that occur, specifying exactly what went wrong, and outlining the steps you will take to prevent further incidents.
  • Stay On Top of Cleaning – Establish a cleaning rota and aim to clean up any spillages as soon as possible. It is also important to use the right cleaning products, and in the right quantity. Use the wrong product and you may not effectively remove a spillage. And use too much of a product and you could make the slipping hazard even worse.
  • Make Customers Aware of the Risks – After cleaning, place signs warning customers of slippery surfaces. If there are any steps or ramps on the shop floor, make sure they are clearly indicated, with signage if necessary.
  • Stay On Top of Maintenance – Replace faulty lighting, damaged floor tiles, and any other faults that could lead to accidents as soon as possible.
  • Reduce Clutter – Never leave stock or cleaning equipment unattended in walkways. This goes for your storeroom as well as your shop floor. Your staff are just as liable to get injured by a slip, trip, or fall as your customers.

Risk Management and Insurance

Addressing the common causes of slips, trips, and falls should form a part of your wider risk management strategy. Read our full guide to risk management for retail businesses.

As we mentioned above, there are severe penalties for any store that does not take the time to mitigate slipping and tripping hazards. The Health and Safety Executive has numerous case studies of slips and trips that ultimately cost retail stores dearly.

Specialist retail insurance can help cover any legal costs or settlements that may arise as a result of an incident in your shop. You have a legal duty to get employers liability insurance to cover the risks for your staff, while public liability insurance can cover any incidents that affect customers, contractors, delivery drivers, and other members of the public.

There are strong links between risk management and insurance. Your insurer may require you to implement certain risk management processes as a condition of your cover. But at the same time, if you can evidence your risk management efforts, you may be able to make a saving on the cost of cover.

Get The Right Cover For Your Retail Store

A specialist retail insurance policy can help provide cover for losses you may experience as a result of slips, trips, falls, and other incidents, subject to policy terms, conditions and exclusions.

James Hallam is an independent Lloyd’s broker with an experienced team of insurance professionals who care about protecting your store. We can help you access the cover you need for your business, and we can also show you how to evidence your risk management in order to make potential savings on your premiums.

Find out how we can help your shop today.


How To Value Vintage Clothing For Vintage Shops

How To Value Vintage Clothing For Vintage Shops 1000 667 James Hallam

If you run a vintage clothes shop, or a general second hand shop that sells vintage clothes among other goods, then you may have wondered just how much you should be charging for your vintage items.

In this post we will explore some ways you can value your vintage clothing, to help you set prices that reflect each item’s true value that your customers will be happy to pay.

What Affects the Value of Vintage Clothes?

Here are the some of the things that can impact the value of any item of vintage clothing:

  • Label – Some labels will always be worth more than others. Dior, Chanel, and other high-end designer labels will always attract high prices. But other labels might vary in value, depending on certain trends.
  • Condition – Items in good condition will be worth more than items that are soiled, worn, or damaged. However, some items have “provenance”. If an item is particularly rare, or if you can prove that it was once owned or worn by a famous person, then buyers might be more willing to overlook a bit of wear and tear.
  • Quality –Mass produced items made from cheap materials will be worth less than rare items made from high quality materials and with obvious care and craftsmanship.

How To Value Vintage Clothing

There are a few things you can try to help you determine the value of any item in your stock. Including:

  • Check online listings
  • Immerse yourself in vintage culture
  • Get a professional valuation

Some of these techniques might prove useful if you need to value large volumes of clothes as quickly as possible. Other techniques might be more costly and time-consuming, and so should be reserved only for items you suspect might be particularly valuable.

Be sure to test and adjust your prices. Be flexible, and be prepared to accept best offers rather than your asking price. Also be aware of how the seasons might affect an item’s value. People will likely pay more for a coat in the autumn or winter than they would during the height of summer.

We’ll go through each of the actions you can take in more detail below.

Check The Online Listings

Head to any site where people can buy and sell vintage clothing: Vinted, Depop, and eBay are good places to start.

If possible, look up the item’s label. But if the item does not have a label, try to find similar items based on its type, size, style, fit, pattern, and the approximate decade in which you think it might have been manufactured.

Pay more attention to final sale prices rather than listing prices. Ultimately, an item is only worth whatever people are willing to pay for it. You might see one item listed at, for example, £300, and another almost identical item that sold for around £50. If the listed item does not sell at the higher price, this suggests that the item’s true value is closer to £50 than £300.

Immerse Yourself in Vintage Clothing Culture

This is more of a long-term strategy that might help you develop your “eye” for spotting potentially valuable items, and your instinct for how much it might be worth.

Attend as many vintage events as you can and while you’re there:

  • Pay attention to what people are selling, and what people are buying.
  • Listen to the sort of questions buyers ask, and the sort of information sellers provide.
  • Talk to other sellers, either in person or online.
  • Share insights, and you can start to develop a joint understanding of current and emerging trends.

It can also help to pay attention to auctions. Shedd is a dedicated vintage auction marketplace in which every single item is initially listed at a low price with no reserve. This means that the sale prices may reflect authentic market demand from real buyers.

Finally, look out for industry guides. There may be specialist guides to current trends and estimated valuations for certain styles or brands.

Get a Specialist Valuation

If you come across an item that you suspect may be rare or valuable, and you want to make absolutely sure that it is not a fake, then it might help to get a specialist valuation.

A specialist can advise you on the item’s provenance, and they may even be able to help you restore the item to make it even more valuable.

Obviously, this will take time, and specialists evaluators will not work for free. But if you suspect you have a genuine Gucci on your hands, for instance, then any costs may be entirely justified.

Once You Understand How Valuable Your Stock Is, Be Sure To Get It Covered

You can get insurance that will cover you for the risks associated with stocking and selling vintage clothes. Stock insurance will cover your valuable vintage items for loss or damage whether they are on your shop floor, in storage, or in transit.

When arrangine stock insurance, you’ll need to think about:

  • Accurate valuations: When getting cover for your vintage clothing business, it is helpful to provide your insurer with an accurate valuation figure for your stock. This way, they can ensure you are covered for the right amount, so that you will get the settlement you need should you ever need to make a claim.
  • Particularly valuable items: Some insurers may only insure your stock up to a certain value, so it is also important to notify your insurer about any particularly valuable items in your stock, just in case they would push your cover level beyond the limit.
  • Trends and value fluctuations: And remember that the value of vintage clothes tends to change! So be sure to revise your valuations as often as possible based on the latest trends, and to give your insurer an up-to-date value every time you renew your policy.

Get Vintage Clothes Shop Insurance From James Hallam

James Hallam is an independent Lloyd’s broker with a dedicated team of insurance professionals who care about protecting your business, whether you sell vintage clothes exclusively, or among other items in a second hand shop.

Find out how we can help you today.

How To Protect Your Business From Extreme Weather Events

How To Protect Your Business From Extreme Weather Events 1000 781 James Hallam

In recent years, the UK has faced heatwaves, floods, and a number of severe storms.

In this post we will explore the risks that your business might face should extreme weather events become more common in the UK, before discussing how you can manage and mitigate these risks.

Key Risks of Extreme Weather To Businesses

Heatwaves
High temperatures can lead to increased health risks for your staff and your customers.

The risk could be particularly high for anyone who works in a role that demands a lot of physical activity, or in environments where temperatures are already high, such as factories, warehouses, and industrial settings.

Storms
Storms can lead to travel disruption, which could affect your supply chain or your deliveries.

A storm could also lead to property damage, such as from falling trees or branches, and it could even lead to power cuts.

And a power cut could affect your business in a number of ways: You could lose your temperature controlled stock if your fridges or freezers fail, and if your security systems go down you may be more vulnerable to theft or vandalism.

Floods
Violent storms can also lead to flash floods, which could cause devastating damages to any kind of business.

And it is not just businesses located on flood plains that need to consider the risk of flood. Heavy rains could overwhelm drainage systems, which could lead to floods in areas that are not usually at risk of flooding.

How To Protect Your Business From Extreme Weather Events

If extreme weather events are becoming more common in the UK, below are some strategies that you could implement to safeguard your business against all kinds of weather-related risks, including:

  • Pay attention to Government warnings and weather alerts
  • Manage extreme temperatures
  • Flood planning and protection
  • Storm planning and protection
  • Insurance cover

We’ll explore each of these in more detail below.

Forecasts and Government Weather Warning Notifications

Pay attention to the weather forecast, and pay particular attention to any Government warnings about extreme weather events, and the possible risks they may bring.

When it comes to floods, take a look at the Flood Hub’s flood risk maps, which provide both a five-day flood risk forecast, along with potential long-term flood risks. You can also sign up for official Government flood warnings, which means you can get a call, text, or email if there are any particular risks in your area.

How to Manage Heatwaves in the Workplace

The Health and Safety Executive (HSE) does not specify a maximum working temperature for any workplace. This is because all workplaces are different, and some employees may routinely experience high temperatures as part of their work, such as those who work in factories, industrial settings, and warehouses.

However, the HSE does provide guidance on “thermal comfort”, outlining how high temperatures could encourage staff to exercise less caution and take more risks. For example, they may struggle to focus or concentrate, they may choose not to wear certain items of PPE, and they may cut certain corners that could put themselves, or others, at risk.

If you are worried about how a heatwave might affect your employees or your business, there are certain policies you could introduce to help your staff keep cool. The British Safety Council has published advice on staying safe at work during heatwaves, which includes:

  • Relaxing dress codes
  • Allowing staff to take more frequent breaks
  • Providing a supply of cold drinks
  • Introducing more flexible working policies

Protecting Your Business From Flooding

Sign up for alerts: Above we mentioned how signing up for flood alerts can give you an advanced warning that could give you time to prepare. However, a severe storm could lead to flash flooding, which could strike your business without warning.

Consider stock and equipment placement: There are some measures you could introduce that could help to limit the damage of any flooding on your premises. This can include storing any high-value stock or equipment on high shelves or upper floors.

Invest in drainage: You could also invest in systems that could help reduce the risks of flash flood affecting your business. For instance, you can install non-return valves on your business’s drains, along with the inlet and outlet water pipes. With these in place, even if the local drainage systems get overwhelmed, it will be less likely that any flood water will enter your premises.

Create a flood response plan: Beyond this, it is worth taking the time to design a flood response plan for your business. This could include steps staff should take to keep themselves safe, along with contingency plans to limit disruption to supply lines, deliveries, and other aspects of your operation.

Read our full guide to preparing your business for a flood. Though this guidance refers specifically to retail businesses, it features tips that could help to keep any business safe.

Protecting Your Business From Storms

Unless high winds cause a tree to fall on your business premises, then it is unlikely that a storm itself will threaten your business. However, long periods of heavy rain could make flash floods more likely, and stormy weather could lead to power cuts and other disruptions.

The best way to protect your business from storms is through assessing all the possible risks that a storm could bring, before designing a risk management plan to help you mitigate these risks:

  • Back-up generators to help you deal with power cuts. You could also ensure that there will always be backup power for your fire and security systems, so that power outages will not put your business at increased risk of fire, theft, or vandalism.
  • Continuity plans for dealing with disruption and business interruption. How would you manage any delayed deliveries or shipments, for example? Who would you notify, and what measures would help you manage operations until you get back on track?
  • Working arrangements: If your staff are temporarily unable to travel due to adverse weather conditions, could you introduce temporary flexible working arrangements that would enable them to work from home?
  • Safety protocols: Would a storm put any of your employees at risk on the job? Your employee safety procedures should specify the conditions in which employees should stop working and instead vacate to a place of safety, particularly if they work in a high-risk environment such as a construction site.

How Insurance can Protect Your Business From Extreme Weather Events

James Hallam is an independent Lloyd’s broker with a team of insurance professionals who are dedicated to protecting your shop from the risks you face from extreme weather.

We can help you understand the specific risks your business faces, and we will ensure that your business insurance will give you the cover you need when you need it most. For example, we can help you access specialist business insurance that will cover you for flood risks, and we will make sure that your business interruption insurance will help cover costs while you get back on track.

Learn more about our tailored insurance solutions for SMEs, and get a free quote today.


How to Secure High-Theft Items in Retail

How to Secure High-Theft Items in Retail 1000 572 James Hallam

In 2025 – 2026, police recorded 507,100 shoplifting offences in England and Wales. The annual figures suggest that shoplifting has become increasingly common every year following the 2020 – 2021 lockdowns, and there are significantly more annual recorded incidents now than there were just 10 years ago.

In this post we will outline the sort of products shoplifters are most likely to target, before exploring some strategies to help you protect the high-theft items in your store.

Why Do Thieves Target Some Products More Than Others?

There are a few things that might make a certain item particularly attractive to thieves:

  1. Its value. A lot of the time, shoplifters steal items not because they want or need them, but because they intend to sell them. Some items have a higher demand and thus fetch a higher price on the black market than others.
  2. Its size. The smaller the product, the easier it is for thieves to discreetly lift it from the shelves and hide it.
  3. Its security. Shoplifters may be more likely to attempt a theft is an item is located in a part of the store where they are unlikely to be seen.

What Are The Most Commonly Stolen Items From Shops?

These are some of the most common items shoplifted in the UK:

  1. Baby formula. Unfortunately, this may be the most commonly stolen item in the UK simply because it is essential, it is expensive, and many new parents may be struggling to make ends meet.
  2. Steak, lamb, bacon, and other premium cuts of meat. Some thieves will steal meat for their own personal use. Others will aim to sell it to pubs and other establishments via online marketplaces.
  3. Cosmetics and beauty products. This might include makeup, fragrances, and razor blades. These items are small and lightweight, and thus relatively easy to hide, and they tend to sell for high prices online.
  4. Some thieves may lift bottles of wine or vodka from the shelves for their own use. But others may intentionally target premium spirits, such as whiskey or artisan gin, in order to sell them online.

Of course, even if you do not sell any of these items in your store, you may still sell certain high value items, such as electronics, tobacco, and vaping products, that thieves may target with the intention of selling them online.

How to Secure High-Theft Items in Retail

We recently published a guide to how you can help prevent shoplifting in your store. We also have a guide to dealing with the increased risk of shoplifting at busy times of the year, such as Christmas.

There are some special measures you can introduce to protect the high-theft items in your shop, such as:

  • Rethink your store layout
  • Locked display cabinets
  • CCTV
  • Security Tags
  • Staffing

We’ll explore each of these in more detail to identify exactly how they can help you to reduce and deter theft.

Rethink Your Store Layout

Aim to keep any high value items behind the till, so that customers have to actually request them from staff. Some stores have taken to keeping high-theft items such as baby formula and alcohol behind the till.

When thinking about your store layout, consider lines of sight, and aim to remove any blind spots where thieves could operate unobserved. Also try to make sure there are clear sight lines at your entrance, so that customers would not be able to enter or leave without your staff noticing.

Locked Display Cabinets

If you cannot keep all of your high value items behind the till, then store them in locked display cabinets, so that once again, customers will not be able to access them without asking a member of staff.

Again, consider your store layout. Try to keep these locked display cabinets in a well-lit area as close to the till as possible.

CCTV

You should ensure you have CCTV coverage of your entire shop floor, with a particular emphasis on areas that might be out of sight from the till. You could also position CCTV so that it is always monitoring any locked display cabinets, with signs notifying customers that they are being recorded.

Security Tags

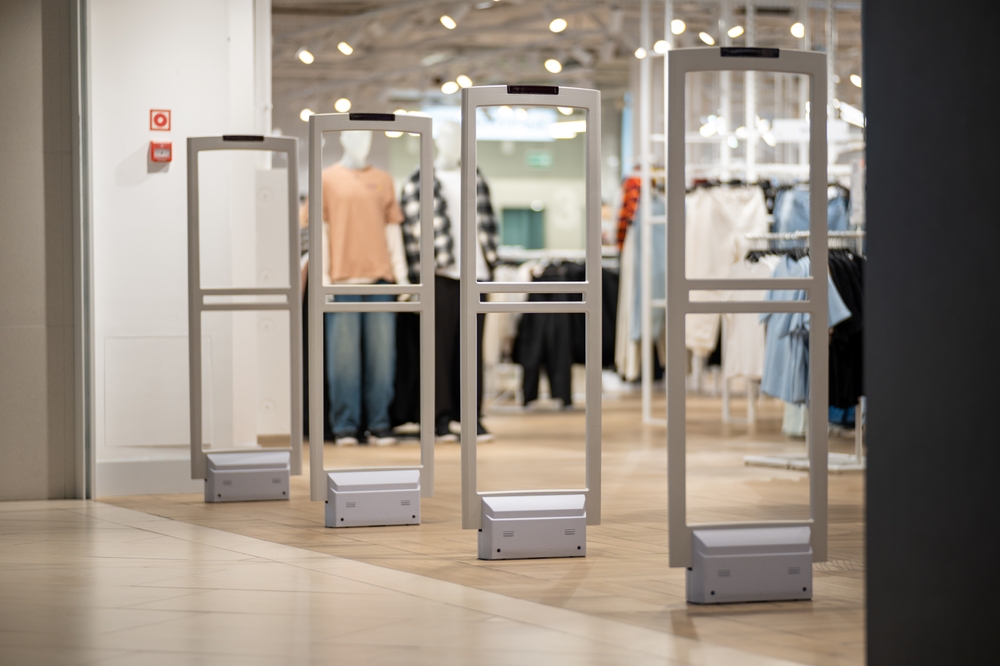
Attach security tags to your high value, high-theft items, which members of staff would have to remove at purchase.

These can act as a strong deterrent, as even if they do not prevent thieves from lifting the products from your shelves, they may not be able to remove the security tags without damaging the product. This would make the product harder for them to sell.

Staffing

Train your staff to understand the common shoplifting techniques, so they know what sort of behaviours to look out for, and what sort of items thieves are most likely to target. Good customer service can also help prevent many thefts. If your staff make a point of greeting every customer as they enter, then any potential thieves will know that their presence has been noted, which may make it harder for them to act.

You should also consider your staffing levels and your staff rotas. If possible, you should aim to limit the times when there is just one single member of staff on the shop floor. This is because shoplifters often work in groups. One person will distract a member of staff while the other attempts to lift a high value item, unobserved.

Get The Right Cover For Your Retail Store

Shoplifting affects retail businesses in a number of ways. Beyond the financial losses, you also have to consider the costs of installing new security systems, the damages to staff morale, and an overall less pleasant retail experience for everyone. If your customers have to contend with security tags, locked cabinets, and extensive CCTV coverage, they may start to feel like you do not trust them.

But no matter how much your security systems cost, they may help you save money in the long-term through reducing your losses due to theft. Plus, if you can evidence your anti-theft measures to your insurers, it may help you to make a saving on the cost of cover.

While insurance cannot itself prevent shoplifting, a specialist retail insurance policy can cover your store for many of the losses you may experience as a result of theft and other incidents.

James Hallam is an independent Lloyd’s broker with a dedicated team of insurance professionals who care about protecting your store.

Find out how we can help your shop today.

Do Shop Owners Need Cyber Cover for POS and Card Payments?

Do Shop Owners Need Cyber Cover for POS and Card Payments? 1000 668 James Hallam

Cyber insurance has become essential for all businesses, and this includes brick and mortar shops. Even if you do not sell any products online, your point of sale (POS) and card payment systems may still leave you vulnerable to attack.

How Can Hackers Target POS and Card Payments?

Cybercriminals know how to target your POS and card payment systems. Some cyberattacks are carried out in person and on your premises. A cybercriminal might use a USB or a similar device to install malware on an unattended terminal, or they may use your guest Wi-Fi to access your POS devices. But cybercriminals can also hack these systems remotely.

What Are The Risks of POS and Card Payment Breaches?

Once cybercriminals gain access to your POS and card payment systems, they can harm your shop and your customers in a number of ways:

  • Cybercriminals might gain access to the data of any cardholder who uses a compromised machine. They could lead to identity theft and other forms of fraud, and it could even result in chargebacks for certain purchases. You may even face some legal action yourself as part of a wider fraud investigation.
  • Cybercriminals may gain remote access to your systems, where they may steal your personal data or your customers’ personal data, or else cause some prolonged system downtime that could seriously compromise your operations.
  • Cybercriminals may install malware that will encrypt your POS systems as part of a ransomware attack. You will not be able to process any payments until you meet their demands. If you fail to meet their demands, they may choose to steal your data outright, or they may simply delete it, which will lead to further downtime. All the while, you will miss out on revenue, and your reputation with your customers and suppliers may suffer.

What Does Cyber Insurance For Shops Cover?

Cyber insurance may not prevent POS and card system cyberattacks from occurring. But if you are the victim of a cyberattack, your cyber insurance policy can provide invaluable cover for your liabilities and recovery:

  • Investigation – You will be covered for the costs of the IT forensics investigation, in which insurers will work to determine the cause of the breach, and identify the scope of the damage.
  • Response – Your policy will cover certain crisis management procedures, such as notifying and supporting any customers who may have been affected by the breach. If necessary, your policy may also cover your PR, which could help you retain your reputation following an attack.
  • Business Interruption – If your POS and card payment systems are compromised or offline, then your revenue will inevitably suffer. Your cyber policy can include business interruption insurance, which can cover any lost revenue while your systems recover.
  • Other expenses – Your cyber insurance policy can cover any other expenses you might encounter during your response and recovery, which might include chargeback and card replacement costs, and the costs of replacing or restoring your terminals and other equipment.
  • Legal Expenses – Finally, your cyber insurance can cover any legal fees that may arise if you are involved in any fraud investigations as a result of the breach.

What is Not Covered By Cyber Insurance For Shops?

While cyber insurance can provide invaluable cover should you find yourself a victim of a cyber attack, there are some circumstances where you might not be covered.

Prior Known Circumstances
You may not be covered from losses arising from problems arising from “prior known circumstances” – for cyber breaches that occurred even though you were aware of a certain vulnerability.

For example, if you notice a customer behaving suspiciously in your store, and you suspect that one of your terminals may have been compromised, then you may not be covered for any subsequent incidents should you fail to act on your suspicions.

Poor Security System Maintenance
Similarly, when you take out your policy, your insurer may ask you to specify any cybersecurity systems and procedures you currently have in place. If you make a claim on your policy, and your insurer finds that you failed to maintain these systems, then they may turn down your claim.

Cover Exclusions
Some cyber insurance policies may list a number of additional exclusions. You may not be covered for incidents arising from “acts of foreign enemies”, for instance, or for data loss that occurs as a result of a wider issue with your provider.

For more information about exclusions to your cyber insurance cover, be sure to read your policy wording.

How To Protect Your Shop From Cyber Attacks

Cybersecurity is a complex issue, and cybercriminals are getting smarter all the time. But here are some essential tips that could help you keep your shop and your customers safe:

  • Updates
    Keep all of your systems updated. Cybercriminals are constantly looking for vulnerabilities to exploit, and security updates are vital for closing these loopholes.
  • Wi-Fi access
    Think twice about offering guest Wi-Fi. Set strong password protection, and never share your login credentials with anyone.
  • Training
    Train your staff to understand the risks of cyberattacks, and the sort of warning signs they should look out for.
  • Physical awareness
    Remember that some retail cyberattacks occur in person. Do not leave any terminals or other devices unattended at any time, as cybercriminals may be able to compromise your systems while your back is turned.

Get Specialist Cyber Insurance For Shops From James Hallam

James Hallam is an independent Lloyd’s broker with a dedicated team of insurance professionals who care about protecting your shop. We can help you access specialist retail insurance for your store, which can include cyber insurance.

Find out how we can help you today.


Welcome to James Hallam: Supporting Anthony Jones Business and Personal Insurance Customers

Welcome to James Hallam: Supporting Anthony Jones Business and Personal Insurance Customers 500 334 James Hallam

When your insurance arrangements move to a new broker, it’s understandable to have questions. Will your service change? Who do you contact? Will you still receive the same expert advice?

If you’re an Anthony Jones business or personal insurance customer, you can be reassured that you’re moving to a broker with a long-standing reputation for delivering specialist insurance advice and outstanding customer service.

James Hallam is proud to be the official nominated insurance broker for Anthony Jones customers, providing continuity, expertise and access to an even broader range of insurance solutions.

A broker you can trust

Insurance isn’t just about policies. It’s about having experienced people who understand your circumstances and are there to help when you need them most.

As one of the UK’s leading independent insurance brokers, James Hallam has been arranging insurance for businesses and private clients for more than four decades. We work with a wide panel of leading insurers, enabling us to recommend cover that’s tailored to each client’s individual needs rather than a standard, one-size-fits-all solution.

Whether you’re protecting your family home, your car, your business premises or your professional liabilities, our advisers take the time to understand what’s important to you.

Looking after both personal and business insurance

One of the advantages of working with James Hallam is the breadth of expertise available under one roof.

For personal customers, we can arrange insurance for homes, vehicles, travel, valuable possessions and many other everyday risks.

For business owners, we support organisations across a wide variety of industries, arranging cover for property, liability, professional risks, cyber threats, fleets and much more.

Many of our clients appreciate having a single trusted broker who can look after both their business and personal insurance requirements, making it easier to review cover, identify potential gaps and ensure their insurance evolves alongside changing circumstances.

Making the transition straightforward

We understand that changing brokers can seem daunting, but our priority is making the process as seamless as possible.

Our experienced advisers are available to answer questions, explain your options and support you throughout your renewal and beyond.

You’ll continue to receive personal service from knowledgeable insurance professionals who are committed to helping you make informed decisions about your insurance.

Insurance advice that grows with you

Insurance requirements rarely stay the same for long.

Businesses expand, employ more people, purchase new equipment or enter new markets. Families move home, buy new vehicles or acquire valuable possessions.

Regular reviews help ensure your insurance continues to reflect your current circumstances, providing appropriate protection without unnecessary complexity.

As an independent broker, James Hallam can work with you over the long term, adapting your insurance programme as your needs change.

Welcome to James Hallam

We’re delighted to welcome Anthony Jones customers to James Hallam.

Our focus is simple: providing expert advice, excellent service and tailored insurance solutions that give you confidence in the protection you have in place.

Whether you’re renewing an existing policy, reviewing your insurance portfolio or looking for advice on future cover, our team is here to help.

We look forward to building a long-term relationship and helping you protect what matters most, both in business and in your personal life.

If you have any questions or would like to speak to a member of the dedicated Anthony Jones team, please don’t hesitate to get in touch.

What is Contractors’ All Risk Insurance and Who Needs It?

What is Contractors’ All Risk Insurance and Who Needs It? 1000 666 James Hallam

If you are a building contractor, contractors’ all risk insurance can cover almost every aspect of an ongoing construction or development project, including the equipment and materials you are using, and any people involved in the project.

What is Contractors’ All Risk Insurance?

Contractors’ all risk insurance is specialist insurance cover for building contractors. As the name suggests, it is designed to cover all of the risks you might face throughout a building and development project.

Core areas of cover include:

  • Insurance for contract works on construction sites, including cover for demolition and excavation projects.
  • Plant and equipment insurance.
  • Business interruption insurance, to cover project overheads in the event of delays.
  • Insurance for any temporary buildings you use throughout the project.
  • Liability and personal injury insurance for any individuals involved in the project, including workers and other members of the public who might spend time on or near the construction site.

Once the project is complete, contractors’ all risk insurance can also provide some cover for your completed buildings while they are unoccupied and awaiting tenants.

Contractors’ all risk insurance should not be confused with contract works insurance. For more information, read our guide to the difference between contractors’ all risk insurance and contract works insurance.

Who Needs Contractors’ All Risk Insurance?

Contractors’ all risk insurance can provide essential comprehensive cover for many parties concerned with construction projects, including:

  • Building contractors and construction firms.
  • Subcontractors, such as those who provide specialist services during a building project, including electricians, plumbers, and roofers.
  • Property developers, should a renovation require extensive construction work.
  • Property owners arranging for construction of renovation work.
  • Civil engineering contractors.

In most cases, the main building contractor will take out a contractors’ all risk insurance policy to cover the project, and they may take out a joint policy with a second party, such as a property owner.

Each of the parties we have listed above should ensure they are covered by the main contractor’s all risk insurance policy. If not, then they may have to get a policy of their own to cover their own materials, equipment, employees, and liabilities.

Is Contractors’ All Risk Insurance a Legal Requirement

Though contractors’ all risk insurance is not always a legal requirement in the UK, many large scale construction or renovation projects will require such cover to be in place. The contract may also specify who is required to arrange for the cover, whether this is the main contractor, or the employer.

Why You Need Contractors’ All Risk Insurance

Yet even without a legal obligation, and even if there are no contractual obligations, you should still view contractors’ all risk insurance as an absolute necessity, particularly when it comes to certain kinds of construction or renovation projects:

  • Large projects involving extensive complex works, in which the costs of any potential damage or delays would be significant.
  • Development projects organised by the property owner, for which they would be liable for all financial risks.
  • Joint projects involving numerous contractors, subcontractors, and other parties.

In any of these situations, a single incident could lead to significant costs which could jeopardise not just the project, but also your business. Contractors’ all risk insurance would cover these costs, providing essential protection for the project itself, and for all parties involved.

Get The Specialist Construction Insurance You Need With James Hallam

James Hallam is an independent Lloyd’s broker with a specialist team of experienced insurance professionals who are committed to protecting construction business.

We will take the time to understand your construction project so that we can advise on the specific risks you are facing. We can then help you access a specialist contractors’ all risk insurance package that meets all of your needs at a competitive price.

Find out how we can help you today.