SME

Health and Safety Induction Checklist for New Employees

Health and Safety Induction Checklist for New Employees 1000 667 James Hallam

As part of their onboarding and induction process, all new employees should receive a thorough introduction to your company’s health and safety policies and procedures.

In this post we will outline what you should include in your health and safety induction for new employees, so you can cover all bases and stay compliant with the relevant health and safety legislation.

Why Health and Safety Inductions Matter

The Health and Safety Executive (HSE) makes it clear that employers have a legal responsibility to ensure that the workplace is safe and healthy for everyone.

One of your responsibilities under the Management of Health and Safety at Work Regulations 1999 is to take action to eliminate workplace hazards, or to control the risks.

Health and safety inductions are an essential component of this risk management process. Through introducing new employees to your various health and safety policies and procedures, you can equip them with the knowledge and skills they need to keep themselves and others safe.

You can also ensure that, in the event of an emergency, everyone knows what to do, where to go, and to whom they should report.

What to Include in Your Health and Safety Induction Checklist for New Employees

These are the key elements that all workplaces should include in their health and safety induction checklists:

  1. An introduction to the job, including instructions on how to carry out the role safely, and details of all necessary training requirements, welfare provisions, and emergency contacts.
  2. Emergency arrangements, including the fire evacuation procedure, accident and incident reporting procedures, and details of the first aid provisions.
  3. Manual handling procedures, including assessments (is the object too heavy to lift?) and the use of lifting aids.
  4. Hazard awareness: What sort of risks should the employee look out for, and how should they report any risks they spot?
  5. Housekeeping: What role can the employee play in helping to keep the working environment safe, clean, and free of clutter?

Industry Specific Requirements for New Employee Inductions

Beyond the key elements, you may have to introduce additional elements to your health and safety induction checklist depending on the specific risks in your workplace:

  1. Equipment, tools, and machinery: Safe use, training requirements, and awareness of health and safety risks.
  2. Personal Protective Equipment (PPE) policies, including the correct use and storage, and the procedure for reporting faults.
  3. Hazardous substance policies: Including risk assessments, and instructions on safe storage, handling, and disposal. Depending on the industry you work in, you may also require your new employees to receive certain vaccines before they can work with the hazardous materials you manage.

Health and Safety Induction Checklist Template

You can download a free health and safety induction checklist template from the Government’s website.

This particular checklist includes a box to tick to confirm that you have booked the new employee’s mandatory health, safety, and wellbeing awareness training. It also includes some useful guidance notes to explain various aspects of the checklist items.

You can also read our guide to writing a health and safety checklist for the office, and our guide to writing a health and safety checklist for warehouses.

Health and Safety Should be an Ongoing Priority

Running through a health and safety induction checklist will literally be a box-ticking exercise for both the employer and the employee. But this does not mean that you should treat it as a mindless “one-and-done” task.

You have an ongoing duty of care to all of your employees, and health and safety awareness and training should not stop at induction:

  • Make your health and safety policy easily accessible to all employees. This means writing it in clear language, and storing it in a place where any employee can reference it at any time, such as on the company intranet.
  • Provide routine refresher training, so that employees never lose sight of the essentials. Ongoing health and safety training can also help you to protect your employees and your business against new and evolving threats, such as the growing risk of cybercrime.
  • Place signage around the workplace to highlight key risks (such as steps, edges, and loading areas), and to remind employees of their responsibilities.
  • Thoroughly investigate any incidents to help you identify measures that could help prevent future risks.

Get The Right Cover For Your Business

If your business employs staff, Employers Liability Insurance is typically a legal requirement. This can provide protection for your  employees against  injury or illness claims that might take place in the workplace. Beyond this, you may want to consider insurance protection  for third party liabilities, property damage, business interruption  theft, and cybercrime depending on your circumstances.

James Hallam is an independent Lloyd’s broker with a dedicated team of insurance professionals who care about protecting your business. We can help you access  insurance cover designed against a range of workplace risks you may face.
Learn more about our specialist SME insurance services.

What is Tramping and Trunking in HGVs?

What is Tramping and Trunking in HGVs? 1000 667 James Hallam

In the haulage industry, the terms “tramping” and “trunking” refer to two different strategies for managing routes and contracts. In this post we will outline the key differences between tramping and trunking, along with the possible risks and rewards of each.

What is Tramping?

Tramping refers to the practice of transporting goods over long distances and long periods of time.

The long distances involved in tramping means that drivers are required to spend extended periods on the road away from home. A journey to the destination and back could take a number of days, during which time the driver may effectively live in their cab. They will drive for a limited number of hours before sleeping in their cab at the end of the day.

Benefits of Tramping

  • Long distance haulage contracts may be highly lucrative for haulage firms.
  • Tramping jobs tend to pay better than other driving roles.
  • The work can be more varied. The driver may be required to physically move the cargo at pick-up or drop-off, for example.

Downsides of Tramping

  • Tramping contracts typically involve larger quantities of goods, so they will also involve larger and heavier trucks. These can be more expensive to acquire, run, and insure.
  • Not all drivers enjoy being away from home for long periods, and some may struggle to manage their tachograph while spending days on the road.
  • European tramping contracts may require drivers to acquire certain travelling documents, while also familiarising themselves with overseas driving laws and customs.
  • Tramping may also require driving to remote locations on unfamiliar rural roads, which may make accidents more likely.

What is Trunking?

Trunking involves shorter distances and regular routes. Indeed, a driver may take the same route every day, and they will usually be able to return home once the delivery, or their shift, is complete.

Night trunking is also common, and some drivers may prefer this, as it would mean travelling on less busy roads, with less chance of traffic jams and other delays.

Benefits of Trunking

  • As drivers can return home at the end of each shift, trunking arrangements can lead to a much better work/life balance than tramping arrangements.
  • As drivers will stick to familiar roads, including motorways and dual carriageways, there may be less risk of accidents.
  • Haulage firms will likely find a trunking fleet much easier to manage than a tramping fleet, as all the vehicles and drivers will usually stay within a relatively small area.

Downsides of Trunking

  • In order to avoid traffic and meet strict delivery times, trunking contracts often rely on night shifts. Not all drivers appreciate unsociable hours, and driving at night could make driver fatigue more likely.
  • Trunking contracts may be more reliable and easier to manage, but they will probably not pay as much as long-distance or overseas tramping contracts.

Tramping vs. Trunking – Key Considerations For Fleet Managers

  • Compliance – Drivers are restricted to a set number of driving hours each day, all of which they must meticulously record on their tachographs. This can be relatively easy to manage and enforce with trunking arrangements, as fleet managers can set shifts in line with driving hours. But it will be up to the driver to manage their hours and their tachograph throughout a long distance tramping arrangement.
  • Fleet Management – Managing your fleet can be relatively straightforward when all of your vehicles and drivers stick to familiar routes that are no more than a day’s driving distance from your depot. But it can be more challenging to keep tabs on your fleet when your drivers spend days away from home, especially when they travel overseas.
  • Driver Welfare – Both tramping and trunking can place huge demands on drivers, particularly if the contract involves night driving. Beyond simple compliance, you will have to establish a means of helping drivers maximise their work/life balance while understanding and fighting the risks of driver fatigue.
  • Insurance – Tramping arrangements will generally require more extensive insurance coverage, to account for the long periods spent on unfamiliar roads, the potential for arranging for repairs and recovery overseas, and the involvement of heavier and more powerful trucks and trailers.

Tramping or Trunking, We Have You Covered

James Hallam is an independent Lloyd’s broker with a dedicated team of insurance professionals who care about protecting you and your fleet.

Whether you go for tramping or trunking contracts, we can help you ensure you have access to  cover that meets your needs  to protect your drivers, your vehicles, and your operations against potential risks your fleet faces.

Learn more about our HGV insurance services.

What is Insurance Premium Tax?

What is Insurance Premium Tax? 1000 643 James Hallam

Insurance premium tax (IPT) is a tax the UK Government applies to certain insurance products.

In this post we will explain how IPT works, including the types of insurance policies to which it applies.

What is Insurance Premium Tax?

The UK Government applies IPT to general insurance premiums. Rather than seeing IPT as a separate payment, it is built directly into the premiums you pay for certain forms of cover. Your insurer collects the tax in this way before passing it on to HMRC.

Insurance Premium Tax vs. VAT

Perhaps the best way to think of IPT is as a form of VAT that specifically applies to certain insurance products. When you buy applicable products or services, you will automatically pay the VAT as part of the overall cost. Similarly, when you pay your insurance premium, some of the payment will cover your insurance costs, while the rest will go to the UK Government as tax.

But while both VAT and IPT are indirect taxes collected by HMRC, there are some key differences between the two:

  1. Insurance products are actually exempt from VAT. The Government first introduced IPT in order to collect taxes on transactions to which VAT did not apply.
  2. The current VAT rate is 20%, which HMRC applies to most goods and services. But there are two IPT rates – a standard rate, and a higher rate.
  3. While businesses can reclaim VAT on their tax returns, they generally cannot reclaim IPT.

Insurance Premium Tax Rates

HMRC applies two different IPT rates. At the time of writing, they are:

  • Standard Rate – 12%
  • Higher Rate – 20%

The standard rate applies to some of the most common insurance products, such as home insurance, pet insurance, and car insurance.

Meanwhile, the higher rate generally applies to insurance products that are sold alongside other products or services – such as when airlines sell travel insurance alongside a flight, or when an electronics manufacturer allows customers to purchase cover for their appliances.

You can read a full breakdown of the current IPT rates.

Insurance Premium Tax Exemptions

Certain insurance products are exempt from IPT, including:

  • Cover for commercial aircraft and marine vessels.
  • Cover for commercial goods during international transit.
  • Most long-term insurance products, including life insurance and permanent health insurance policies.
  • Reinsurance (i.e. cover that insurance firms take out to cover risks relating to the policies they underwrite).
  • Cover for overseas risks – though these policies may instead be liable for taxes imposed by other countries.

You can read a full guide to IPT exemptions.

Who Pays Insurance Premium Tax?

Insurers apply IPT directly to their premiums, which means that they effectively collect the tax payments from their customers on behalf of HMRC. IPT is always paid directly by the policyholder, whether this is an individual or a business.

Can You Claim Back Insurance Premium Tax?

While businesses can claim back VAT, they generally cannot claim back IPT.

Even if your business is VAT-registered, you cannot list IPT as input tax on your VAT return. It is instead treated as an entirely separate tax.

As we mentioned above, certain insurance products are exempt from IPT, and you may be able to reclaim payments if you believe you were charged incorrectly. But this is a matter you will have to settle directly with your insurer. You will not be able to reclaim the payments from HMRC.

How Does Insurance Premium Tax Affect the Cost of Insurance?

The current IPT rates have been in place since 2017, and the rates have risen six times since the tax was first introduced in 1994. If the rate changes at all in the coming years, it will most likely be in the form of a further increase.

IPT means higher insurance premiums for policyholders. Depending on the type of insurance, you will either have to pay 12% or 20%, which will be applied directly to your premiums. This means there is simply no way to avoid it and, as we have seen, businesses cannot reclaim IPT either.

But if you do want to make savings on the cost of your business insurance, a good place to start is through working with an insurance broker. An experienced broker can advise you on key risk management procedures, and show you how to evidence these measures to your insurer in order to potentially save on premiums. Your broker can also help you access a tailored insurance package that will provide insurance solutions for the risks you  face.

Get The Right Cover For Your Business

James Hallam is an independent Lloyd’s broker with a dedicated team of insurance professionals who care about protecting your business. As well as offering cost-effective risk management advice, we can also help you source the  cover you need for your business.

Learn more about our specialist SME insurance services.


What Insurance Do Driving Instructors Need?

What Insurance Do Driving Instructors Need? 1000 668 James Hallam

Teaching people to drive is an inherently risky business. Beyond L-plates and a dual control car, you will need extensive insurance cover to protect you, your learner, your vehicle, and other road users.

If you work for a driving school, then your employer will likely sort out the necessary insurance on your behalf. But if you are a self-employed driving instructor, then you will be wholly responsible for arranging your own cover.

In this post we will outline the key insurance requirements for driving instructors, including the cover you need by law.

Can Driving Instructors Use Standard Car Insurance Policies?

An ordinary car insurance policy will not provide this cover, not even if you add “business use” to the policy. Only a dedicated driving tuition motor insurance policy will give you the specialist cover you need.

Legal Requirements For Driving Instructor Insurance

You have a legal requirement to get driving tuition motor insurance. This will cover you for the specific risks associated with driving a dual control car, and with providing paid tuition services.

Also, if you hire any employees, such as someone to provide admin support, then you have a legal duty to get employer’s liability insurance. This can provide protection against injury or illness claims that may take place in the workplace. You need to get this cover even if you hire one of your relatives, and even if they only work for you for a few hours a week.

Strongly Recommended Insurance Extras For Driving Instructors

Additional cover options unlikely to be covered as standard within your driving instructor’s insurance could include:

  • Public Liability Cover – This can be a coverage gap for driving instructors. Driving tuition motor insurance can cover your liabilities during your driving lessons. Public liability cover, on the other hand, can cover accidents, injuries, and damages to personal property that occur outside of your driving lessons.
  • Professional Indemnity Cover – If you deliver training to fleets, or if you are responsible for training other driving instructors, then professional indemnity insurance can cover legal fees and compensation payments following claims of professional negligence.
  • Contents Cover – This can cover the loss, damage, or theft of your belongings that you take outside your home, such as your smartphone, your laptop, and any other equipment you use to run your business.
  • Personal Accident Cover – If you are unable to provide driving lessons, then your income will stop immediately. Personal accident insurance can provide a lump sum in the event of an injury, such as loss of sight, limbs or permanent total disablement. It can also provide a weekly benefit for temporary disablement that prevents you from carrying out your work. (Personal Accident Cover is different to Accident, Sickness and Unemployment Cover, which provides a monthly benefit to cover your overheads.)

All covers included within the policy and optional extras are subject to policy terms and conditions, limits and endorsements.

Common Pitfalls with Driving Instructor Insurance

Above we mentioned that public liability can be a cover gap for driving instructors. But it is also a mistake to assume that your public liability insurance will cover you for anything that occurs outside of your driving lessons.

The same is true for the other additional extra covers, such as Professional Indemnity Insurance, Contents and Personal Accident. Your insurance policy will likely list a number of exclusions to the cover. Take the time to read your policy wording, along with the exclusions, so as to fully understand exactly what you are and are not covered for.

Also be aware that your work as a driving instructor may compromise certain other insurance policies you hold. For example, you may have to inform your home insurance provider if you are running your driving instructor business from home, and you may need to add business use to your car insurance policy in addition to getting a dedicated driving tuition motor insurance policy.

How Much is Insurance For Driving Instructors?

The amount you pay for your policy will depend on a number of factors:

  • The type of car you drive – Advanced and high performance models will cost more to insure, due to the increased risk of theft, and the potential high cost of repairs following an accident.
  • The type of training you provide – If you train fleet drivers or other driving instructors, then you will likely have to pay more for insurance owing to the need for professional indemnity cover.
  • The level of cover you choose – You may be able to specify the level of public liability or personal accident cover you receive, for example. The higher your cover limit, the more you should expect to pay.

How James Hallam Can Help You Get The Cover You Need as a Driving Instructor

James Hallam is an independent Lloyd’s broker with a dedicated team of insurance professionals who care about protecting you and your business.

We can advise you on the risks you may face as a driving instructor, and we can help you access a tailored policy that meets your cover needs. We can also help you ensure that your work as a driving instructor does not compromise any other insurance policies you hold.

Learn more about our specialist insurance services.

What is Deterioration of Stock Insurance?

What is Deterioration of Stock Insurance? 1000 568 James Hallam

Deterioration of stock insurance can provide essential cover for any business that sells or stores perishable goods.

In this post we will explain what deterioration of stock insurance is and what it covers, along with some common exceptions and limitations to the cover.

What is Deterioration of Stock Insurance?

If an unexpected event causes your perishable stock to spoil or degrade, then deterioration of stock insurance can cover your losses. Specifically, this cover can provide some financial compensation should deterioration make your stock unsuitable for sale.

Business insurance policies generally will not offer cover for stock deterioration as standard. To get the protection you need, you will either need to get a specialist policy, or you will need to add the cover to an existing policy.

Some insurers may specify that you introduce certain measures in order to safeguard your stock, as a condition of cover. This might include installing a failsafe, such as a backup power system, while staying on top of equipment cleaning, servicing, and maintenance schedules.

What Does Deterioration of Stock Insurance Cover?

Deterioration of stock insurance covers loss or damage of perishable goods that need to be stored at certain temperatures.

For example:

  • A power failure causing a fridge or a freezer to fail.
  • Water damage from leaks or flooding.
  • Transport issues – for example, a truck transporting temperature-controlled goods is involved in an accident, resulting in equipment failure.
  • Damage from insufficient heating, cooling, or unwanted temperature fluctuations.

Are There Any Exclusions and Limitations to Deterioration of Stock Insurance?

Most deterioration of stock insurance policies will list a number of exclusions and limitations. These might include:

  • Poor Maintenance and Neglect – If a fridge, freezer, or other equipment fails as a result of poor maintenance, your insurer may reject your claim. Stay on top of servicing and cleaning schedules to ensure you get the cover you need.
  • Foreseeable Events – Similarly, your insurer will likely reject your claim if your stock deteriorates as a result of an incident you could have foreseen and prevented. For instance, you might have to take special measures to protect your stock in the event of a heatwave. If you were aware that high temperatures were forecast, but you did not work to secure your stock, then you may not be covered for any loss.
  • Natural Deterioration – Deterioration of stock insurance is designed to cover sudden and unexpected events. It will not cover losses due to slow or gradual decline.
  • Pre-Existing Problems – If your stock was already faulty before you put it into storage, then your insurance probably will not cover you for any unexpected events leading to total loss.
  • Security Issues – If your equipment fails as a result of a break in, your insurer may reject your claim if they find that you did not take adequate steps to secure your premises. Most policies also include standard exclusions for losses due to war, terrorism, riots, and civil unrest.

Who Needs Deterioration of Stock Insurance?

Any business that stores, transports, or sells perishable goods could benefit from deterioration of stock insurance. This might include:

  • Cafes, restaurants, bakeries, butchers, delis, takeaway shops, and any other business that prepares and sells food on the premises.
  • Greengrocers, corner shops, newsagents, off-licenses, wine merchants, and supermarkets.
  • Pharmacies, along with any business that stores or sells cosmetic and beauty products.
  • Florists and other horticultural businesses.
  • Warehouses that specialise in storing any kind of perishable good.

Get The Cover You Need for Your Stock

James Hallam is an independent Lloyd’s broker with access to a hand-picked selection of A-rated insurance providers.

We can help you get the specialist stock deterioration insurance you need to protect your business against unexpected events. We can also advise you on essential risk management procedures that could make stock deterioration less likely, and we can show you how to evidence these measures to your insurer in order to potentially reduce the cost of cover.

Get in touch for a free quote today.

How To Identify Risks in Your Business

How To Identify Risks in Your Business 1000 667 James Hallam

There is more to risk management than identifying possible sources of accidents and injuries. It is also important to identify risks that could lead to inefficiencies, disrupt your operations, increase your overheads, and affect your cashflow.

In this post we will explore how to identify risks in your business, and establish the process for managing, mitigating, or eliminating these risks.

Common Risks for Every Business

When assessing the sources of risk in your business, you should consider:

  • Property Risks – Including damage from fire, flood, subsidence, and other incidents, along with losses from theft, vandalism, and other crimes.
  • Finance Risks – Including cash flow fluctuations, debt management, and economic uncertainty.
  • Operations Risks – Including bottlenecks and inefficiencies that could lead to risks, possible hazards posed by outdated or faulty tech, and poor quality control measures.
  • Cyber Risks – Including financial and reputational damages from cybercrime, and liability costs from data leaks and data loss.
  • Legal Risks – Such as claims involving intellectual property theft, dishonesty, negligence, and fraud.
  • Supply Chain Risks – Including dependencies, issues with transportation, and potential disruption.
  • Stock Risks – Such as losses from theft or spoilage. You will have to consider additional risks if you routinely store or work with hazardous materials.
  • Staff Risks – Including issues with compliance, training, skill gaps, and turnover.

How Create Your Risk Management Process

For every risk that you identify for your business, you should also identify the following:

  • Who is at risk? Who might be affected by a particular risk, and how might it affect them? Consider whether each risk will affect staff, customers, contractors, delivery drivers, visitors, or a combination of the above. Also bear in mind that some people may experience risks differently. Someone with vision or hearing problems, for example, may find it harder to follow evacuation procedures.
  • How likely is the risk? Plus, how severe would the outcome be? This could range from financial or reputational damages to serious injuries and death. After you have quantified your risks in this way, you can prioritise them based on their probability and severity. This will allow you to allocate your risk management resources effectively.
  • How are you going to manage, mitigate, or eliminate the risk? The specific steps you take will of course depend on the risk in question. Though for every action you identify, you should also establish who is responsible for carrying it out, along with a timeframe for completing it, and a process for reviewing the risk assessment.

Managing Your Business Risks

Read our essential guide to risk management for businesses. We also have a number of specialist guides for certain kinds of businesses. Some of these offer general risk management advice, but others focus on specific risks, such as fire, theft, or cybercrime.

General Risk Management Guides

Cyber Risk Management Guides

Fire Risk Management Guides

Get Tailored Insurance For Your Business

James Hallam is an independent Lloyd’s broker with access to a hand-picked selection of insurance providers.

We can help you understand the risks your business is facing, and we can advise you on how to effectively manage these risks. We can then help you access the business insurance you need, and we can show you how to evidence your risk management processes in order to make savings on the cost of cover.

Get in touch for a free quote today.

Why is Retail Theft Rising in 2026?

Why is Retail Theft Rising in 2026? 1000 666 James Hallam

Shops across the UK are reporting a rise in retail theft. According to figures from the Office for National Statistics (ONS), over 500,000 incidents were reported in 2025 – 2026, a rise in 5% compared to the previous year.

In this post we will outline some of the underlying causes of this rise in retail theft, before exploring some ways you can help to prevent theft in your store.

Underlying Causes of Retail Theft Rising

There are a number of factors which affect crime rates, particularly theft. In 2026, we are seeing the following contributory factors:

  • Cost of living crisis
  • Organised crime
  • Staffing issues
  • Rise in self-checkouts

We’ll explore each of these individually below to find out more about the causes and how it may impact target items.

The Ongoing Cost of Living Crisis

The UK has been struggling with high inflation rates for a number of years, which greatly increased the cost of living for millions.

Rising food costs may have contributed to the increase in shoplifting. Baby formula is one of the most commonly stolen items in the UK, and this is likely because it is both essential and expensive.

Organised Crime

Some retail bodies claim that organised crime is driving a rise in retail theft.

Some of this may be relatively small scale, such as the thieves who steal premium cuts of meat to sell to pubs and other establishments. But some retailers have fallen victim to larger gangs that have targeted multiple stores in succession.

Even worse, this form of theft seems to be linked with rising incidents of violence and abuse against frontline retail staff.

Staffing Issues

Rising costs have forced many stores to cut staff hours, and the UK workforce as a whole has shrunk in recent years.

Fewer staff on the shop floor means that there are fewer people to look out for the signs of shoplifting, and more blind spots for thieves to operate in.

The Rise of Self-Checkouts

Many stores have started offering self-checkout services, partially as a way of managing costs, and partially as a way of offering a more streamlined experience to customers.

Some self-checkout areas feature systems designed to prevent theft, such as security cameras, and gates that will only open if the customer scans a code they receive after purchase. But nonetheless, the perceived lack of security around self-checkout areas may be fueling a rise in shoplifting.

Some customers find self-checkout systems confusing, which may mean they unintentionally take some items without paying. And while they may not be shoplifting in the strictest sense, this will still lead to losses for the store.

The Impact of Retail Theft on Stores

How To Reduce Theft in Your Store

We have a number of guides on our site to help you address retail theft in your store:

It is also important to address the risks of employee theft in your store. Read our full guide to understanding and preventing employee retail theft.

Get The Right Cover For Your Retail Store

A specialist retail insurance policy can cover your store for many of the losses you may experience as a result of theft and other incidents, subject to policy terms, conditions and exclusions.

James Hallam is an independent Lloyd’s broker with an experienced team of insurance professionals who care about protecting your store.

Find out how we can help your shop today.

How to Prevent Slips, Trips, and Falls in Your Shop

How to Prevent Slips, Trips, and Falls in Your Shop 1000 667 James Hallam

Slips, trips, and falls are a major issue for retail businesses, and there are severe penalties for shops that do not take the time to address the risks.

In this post we will explore some of the possible underlying causes of slips, trips, and falls in the retail environment. We will also outline how you can address these risks in your store.

What Causes Slips, Trips, and Falls in Shops?

There are a number of different causes for slips, trips and falls in shops, including:

  • Clutter – Any stock or equipment left in walkways can create a trip hazard for both staff and customers.
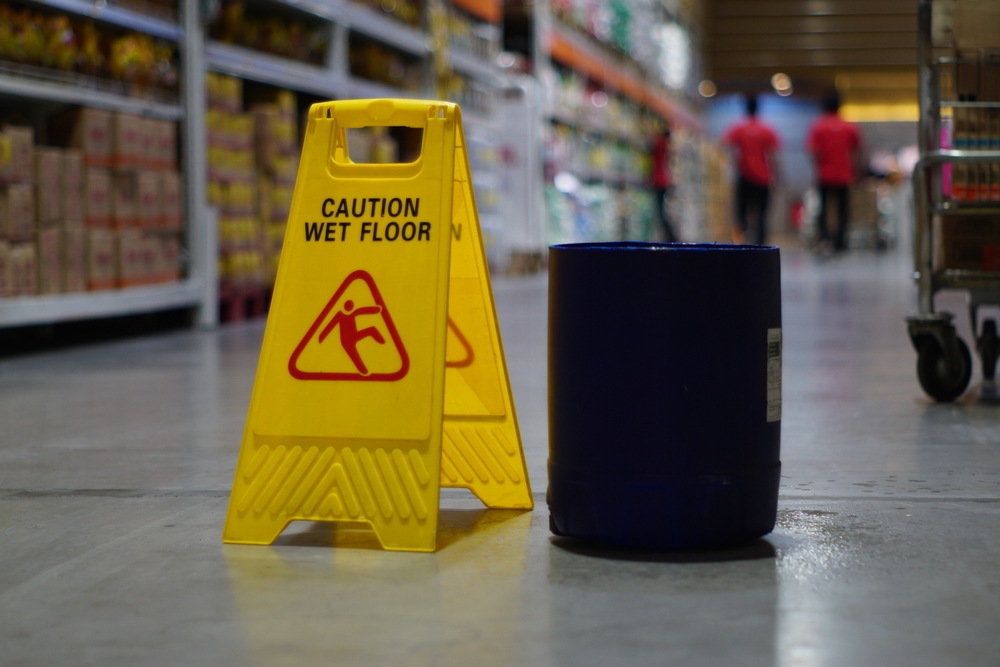
  • Liquids – A spilled liquid creates a slipping hazard. But customers may also slip on a freshly cleaned surface, particularly if there are no warning signs about, or if staff used too much cleaning product.
  • Mats, Rugs, and Tiles – People may trip over a rumpled mat or rug, or a loose tile on the floor.
  • Environmental factors – People may fail to spot slip or trip hazards if the lighting is poor. Or they may lose their footing if they do not see a step or a ramp.

How To Prevent Slips, Trips, and Falls in Your Shop

To help reduce and prevent slips, trips and falls in your shop, you should consider:

  • Staff Training – Train your staff to spot the risks that could contribute to slips, trips, and falls, and make sure that everyone knows what to do to address these risks. Also make a point of recording and reporting any incidents that occur, specifying exactly what went wrong, and outlining the steps you will take to prevent further incidents.
  • Stay On Top of Cleaning – Establish a cleaning rota and aim to clean up any spillages as soon as possible. It is also important to use the right cleaning products, and in the right quantity. Use the wrong product and you may not effectively remove a spillage. And use too much of a product and you could make the slipping hazard even worse.
  • Make Customers Aware of the Risks – After cleaning, place signs warning customers of slippery surfaces. If there are any steps or ramps on the shop floor, make sure they are clearly indicated, with signage if necessary.
  • Stay On Top of Maintenance – Replace faulty lighting, damaged floor tiles, and any other faults that could lead to accidents as soon as possible.
  • Reduce Clutter – Never leave stock or cleaning equipment unattended in walkways. This goes for your storeroom as well as your shop floor. Your staff are just as liable to get injured by a slip, trip, or fall as your customers.

Risk Management and Insurance

Addressing the common causes of slips, trips, and falls should form a part of your wider risk management strategy. Read our full guide to risk management for retail businesses.

As we mentioned above, there are severe penalties for any store that does not take the time to mitigate slipping and tripping hazards. The Health and Safety Executive has numerous case studies of slips and trips that ultimately cost retail stores dearly.

Specialist retail insurance can help cover any legal costs or settlements that may arise as a result of an incident in your shop. You have a legal duty to get employers liability insurance to cover the risks for your staff, while public liability insurance can cover any incidents that affect customers, contractors, delivery drivers, and other members of the public.

There are strong links between risk management and insurance. Your insurer may require you to implement certain risk management processes as a condition of your cover. But at the same time, if you can evidence your risk management efforts, you may be able to make a saving on the cost of cover.

Get The Right Cover For Your Retail Store

A specialist retail insurance policy can help provide cover for losses you may experience as a result of slips, trips, falls, and other incidents, subject to policy terms, conditions and exclusions.

James Hallam is an independent Lloyd’s broker with an experienced team of insurance professionals who care about protecting your store. We can help you access the cover you need for your business, and we can also show you how to evidence your risk management in order to make potential savings on your premiums.

Find out how we can help your shop today.


How To Value Vintage Clothing For Vintage Shops

How To Value Vintage Clothing For Vintage Shops 1000 667 James Hallam

If you run a vintage clothes shop, or a general second hand shop that sells vintage clothes among other goods, then you may have wondered just how much you should be charging for your vintage items.

In this post we will explore some ways you can value your vintage clothing, to help you set prices that reflect each item’s true value that your customers will be happy to pay.

What Affects the Value of Vintage Clothes?

Here are the some of the things that can impact the value of any item of vintage clothing:

  • Label – Some labels will always be worth more than others. Dior, Chanel, and other high-end designer labels will always attract high prices. But other labels might vary in value, depending on certain trends.
  • Condition – Items in good condition will be worth more than items that are soiled, worn, or damaged. However, some items have “provenance”. If an item is particularly rare, or if you can prove that it was once owned or worn by a famous person, then buyers might be more willing to overlook a bit of wear and tear.
  • Quality –Mass produced items made from cheap materials will be worth less than rare items made from high quality materials and with obvious care and craftsmanship.

How To Value Vintage Clothing

There are a few things you can try to help you determine the value of any item in your stock. Including:

  • Check online listings
  • Immerse yourself in vintage culture
  • Get a professional valuation

Some of these techniques might prove useful if you need to value large volumes of clothes as quickly as possible. Other techniques might be more costly and time-consuming, and so should be reserved only for items you suspect might be particularly valuable.

Be sure to test and adjust your prices. Be flexible, and be prepared to accept best offers rather than your asking price. Also be aware of how the seasons might affect an item’s value. People will likely pay more for a coat in the autumn or winter than they would during the height of summer.

We’ll go through each of the actions you can take in more detail below.

Check The Online Listings

Head to any site where people can buy and sell vintage clothing: Vinted, Depop, and eBay are good places to start.

If possible, look up the item’s label. But if the item does not have a label, try to find similar items based on its type, size, style, fit, pattern, and the approximate decade in which you think it might have been manufactured.

Pay more attention to final sale prices rather than listing prices. Ultimately, an item is only worth whatever people are willing to pay for it. You might see one item listed at, for example, £300, and another almost identical item that sold for around £50. If the listed item does not sell at the higher price, this suggests that the item’s true value is closer to £50 than £300.

Immerse Yourself in Vintage Clothing Culture

This is more of a long-term strategy that might help you develop your “eye” for spotting potentially valuable items, and your instinct for how much it might be worth.

Attend as many vintage events as you can and while you’re there:

  • Pay attention to what people are selling, and what people are buying.
  • Listen to the sort of questions buyers ask, and the sort of information sellers provide.
  • Talk to other sellers, either in person or online.
  • Share insights, and you can start to develop a joint understanding of current and emerging trends.

It can also help to pay attention to auctions. Shedd is a dedicated vintage auction marketplace in which every single item is initially listed at a low price with no reserve. This means that the sale prices may reflect authentic market demand from real buyers.

Finally, look out for industry guides. There may be specialist guides to current trends and estimated valuations for certain styles or brands.

Get a Specialist Valuation

If you come across an item that you suspect may be rare or valuable, and you want to make absolutely sure that it is not a fake, then it might help to get a specialist valuation.

A specialist can advise you on the item’s provenance, and they may even be able to help you restore the item to make it even more valuable.

Obviously, this will take time, and specialists evaluators will not work for free. But if you suspect you have a genuine Gucci on your hands, for instance, then any costs may be entirely justified.

Once You Understand How Valuable Your Stock Is, Be Sure To Get It Covered

You can get insurance that will cover you for the risks associated with stocking and selling vintage clothes. Stock insurance will cover your valuable vintage items for loss or damage whether they are on your shop floor, in storage, or in transit.

When arrangine stock insurance, you’ll need to think about:

  • Accurate valuations: When getting cover for your vintage clothing business, it is helpful to provide your insurer with an accurate valuation figure for your stock. This way, they can ensure you are covered for the right amount, so that you will get the settlement you need should you ever need to make a claim.
  • Particularly valuable items: Some insurers may only insure your stock up to a certain value, so it is also important to notify your insurer about any particularly valuable items in your stock, just in case they would push your cover level beyond the limit.
  • Trends and value fluctuations: And remember that the value of vintage clothes tends to change! So be sure to revise your valuations as often as possible based on the latest trends, and to give your insurer an up-to-date value every time you renew your policy.

Get Vintage Clothes Shop Insurance From James Hallam

James Hallam is an independent Lloyd’s broker with a dedicated team of insurance professionals who care about protecting your business, whether you sell vintage clothes exclusively, or among other items in a second hand shop.

Find out how we can help you today.

How To Protect Your Business From Extreme Weather Events

How To Protect Your Business From Extreme Weather Events 1000 781 James Hallam

In recent years, the UK has faced heatwaves, floods, and a number of severe storms.

In this post we will explore the risks that your business might face should extreme weather events become more common in the UK, before discussing how you can manage and mitigate these risks.

Key Risks of Extreme Weather To Businesses

Heatwaves
High temperatures can lead to increased health risks for your staff and your customers.

The risk could be particularly high for anyone who works in a role that demands a lot of physical activity, or in environments where temperatures are already high, such as factories, warehouses, and industrial settings.

Storms
Storms can lead to travel disruption, which could affect your supply chain or your deliveries.

A storm could also lead to property damage, such as from falling trees or branches, and it could even lead to power cuts.

And a power cut could affect your business in a number of ways: You could lose your temperature controlled stock if your fridges or freezers fail, and if your security systems go down you may be more vulnerable to theft or vandalism.

Floods
Violent storms can also lead to flash floods, which could cause devastating damages to any kind of business.

And it is not just businesses located on flood plains that need to consider the risk of flood. Heavy rains could overwhelm drainage systems, which could lead to floods in areas that are not usually at risk of flooding.

How To Protect Your Business From Extreme Weather Events

If extreme weather events are becoming more common in the UK, below are some strategies that you could implement to safeguard your business against all kinds of weather-related risks, including:

  • Pay attention to Government warnings and weather alerts
  • Manage extreme temperatures
  • Flood planning and protection
  • Storm planning and protection
  • Insurance cover

We’ll explore each of these in more detail below.

Forecasts and Government Weather Warning Notifications

Pay attention to the weather forecast, and pay particular attention to any Government warnings about extreme weather events, and the possible risks they may bring.

When it comes to floods, take a look at the Flood Hub’s flood risk maps, which provide both a five-day flood risk forecast, along with potential long-term flood risks. You can also sign up for official Government flood warnings, which means you can get a call, text, or email if there are any particular risks in your area.

How to Manage Heatwaves in the Workplace

The Health and Safety Executive (HSE) does not specify a maximum working temperature for any workplace. This is because all workplaces are different, and some employees may routinely experience high temperatures as part of their work, such as those who work in factories, industrial settings, and warehouses.

However, the HSE does provide guidance on “thermal comfort”, outlining how high temperatures could encourage staff to exercise less caution and take more risks. For example, they may struggle to focus or concentrate, they may choose not to wear certain items of PPE, and they may cut certain corners that could put themselves, or others, at risk.

If you are worried about how a heatwave might affect your employees or your business, there are certain policies you could introduce to help your staff keep cool. The British Safety Council has published advice on staying safe at work during heatwaves, which includes:

  • Relaxing dress codes
  • Allowing staff to take more frequent breaks
  • Providing a supply of cold drinks
  • Introducing more flexible working policies

Protecting Your Business From Flooding

Sign up for alerts: Above we mentioned how signing up for flood alerts can give you an advanced warning that could give you time to prepare. However, a severe storm could lead to flash flooding, which could strike your business without warning.

Consider stock and equipment placement: There are some measures you could introduce that could help to limit the damage of any flooding on your premises. This can include storing any high-value stock or equipment on high shelves or upper floors.

Invest in drainage: You could also invest in systems that could help reduce the risks of flash flood affecting your business. For instance, you can install non-return valves on your business’s drains, along with the inlet and outlet water pipes. With these in place, even if the local drainage systems get overwhelmed, it will be less likely that any flood water will enter your premises.

Create a flood response plan: Beyond this, it is worth taking the time to design a flood response plan for your business. This could include steps staff should take to keep themselves safe, along with contingency plans to limit disruption to supply lines, deliveries, and other aspects of your operation.

Read our full guide to preparing your business for a flood. Though this guidance refers specifically to retail businesses, it features tips that could help to keep any business safe.

Protecting Your Business From Storms

Unless high winds cause a tree to fall on your business premises, then it is unlikely that a storm itself will threaten your business. However, long periods of heavy rain could make flash floods more likely, and stormy weather could lead to power cuts and other disruptions.

The best way to protect your business from storms is through assessing all the possible risks that a storm could bring, before designing a risk management plan to help you mitigate these risks:

  • Back-up generators to help you deal with power cuts. You could also ensure that there will always be backup power for your fire and security systems, so that power outages will not put your business at increased risk of fire, theft, or vandalism.
  • Continuity plans for dealing with disruption and business interruption. How would you manage any delayed deliveries or shipments, for example? Who would you notify, and what measures would help you manage operations until you get back on track?
  • Working arrangements: If your staff are temporarily unable to travel due to adverse weather conditions, could you introduce temporary flexible working arrangements that would enable them to work from home?
  • Safety protocols: Would a storm put any of your employees at risk on the job? Your employee safety procedures should specify the conditions in which employees should stop working and instead vacate to a place of safety, particularly if they work in a high-risk environment such as a construction site.

How Insurance can Protect Your Business From Extreme Weather Events

James Hallam is an independent Lloyd’s broker with a team of insurance professionals who are dedicated to protecting your shop from the risks you face from extreme weather.

We can help you understand the specific risks your business faces, and we will ensure that your business insurance will give you the cover you need when you need it most. For example, we can help you access specialist business insurance that will cover you for flood risks, and we will make sure that your business interruption insurance will help cover costs while you get back on track.

Learn more about our tailored insurance solutions for SMEs, and get a free quote today.