Posts By :

Sarah Clements

What Does The Super El Niño Mean For Travel Destinations?

What Does The Super El Niño Mean For Travel Destinations? 1000 667 James Hallam

A Super El Niño event means that the average sea surface temperatures in certain parts of the Pacific Ocean rise by 2°C or more. Such an event will bring a significant climactic impact, which could severely disrupt the global travel industry.

Scientists have suggested that the world might see a Super El Niño event in the next couple of years. In this post we will explore what the Super El Niño could mean for travel destinations, with some tips on how travel agents and tour operators might prepare.

The Potential Impact of Super El Niño

Rising sea temperatures can lead to a host of climate impacts, including:

  • Severe flooding
  • High temperatures
  • Drought, and an increased risk of wildfires and cyclones
  • Food shortages
  • Disruption to water supplies

How Will a Super El Niño Affect the UK?

The impacts of a Super El Niño will vary considerably at different times of the year, and in different parts of the world. In the UK, for example, an El Niño event usually leads to warmer summers and colder winters.

Which Countries Are Most Affected by the Super El Niño?

A Super El Niño event will have the biggest impact on countries that are close to the particularly warm areas of the Pacific Ocean. Some of these countries may see unusually hot and dry conditions, while others may see extremely wet conditions, with an increased risk of flooding.

Many of these countries are popular travel destinations in the winter months. Below we will take a closer look at some of the areas that travellers may choose to avoid outright in the coming years, so as not to face severe disruption and other risks.

What Does The Super El Niño Mean For Travel Destinations?

The following travel destinations are likely to be particularly affected:

  • California – Heavy rains can lead to flooding, and even mudslides, which could result in road closures and other disruption.
  • Peru and Ecuador – As these countries are the closest to the excessively warm areas of the Pacific Ocean, they could see the biggest impact from a Super El Niño event. Both countries could see extreme rainfalls and a critical risk of flooding.
  • Australia – Queensland and the wider northeast area of Australia could see soaring temperatures with a potential for drought.
  • Southeast Asia – Countries such as Indonesia and Thailand may also experience drought conditions, with a risk of wildfire and water shortages.

How Should Travel Agents and Tour Operators Prepare For a Super El Niño Event?

Travel agents and tour operators should take steps to manage the risks of a Super El Niño event, while ensuring that their customers are aware that high Pacific temperatures can lead to significant travel disruption and other risks.

Look For Alternative Destinations

Some areas may actually benefit from a Super El Niño event. As we mentioned above, it usually means hotter summers for the UK, so many travellers may simply choose to stay closer to home.

Super El Niño is unlikely to affect snowfall in The Alps, so any travel agents or tour operators who usually sell packages to North American ski resorts may choose to focus on European resorts instead.

Also, the effects of Super El Niño can vary wildly across individual countries, too. Travel agents and tour operators may not have to look very far when seeking alternative travel destinations. For example, while drought may hit southern Thailand, northern Thailand may experience relatively cooler temperatures.

How to Stay On Top Of Developments And Keep Travellers Informed

The UK Government routinely provides travel advice for over 200 overseas countries or territories. During a Super El Niño event, this advice could cover the risks of drought, flooding, wildfires, and other climate impacts.

Find a way to stay on top of the latest travel advice, and take steps to keep your customers updated on any developments. Aim to communicate frequently and consistently, and try to establish an expectation that situations can change quickly.

Read our full guide to communicating travel advice to customers.

Contingency Planning and Insurance

Risk management and contingency planning can give you a clear course of action to follow in the event of an emergency situation, whether this is a simple cancelled flight, or mass disruption following a flash flood or a wildfire.

Outline the immediate steps you would take in order to support your customers and ensure they can stay safe. For example, how would you stay in touch with overseas travellers in situations where established lines of communication may be affected?

Also be sure to advise your customers on the cover they might expect from their travel insurance, along with the limits to the cover. For example, travel cover may not apply if a customer ignores the travel advise and intentionally travels to a high-risk area.

Specialist Insurance Services For Travel Agents and Tour Operators

At James Hallam we have provided dedicated insurance services for travel agents and tour operators for over 35 years. In this time, we have provided advice from our experienced team and cover throughout numerous Super El Niño events.

Find out more about our bespoke insurance services for travel agents and tour operators or call us on 0203 967 1923 or email david.mcgregor@jameshallam.co.uk.
Can You Be Hacked From Opening an Email?

Can You Be Hacked From Opening an Email? 1000 668 James Hallam

Phishing and social engineering attacks are among the most common forms of cybercrime. Such attacks largely depend upon the target taking specific action, such as visiting a malicious website, downloading a malicious file, or inadvertently disclosing sensitive information.

But what if you receive a phishing email, and you do not click any links or download any files from it? Can you be hacked from opening an email?

Can You Get Hacked From Just Opening an Email?

It is technically possible for a cybercriminal to encrypt an email with malicious code, meaning that just opening the email, or even accessing the preview pane, could change your system settings, or trigger a download. However, nowadays, email service providers use a number of systems to prevent any unauthorised access to your personal settings or your operating system.

Modern email systems simply display static text and images with no live scripts or executable codes.

Just opening an email, even if the email itself contains malicious code, should not cause you any issues.

This means that, in order for a phishing or social engineering attack to work, the cybercriminal needs you to take certain actions.

How Else Can You Be Hacked By Email?

The actions a cybercriminal would want you to take would be to access a certain website, or fill in a certain form, or download a certain attachment. Any of these could allow them to install malicious software on your device, which will leave you vulnerable to data breaches, ransomware attacks, or other forms of cybercrime.

How Email Providers Keep You Safe

  • They display emails in a restricted environment which will display a message’s text and images while preventing any embedded codes from interacting with your device and its files. This is known as sandboxing.
  • They block external images as standard, or they route them through their own secure services. As the images do not load automatically, no files are downloaded to your device, which prevents the cybercriminal from getting backdoor access to your system.
  • They scan all potential messages for any red flags, including malicious code or links to known phishing sites. This means that any serious threats are caught and contained before they even make it to your inbox.

Just Because You Cannot Be Hacked From Opening an Email, It Does Not Mean That There Is No Danger

What Information Can Be Gained From an Opened Email?

So, cybercriminals cannot hack your system or access your personal data if you simply open a phishing email. Yet opening a suspect email could still lead to privacy risks, and even leave you more vulnerable to identity theft.

It is possible to embed tracking pixels in emails. These are tiny graphics that are literally the size of a single pixel. They can be transparent, which makes them totally invisible to anyone who is not actively looking for them.

Businesses can use these tracking pixels to measure the reach of their marketing emails. Unfortunately, cybercriminals can also use them in order to gather certain information about you.

This information will be limited. Often, all they can see is your location (via your IP address), along with the type of device you used to access the message, and the time at which you accessed it. And crucially, if they can gather this information, it confirms that your email address is active, and that you will actively engage with certain types of content.

In the long-term, cybercriminals could use this information to build a profile of you. They will come to understand your habits, and they may ultimately learn what sort of messages are most likely to get your attention.

So, eventually, these cybercriminals may catch you when your guard is down, meaning that you will unwittingly take that necessary second step: Clicking a link, or downloading a file.

Opened A Malicious Email? Don’t Panic!

As we have seen, simply opening a malicious email is not likely to compromise your device or your data. And if doing so exposes you to any future privacy risks, you will be safe so long as you stay vigilant, and so long as you never click any links or download any attachments in any future phishing emails.

There are a number of steps you can take and habits you could adopt if you opened a phishing email and you are concerned about future cyberattacks:

  • Change your passwords, using a reliable password management system if possible. This will automatically and routinely create secure new passwords for any online service you use.
  • Use multi-factor authentication wherever possible. This means that, instead of simply using a password to access a system or service, you will also use additional credentials such as a pin, a one-time-access code, or even biometric information.
  • Get a good antivirus system, which will automatically detect if any unauthorised malicious scripts attempt to run on your system.
  • Stay on top of system updates, and keep your web browser, your email provider, and your antivirus system updated too. The latest updates will include the latest security features, with fewer loopholes or backdoors for cybercriminals to exploit.

What To Do If You Clicked a Link or Downloaded an Attachment From A Phishing Email

It is important to act quickly:

  • Disconnect from the internet, and turn off your device’s wi-fi. Wait a few minutes before you go back online. And before you connect again, tell your device to “forget” the wi-fi network.
  • Change all passwords you use to access any secure online services, and make sure the account recovery information is still correct.
  • Run an antivirus or malware scan on your device.
  • Get in touch with your bank, and ask them to monitor for any suspicious activity.
  • If you are using a device that belongs to your business or your employer, notify their IT or cybersecurity team immediately.

Specialist Cyber Insurance – An Essential Line of Defence

As well as covering your liabilities during a cyberattack, cyber insurance can also cover certain expenses associated with your response, including the costs of notifying clients or customers whose data may have been compromised by a breach.

Read our full guide to how cyber insurance can help protect your business.

James Hallam is an independent Lloyd’s broker with access to a hand-picked selection of A-rated insurance providers. We can help you find the cyber insurance you need at a competitive price.

Get in touch for a free quote today.

What is Deterioration of Stock Insurance?

What is Deterioration of Stock Insurance? 1000 568 James Hallam

Deterioration of stock insurance can provide essential cover for any business that sells or stores perishable goods.

In this post we will explain what deterioration of stock insurance is and what it covers, along with some common exceptions and limitations to the cover.

What is Deterioration of Stock Insurance?

If an unexpected event causes your perishable stock to spoil or degrade, then deterioration of stock insurance can cover your losses. Specifically, this cover can provide some financial compensation should deterioration make your stock unsuitable for sale.

Business insurance policies generally will not offer cover for stock deterioration as standard. To get the protection you need, you will either need to get a specialist policy, or you will need to add the cover to an existing policy.

Some insurers may specify that you introduce certain measures in order to safeguard your stock, as a condition of cover. This might include installing a failsafe, such as a backup power system, while staying on top of equipment cleaning, servicing, and maintenance schedules.

What Does Deterioration of Stock Insurance Cover?

Deterioration of stock insurance covers loss or damage of perishable goods that need to be stored at certain temperatures.

For example:

  • A power failure causing a fridge or a freezer to fail.
  • Water damage from leaks or flooding.
  • Transport issues – for example, a truck transporting temperature-controlled goods is involved in an accident, resulting in equipment failure.
  • Damage from insufficient heating, cooling, or unwanted temperature fluctuations.

Are There Any Exclusions and Limitations to Deterioration of Stock Insurance?

Most deterioration of stock insurance policies will list a number of exclusions and limitations. These might include:

  • Poor Maintenance and Neglect – If a fridge, freezer, or other equipment fails as a result of poor maintenance, your insurer may reject your claim. Stay on top of servicing and cleaning schedules to ensure you get the cover you need.
  • Foreseeable Events – Similarly, your insurer will likely reject your claim if your stock deteriorates as a result of an incident you could have foreseen and prevented. For instance, you might have to take special measures to protect your stock in the event of a heatwave. If you were aware that high temperatures were forecast, but you did not work to secure your stock, then you may not be covered for any loss.
  • Natural Deterioration – Deterioration of stock insurance is designed to cover sudden and unexpected events. It will not cover losses due to slow or gradual decline.
  • Pre-Existing Problems – If your stock was already faulty before you put it into storage, then your insurance probably will not cover you for any unexpected events leading to total loss.
  • Security Issues – If your equipment fails as a result of a break in, your insurer may reject your claim if they find that you did not take adequate steps to secure your premises. Most policies also include standard exclusions for losses due to war, terrorism, riots, and civil unrest.

Who Needs Deterioration of Stock Insurance?

Any business that stores, transports, or sells perishable goods could benefit from deterioration of stock insurance. This might include:

  • Cafes, restaurants, bakeries, butchers, delis, takeaway shops, and any other business that prepares and sells food on the premises.
  • Greengrocers, corner shops, newsagents, off-licenses, wine merchants, and supermarkets.
  • Pharmacies, along with any business that stores or sells cosmetic and beauty products.
  • Florists and other horticultural businesses.
  • Warehouses that specialise in storing any kind of perishable good.

Get The Cover You Need for Your Stock

James Hallam is an independent Lloyd’s broker with access to a hand-picked selection of A-rated insurance providers.

We can help you get the specialist stock deterioration insurance you need to protect your business against unexpected events. We can also advise you on essential risk management procedures that could make stock deterioration less likely, and we can show you how to evidence these measures to your insurer in order to potentially reduce the cost of cover.

Get in touch for a free quote today.

How To Identify Risks in Your Business

How To Identify Risks in Your Business 1000 667 James Hallam

There is more to risk management than identifying possible sources of accidents and injuries. It is also important to identify risks that could lead to inefficiencies, disrupt your operations, increase your overheads, and affect your cashflow.

In this post we will explore how to identify risks in your business, and establish the process for managing, mitigating, or eliminating these risks.

Common Risks for Every Business

When assessing the sources of risk in your business, you should consider:

  • Property Risks – Including damage from fire, flood, subsidence, and other incidents, along with losses from theft, vandalism, and other crimes.
  • Finance Risks – Including cash flow fluctuations, debt management, and economic uncertainty.
  • Operations Risks – Including bottlenecks and inefficiencies that could lead to risks, possible hazards posed by outdated or faulty tech, and poor quality control measures.
  • Cyber Risks – Including financial and reputational damages from cybercrime, and liability costs from data leaks and data loss.
  • Legal Risks – Such as claims involving intellectual property theft, dishonesty, negligence, and fraud.
  • Supply Chain Risks – Including dependencies, issues with transportation, and potential disruption.
  • Stock Risks – Such as losses from theft or spoilage. You will have to consider additional risks if you routinely store or work with hazardous materials.
  • Staff Risks – Including issues with compliance, training, skill gaps, and turnover.

How Create Your Risk Management Process

For every risk that you identify for your business, you should also identify the following:

  • Who is at risk? Who might be affected by a particular risk, and how might it affect them? Consider whether each risk will affect staff, customers, contractors, delivery drivers, visitors, or a combination of the above. Also bear in mind that some people may experience risks differently. Someone with vision or hearing problems, for example, may find it harder to follow evacuation procedures.
  • How likely is the risk? Plus, how severe would the outcome be? This could range from financial or reputational damages to serious injuries and death. After you have quantified your risks in this way, you can prioritise them based on their probability and severity. This will allow you to allocate your risk management resources effectively.
  • How are you going to manage, mitigate, or eliminate the risk? The specific steps you take will of course depend on the risk in question. Though for every action you identify, you should also establish who is responsible for carrying it out, along with a timeframe for completing it, and a process for reviewing the risk assessment.

Managing Your Business Risks

Read our essential guide to risk management for businesses. We also have a number of specialist guides for certain kinds of businesses. Some of these offer general risk management advice, but others focus on specific risks, such as fire, theft, or cybercrime.

General Risk Management Guides

Cyber Risk Management Guides

Fire Risk Management Guides

Get Tailored Insurance For Your Business

James Hallam is an independent Lloyd’s broker with access to a hand-picked selection of insurance providers.

We can help you understand the risks your business is facing, and we can advise you on how to effectively manage these risks. We can then help you access the business insurance you need, and we can show you how to evidence your risk management processes in order to make savings on the cost of cover.

Get in touch for a free quote today.

Why is Retail Theft Rising in 2026?

Why is Retail Theft Rising in 2026? 1000 666 James Hallam

Shops across the UK are reporting a rise in retail theft. According to figures from the Office for National Statistics (ONS), over 500,000 incidents were reported in 2025 – 2026, a rise in 5% compared to the previous year.

In this post we will outline some of the underlying causes of this rise in retail theft, before exploring some ways you can help to prevent theft in your store.

Underlying Causes of Retail Theft Rising

There are a number of factors which affect crime rates, particularly theft. In 2026, we are seeing the following contributory factors:

  • Cost of living crisis
  • Organised crime
  • Staffing issues
  • Rise in self-checkouts

We’ll explore each of these individually below to find out more about the causes and how it may impact target items.

The Ongoing Cost of Living Crisis

The UK has been struggling with high inflation rates for a number of years, which greatly increased the cost of living for millions.

Rising food costs may have contributed to the increase in shoplifting. Baby formula is one of the most commonly stolen items in the UK, and this is likely because it is both essential and expensive.

Organised Crime

Some retail bodies claim that organised crime is driving a rise in retail theft.

Some of this may be relatively small scale, such as the thieves who steal premium cuts of meat to sell to pubs and other establishments. But some retailers have fallen victim to larger gangs that have targeted multiple stores in succession.

Even worse, this form of theft seems to be linked with rising incidents of violence and abuse against frontline retail staff.

Staffing Issues

Rising costs have forced many stores to cut staff hours, and the UK workforce as a whole has shrunk in recent years.

Fewer staff on the shop floor means that there are fewer people to look out for the signs of shoplifting, and more blind spots for thieves to operate in.

The Rise of Self-Checkouts

Many stores have started offering self-checkout services, partially as a way of managing costs, and partially as a way of offering a more streamlined experience to customers.

Some self-checkout areas feature systems designed to prevent theft, such as security cameras, and gates that will only open if the customer scans a code they receive after purchase. But nonetheless, the perceived lack of security around self-checkout areas may be fueling a rise in shoplifting.

Some customers find self-checkout systems confusing, which may mean they unintentionally take some items without paying. And while they may not be shoplifting in the strictest sense, this will still lead to losses for the store.

The Impact of Retail Theft on Stores

How To Reduce Theft in Your Store

We have a number of guides on our site to help you address retail theft in your store:

It is also important to address the risks of employee theft in your store. Read our full guide to understanding and preventing employee retail theft.

Get The Right Cover For Your Retail Store

A specialist retail insurance policy can cover your store for many of the losses you may experience as a result of theft and other incidents, subject to policy terms, conditions and exclusions.

James Hallam is an independent Lloyd’s broker with an experienced team of insurance professionals who care about protecting your store.

Find out how we can help your shop today.

How to Prevent Slips, Trips, and Falls in Your Shop

How to Prevent Slips, Trips, and Falls in Your Shop 1000 667 James Hallam

Slips, trips, and falls are a major issue for retail businesses, and there are severe penalties for shops that do not take the time to address the risks.

In this post we will explore some of the possible underlying causes of slips, trips, and falls in the retail environment. We will also outline how you can address these risks in your store.

What Causes Slips, Trips, and Falls in Shops?

There are a number of different causes for slips, trips and falls in shops, including:

  • Clutter – Any stock or equipment left in walkways can create a trip hazard for both staff and customers.
  • Liquids – A spilled liquid creates a slipping hazard. But customers may also slip on a freshly cleaned surface, particularly if there are no warning signs about, or if staff used too much cleaning product.
  • Mats, Rugs, and Tiles – People may trip over a rumpled mat or rug, or a loose tile on the floor.
  • Environmental factors – People may fail to spot slip or trip hazards if the lighting is poor. Or they may lose their footing if they do not see a step or a ramp.

How To Prevent Slips, Trips, and Falls in Your Shop

To help reduce and prevent slips, trips and falls in your shop, you should consider:

  • Staff Training – Train your staff to spot the risks that could contribute to slips, trips, and falls, and make sure that everyone knows what to do to address these risks. Also make a point of recording and reporting any incidents that occur, specifying exactly what went wrong, and outlining the steps you will take to prevent further incidents.
  • Stay On Top of Cleaning – Establish a cleaning rota and aim to clean up any spillages as soon as possible. It is also important to use the right cleaning products, and in the right quantity. Use the wrong product and you may not effectively remove a spillage. And use too much of a product and you could make the slipping hazard even worse.
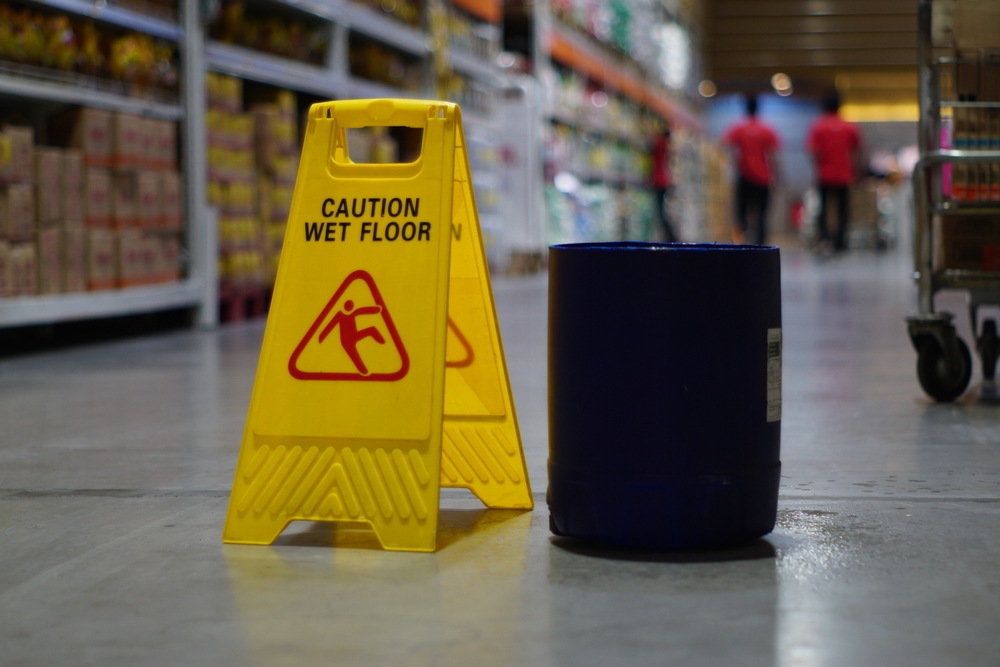
  • Make Customers Aware of the Risks – After cleaning, place signs warning customers of slippery surfaces. If there are any steps or ramps on the shop floor, make sure they are clearly indicated, with signage if necessary.
  • Stay On Top of Maintenance – Replace faulty lighting, damaged floor tiles, and any other faults that could lead to accidents as soon as possible.
  • Reduce Clutter – Never leave stock or cleaning equipment unattended in walkways. This goes for your storeroom as well as your shop floor. Your staff are just as liable to get injured by a slip, trip, or fall as your customers.

Risk Management and Insurance

Addressing the common causes of slips, trips, and falls should form a part of your wider risk management strategy. Read our full guide to risk management for retail businesses.

As we mentioned above, there are severe penalties for any store that does not take the time to mitigate slipping and tripping hazards. The Health and Safety Executive has numerous case studies of slips and trips that ultimately cost retail stores dearly.

Specialist retail insurance can help cover any legal costs or settlements that may arise as a result of an incident in your shop. You have a legal duty to get employers liability insurance to cover the risks for your staff, while public liability insurance can cover any incidents that affect customers, contractors, delivery drivers, and other members of the public.

There are strong links between risk management and insurance. Your insurer may require you to implement certain risk management processes as a condition of your cover. But at the same time, if you can evidence your risk management efforts, you may be able to make a saving on the cost of cover.

Get The Right Cover For Your Retail Store

A specialist retail insurance policy can help provide cover for losses you may experience as a result of slips, trips, falls, and other incidents, subject to policy terms, conditions and exclusions.

James Hallam is an independent Lloyd’s broker with an experienced team of insurance professionals who care about protecting your store. We can help you access the cover you need for your business, and we can also show you how to evidence your risk management in order to make potential savings on your premiums.

Find out how we can help your shop today.


Competent Crew Requirements in Shipping

Competent Crew Requirements in Shipping 1000 668 James Hallam

A well-trained, competent crew is essential for ensuring operational safety and efficiency. Adequate crew training is also a core component of numerous international shipping standards and regulations.

In this post we will outline some of the key crew training requirements in shipping. As well as exploring the benefits of a competent crew, we will also discuss some of the risks you may face if your crew fails to meet the appropriate training standards.

International Standards for Competent Crew Requirements

The International Convention on Standards of Training, Certification, and Watchkeeping for Seafarers (STCW) was first adopted in 1978 and has seen numerous amendments in the intervening years. The STCW Convention establishes minimum basic international standards for training, certification, and watchkeeping for seafarers.

The Convention features four modules of basic safety training, including Personal Survival Techniques, Fire Prevention and Fire Fighting, Elementary First Aid, and Personal Safety and Social Responsibility. Seafarers must complete these four modules before they are assigned to duties on a seagoing ship.

Recent amendments to the STCW Convention include new modules on bullying and harassment, and a requirement for cyber-awareness training for officers.

Beyond this, the International Maritime Organization (IMO) established the minimum standards for manning levels in the International Convention for the Safety of Life at Sea (SOLAS), 1974.

You can read the full guidelines for the application of the IMO safe manning principles.

Certificates of Competency

Under the STCW Convention, flag states are responsible for issuing Certificates of Competency (CoCs) to seafarers who have completed the required training. CoCs are often only necessary if the crew members are undertaking certain duties, and even then, they may only be necessary if the ship is of a certain size, or if it is operating in certain areas.

Broadly speaking, the following crew members are generally required to have CoCs:

  • Deck officers, especially if they perform navigational and bridge watch-keeping duties
  • Engineering officers
  • Radio operators
  • Cooks
  • Security operators

CoCs must be revalidated every five years. Seafarers can revalidate their certificates through demonstrating that they have completed either 12 months of sea service in the last five years, or three months of sea service in the last six months. You can learn more about CoC revalidation.

If seafarers from certain non-UK countries want to work as an officer on a UK-registered ship, then they can apply for a Certificate of Equivalent Competency (CEC) instead.

You can read the full UK Government guidance on competent crew requirements, including the necessary qualifications and documentation, here.

How Crew Competency Affects Seaworthiness

Under the Merchant Shipping Act 1995, it is a criminal offence to send, or to attempt to send, an “unseaworthy” ship to sea. Seaworthiness has also been an implied warranty of all standard marine insurance policies since the introduction of the Marine Insurance Act of 1906, which outlined that vessels must be “reasonably seaworthy in all respects.”

Shipowners have a legal responsibility to ensure that their vessels are seaworthy at the start of their voyage, and throughout. While seaworthiness largely depends on the physical condition of the vessel, it also hinges on the competency of the crew.

For example, in a recent case involving the grounding of the Happy Aras bulk carrier, the court ruled that the master’s incompetence had rendered the vessel unseaworthy.

Following an incident, if the shipowner’s due diligence and the vessel’s seaworthiness come into question, it may not be enough to simply demonstrate that your officers were appropriately certified. It may also be necessary to evidence your recruitment, onboarding, training, supervision, and performance monitoring procedures. These can demonstrate how you ensure your crew remains competent, and your vessel thus remains seaworthy, throughout a voyage.

Owner/Operator Responsibilities for Having Competent Crew

The International Maritime Organization Rules 26.2.2 outlines the responsibilities of owners and operators in ensuring that vessels are safely and sufficiently manned.

These responsibilities include:

  • Assessing all tasks, duties, and responsibilities necessary for the vessel’s safe operation, for the protection of the marine environment, and for dealing with emergency situations.
  • Identifying the skills and experience required to fulfil all necessary functions.
  • Ensuring the manning level is adequate at all times, accounting for peak workloads.
  • Reviewing the manning level in the event of any changes in the nature of the operation.
  • Ensuring that all working arrangements also allow for sufficient rest periods, so as to avoid fatigue.

You can read the full list of IMO general principles for ensuring that vessels are safely and sufficiently manned.

The Importance of a Competent Crew

A competent crew is essential for ensuring operational safety and efficiency. With adequate training, in the event of an incident at sea, every member of the crew will know exactly what they need to do to keep themselves and others safe.

Good training can also help to reduce the losses in the event of an accident. If a fire breaks out onboard, for example, the crew should be able to contain the blaze before it has a chance to spread.

With all this in mind, the risks you will face if your crew does not meet the minimum safety standards should be obvious: The ship will likely be plagued by operational inefficiencies and health and safety oversights. Your operations may fall behind schedule, and should anything go wrong, the crew may not know how to react. Their actions could lead to further damages, along with serious injuries, and even death.

Plus, if you fail to meet these international training standards, you may face fines and other penalties for non-compliance. There could be insurance implications too. Following an incident at sea, if your insurer finds that you did not act to ensure your crew met all relevant standards, then they may reject your claim.

We Can Help You Get The Dedicated Insurance You Need For Voyages

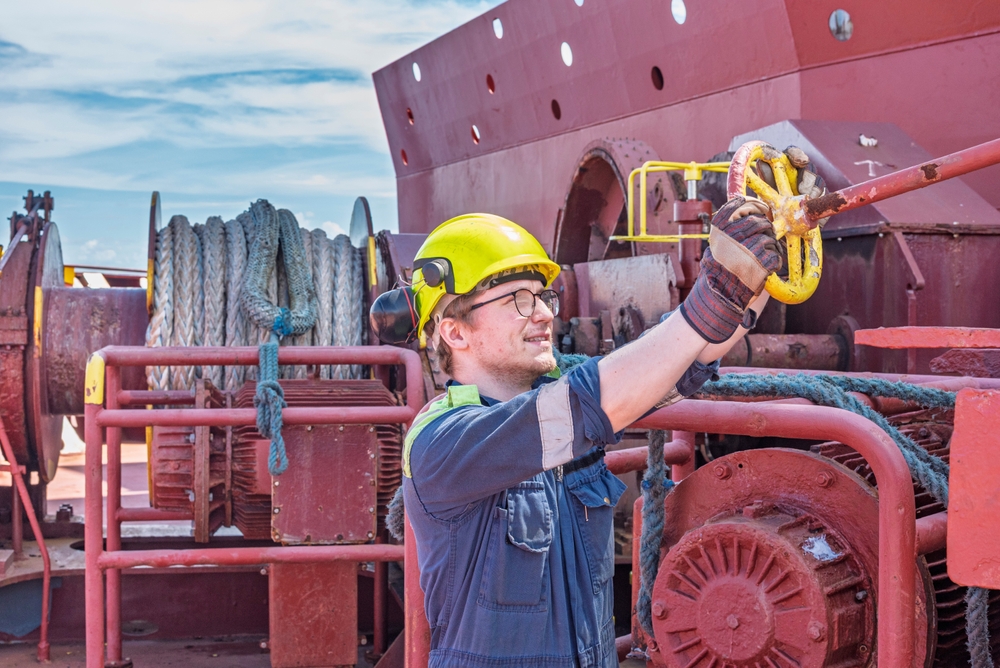
Everard Insurance Brokers provides specialist marine insurance solutions, helping businesses protect valuable shipments throughout the supply chain. We can help you understand the training and regulatory requirements that may apply to your ship and your crew. We can also help you access insurance solutions tailored to the risks you may face both at port and at sea.

Find out more about our specialist marine insurance services.


ATOL Regulations and How To Become Registered

ATOL Regulations and How To Become Registered 1000 667 James Hallam

The ATOL scheme provides travellers with financial protection when they book a package trip that includes some airline travel.

In this post we will explain what ATOL is, and how it works. We will also look at who needs a license, and outline the steps required to get registered. Finally, we will explain some of the penalties and other consequences you could face if you fail to get an ATOL licence when required.

What is ATOL?

ATOL stands for Air Travel Organisers’ Licensing. First introduced in 1973, the ATOL scheme provides travellers with financial protection when they book a package holiday that includes a flight. This protection is separate from their travel insurance cover.

What Does ATOL Do?

ATOL providers must provide their customers with an ATOL certificate whenever they book an ATOL protected trip. Among other things, this document will outline exactly who and what is covered by the ATOL scheme.

If an ATOL registered travel provider ceases trading while their customers are overseas, the ATOL scheme can help the customers to continue their trip through providing some financial support. This can include reimbursement for accommodation, car hire, and transfers, along with support with flights home where necessary.

Exemptions to ATOL Cover

The ATOL scheme does not cover all flights. There are also numerous exceptions to the ATOL coverage, including issues with accommodation, and missing or damaged luggage.

For more information, you can read a full guide to what ATOL does not cover.

When Do You Need To Be ATOL Registered?

The ATOL Scheme is run by the Civil Aviation Authority (CAA), and there is extensive guidance on their website concerning who needs an ATOL, and who is exempt.

Businesses that offer flight packages or flight-only sales to UK passengers are legally required to get an ATOL. This includes businesses based outside of the UK that advertise and sell to customers within the UK.

Travel agencies, tour operators, and online travel retailers may be required to get a licence as part of the Package Travel Regulations. Some travel agents may not be required to hold their own ATOL, such as those who only sell accommodation packages, or those who exclusively sell premade packages that include flights. However, even if a travel agency is exempt from the scheme, they must:

  • Exclusively work with providers who do own an ATOL.
  • Advise their customers on whether or not any flights they book through them are covered by the ATOL scheme.
  • Make it clear just what the ATOL scheme covers, and what it does not cover.
  • Ensure that their customers receive a valid ATOL certificate.

As part of the regulations, all ATOL holders must appoint an accountable person (AP) to ensure that their company complies with the CAA’s terms and conditions.

How To Become ATOL Registered

To get ATOL registered, you will first need to pay an application fee. This can be in the form of a fixed charge, and the amount you pay will depend on the size and nature of your business. At the time of writing, the fees range from £981 to £2,601.

You will also need to take a fitness and a finance test, so that the CAA can confirm that your business has the competence and the capacity to hold a licence. And ultimately, you will need to introduce a mechanism for protecting your customers’ money – with a bond, for example.

You will have to renew your licence once a year, and you will have to go through a similar assessment process every time you renew.

Though it is possible to get an ATOL licence from a franchise or an accredited body, many businesses choose to apply directly to the CAA. You can read the full CAA guidance to applying.

Penalties for Not Being ATOL Registered?

If you are legally required to get an ATOL, either as part of the CAA regulations or under the Package Travel Regulations, then you will face some severe penalties for non-compliance.

The CAA has numerous enforcement powers, and they can pursue criminal prosecution for businesses and individuals. They have also pledged to publicise some of their enforcement actions, in order to provide transparency for consumers, and to create a strong deterrent for non-compliance.

This essentially means that they are prepared to “name and shame” any travel providers that do not comply, which would likely lead to considerable reputational damage. So, even if they do not face prosecution, any business or individual that falls foul of the CAA regulations may struggle to ever trade again.

There may also be some insurance implications for non-compliance. Travel agents and tour providers often rely on scheduled airline failure insurance and supplier failure insurance to cover their own losses should a provider cease trading. But if your insurer finds that you failed to get an ATOL where necessary, or that you neglected to check that your providers were ATOL registered, then they may reject your claim.

How to Ensure You Are Fully Covered as a Travel Agent or Tour Operator

At James Hallam, we have provided dedicated insurance services for travel agents and tour operators for over 20 years.

We can advise you on whether you have a legal obligation to get an ATOL based on the packages you sell. We can also help you access the specialist insurance you need to ensure that, in the event of a supplier failure, you can cover your losses as well as your customers’ losses.

Find out more about our specialist insurance services for travel agents and tour operators.


How Does Second Home Insurance Work?

How Does Second Home Insurance Work? 1000 667 James Hallam

Your standard home insurance policy will not cover any second homes or holiday homes you own. For appropriate protection, you will need a dedicated second home insurance policy.

In this post, we will outline how second home insurance works: Why you need it, what it covers, and how much it might cost. We will also briefly explore the differences between second home insurance and holiday let insurance.

Why You Need Second Home Insurance

Second homes and holiday lets will likely be left unoccupied for periods of time. There are multiple risks associated with leaving properties unoccupied for an extended period. The property may be vulnerable to break-ins and vandalism, for example. And if there is nobody around to look after the property, a small issue such as a burst pipe could eventually escalate into a disaster.

The problem is that standard home insurance policies will only cover occupied properties. The policy will not provide any cover if the property is left unoccupied for more than a specified period, which is usually between 30 and 60 days.

This is why you will need specialist insurance for any second homes or holiday lets in your portfolio. A dedicated policy can provide cover for the risks that come with leaving properties unoccupied for long periods. It can also provide additional liability cover should you choose to let your property to paying guests.

Second Home Insurance vs. Holiday Let Insurance – What Is The Difference?

Both second home insurance and holiday let insurance provide cover for periods when a property is unoccupied. The key difference is that holiday let insurance includes additional liability protection and cover for the risks associated with renting the property to paying guests or members of the public.

For example, if a guest injures themselves while staying at your property and alleges that you were responsible, your holiday let insurance may cover compensation you are legally required to pay, along with legal fees that may arise in the event of a dispute, subject to the policy’s terms, conditions, exclusions and limits

What Does Second Home Insurance Cover?

Second home and holiday let insurance can typically provide cover, subject to policy terms and conditions, exclusions and limits for losses or damage arising from:

  • Forced entry, vandalism, and malicious damage
  • Theft
  • Escape of water
  • Severe weather events, including flooding
  • Subsidence
  • Structural damage
  • Property owners liability cover (for holiday lets)

How Much Is Second Home Insurance?

The cost of your second home or holiday let insurance will depend on a number of factors.

Holiday let or second home
Holiday let insurance will likely cost more than a standard second home insurance policy, due to the need for property owners liability cover on top of the other core areas of cover.

Location
The location of your property can make a difference. You may have to pay more for cover if your property is located in an area with relatively high crime rates, or somewhere with a particularly high risk of flooding. You may also have to pay more for cover if your property is located overseas.

Property size and value
The size and value of your property may affect the cost of any potential repairs following an incident such as a fire or a flood. You may also need additional contents cover if you keep any particularly valuable items in your second home or holiday let.

Get A Free Quote For Second Home Insurance Today

James Hallam is an independent Lloyd’s broker with extensive experience in helping individuals protect their assets. We will take the time to understand your property portfolio, before helping you access the specialist insurance solutions to meet your individual needs.

Get in touch for a free quote today.

How Much D&O Insurance Do I Need?

How Much D&O Insurance Do I Need? 1000 528 James Hallam

If your business faces any legal action, Directors and Officers (D&O) insurance may help cover defence costs against your business’s decision-makers for any personal liability related to their roles, subject to terms, conditions & exclusions. But while most businesses understand the value of D&O insurance, many may wonder just how much D&O insurance they need.

In this post we will explore some of the factors that can determine the level of D&O cover you need. We will also explore some of the risks you may face if you do not have the right level of cover in place.

What Does D&O Insurance Cover?

If anyone makes a claim against any of your directors and officers for alleged wrongful acts, D&O insurance may help cover defence costs and certain damages or settlements that may arise, subject to the policy’s terms & conditions.

D&O insurance can cover any costs associated with allegations of:

  • Neglect
  • Error
  • Trading offences
  • Misleading statements
  • Breach of trust or duty
  • Data breaches

How Much D&O Insurance Do I Need?

How much D&O insurance is enough? The amount of cover you need will depend on the size and nature of your business. You will need more cover if you have external investors, for example, or if you engage in regulated activity.

SMEs with an annual turnover of £10m or less will typically get a D&O cover limit between £1m and £3m.

But if you conduct any regulated activity – if you are an FCA authorised firm, for example – then you might need a cover limit as high as £10m.

Larger listed companies with external shareholders, complex operations or higher risk activities would generally look to get a higher limit of cover, which is likely to have a minimum of £10m indemnity.

Why You Need D&O Insurance

Claims alleging of wrongful acts by directors and officers can be costly. Without D&O cover in place, your business’s decision makers may be held personally liable for certain defence costs, settlements or damages arising from covered claims.

As well as having D&O cover in place, it is equally important to ensure you have sufficient cover for any potential legitimate claims you may face. If your policy’s cover limit does not meet the total cost of a claim this may leave the directors, officers or the business exposed if the total cost of the covered claim exceeds the available cover. Here are some examples of when directors and officers faced personal liability for allegations of wrongdoing:

But while your business is unlikely to face billions in settlements, you should never underestimate the potential cost of a claim, particularly if you have external shareholders, or if you operate in a heavily regulated industry.

How To Ensure You Have An Appropriate Level of D&O Cover

If you want to ensure you have an appropriate level of D&O cover, you could look to the typical levels of cover for businesses of your size and in your sector. As we mentioned above, some businesses will need more cover than others, therefore it will depend upon your individual circumstances.

But for every business, it is important to consider the potential cost of defending claims, as legal and professional expenses can be significant.  A higher policy limit may provide greater financial protection .  The best way to ensure you have the right level of D&O cover for your business is through working with an insurance broker. An experienced broker will help you understand the specific risks and liabilities your business’s directors and operators may face to allow you to make an informed decision. They can then help you access a policy that aligns with your needs and budget.

Directors & Officers Insurance Services From James Hallam

James Hallam is an independent Lloyd’s broker with a team of experienced insurance professionals who care about protecting your business.

We can advise you on your business insurance requirements and help you find a D&O insurance solution that aligns with your business needs and budget

Read our full guide to the many benefits of D&O insurance, and get in touch for a free quote today.