Posts By :

Sarah Clements

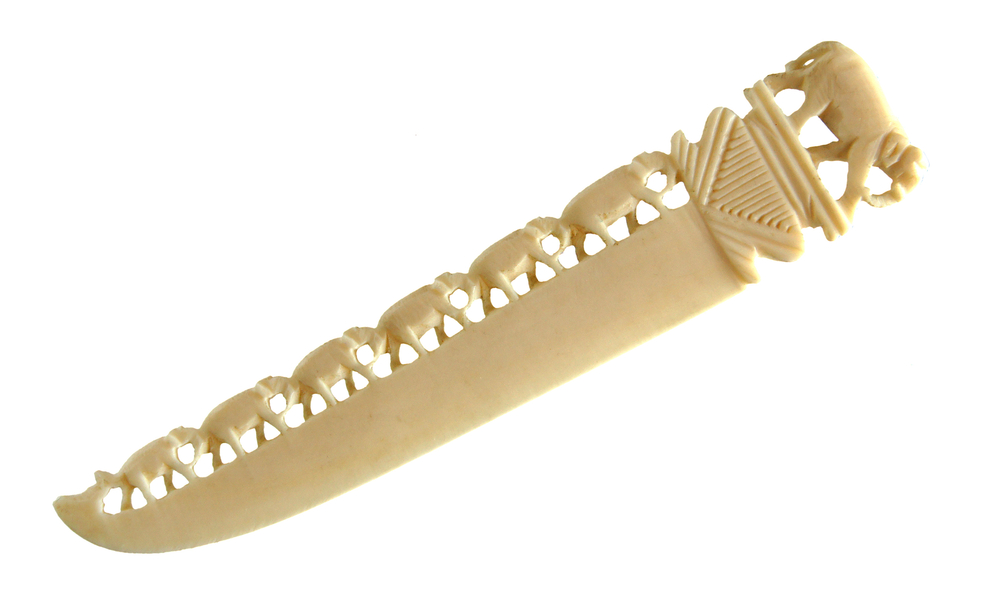
What To Do With Inherited Ivory

What To Do With Inherited Ivory 1000 611 James Hallam

If you have inherited ivory, then you should familiarise yourself with the strict laws that govern the buying and selling of ivory in the UK.

In this post we will outline the UK laws for handling ivory, and assess how these might affect how you manage your inheritance.

Is Ivory Illegal?

Under the Ivory Act 2018, it is illegal to buy or sell most items containing ivory in the UK. The law extends to items that incorporate ivory from elephants, hippos, and marine animals such as narwhals, killer whales, and sperm whales. There are separate laws for items containing ivory from species that are not specified in the Ivory Act 2018, such as ivory from walruses.

The penalty for dealing in ivory items, or for making it possible for others to buy or sell ivory, is a fine of up to £250,000 and up to five years in prison.

Ivory Exceptions to Ivory Laws

However, there are a few exceptions to this law. If you do want to buy or sell ivory items, you need to apply for an exemption. You also need to apply for an exemption if you want to display ivory items in a public gallery, or if you want to export ivory items to an overseas location.

Do You Need To Apply For An Exemption for Inherited Ivory?

It all depends on what you intend to do with the inherited ivory.

If you inherit an ivory item, and you simply wish to keep it in your personal collection, then you do not need to apply for an exemption. You are also free to leave the item to beneficiaries in your will, and to lend the item to others so long as the transaction does not involve any exchange of money or other goods.

You can also give ivory items away as gifts, so long as you are not donating them for display in public. If you wish to donate ivory items to a museum or a gallery, then special rules will apply.

What If I Want To Sell My Inherited Ivory?

As we mentioned above, if you inherit ivory and you want to sell it, then you may  have to apply for an exemption.

Remember that, in UK law, it is also illegal to make it possible for others to buy or sell ivory. This means that you still need to apply for an exemption even if you wish to simply donate the ivory item to an antiques store or a second-hand shop.

For some items, you will be able to apply for a standard exemption, which costs £20 per item. Ivory items eligible for standard exemptions include:

  • Items you are selling or lending to museums.
  • Portrait miniatures made before 1918.
  • Any item made before 3 March 1947 containing less than 10% of integral ivory by volume.
  • Any musical instrument made before 1975 containing no more than 20% of ivory by volume.

If you wish to sell any ivory item that does not meet this criteria, you will first have to apply for an exemption certificate. This costs £250, and the process includes an assessment by the Animal and Plant Health Agency to determine the item’s “artistic, cultural, or historic value”.

As you can see, the type of exemption you need will depend on the item’s age, and on how much ivory it contains. You may need to consult an expert for an appraisal in order to fully understand how to manage your inherited ivory.

How To Apply For An Ivory Exemption

First, use the government’s online ivory eligibility checker to determine what sort of exemption you will need, whether this is a standard exemption or an exemption certificate.

Once you know what kind of exemption you need, you can apply online.

Getting The Right Protection For Your Inherited Ivory

Despite the strict laws, ivory items can still be highly valuable. As a result, whether you want to keep your inherited ivory, donate it to others, or sell it, you should take steps to properly value your items, and to keep them safe.

To begin with, take the time to document every ivory item you inherit. Take photos, and record as many details about the item as you can. Also try to find out as much as possible about the item’s provenance – when it was made, how it was obtained etc.

Next, consult an expert to help you accurately determine the age and value of every ivory item you inherit. This will also help you decide what kind of exemption you need, should you wish to sell or donate the ivory.

Once you have an accurate value for every ivory item you inherit, if the valuation deems them to be of high value, consider discussing your requirements with a  specialist high net worth insurance broker who can help you arrange suitable cover, subject to policy terms, conditions and exclusions. And remember that an item’s value can fluctuate over time. So, if you wish to keep the ivory items for yourself, it is a good idea to get periodic fresh appraisals in order to ensure that your sum insured and specified item values remain adequate following future valuations

Talk To James Hallam About Your High Net Worth Insurance Needs

James Hallam is an independent Lloyd’s broker with a dedicated team of experienced insurance professionals who are committed to getting you the cover you need.

Talk to us, and we can help to ensure you have suitable cover to protect your home and contents, including any ivory or other high value items in your home.

Get in touch for a free quote today.
 

Public Liability and Employer’s Liability – What’s The Difference?

Public Liability and Employer’s Liability – What’s The Difference? 1000 667 James Hallam

Liability insurance can protect your business from a range of costly claims. Many different types of liability insurance are available, but you are required by law to have certain forms of liability cover in place.

In this post we will take a look at two types of liability cover: Public liability insurance, and Employer’s Liability insurance. We will outline what each type of policy covers, before exploring the key differences between the two.

What is Public Liability Insurance?

If a third party  has an accident or injury on your business premises – whether they are a client, a customer, a visitor, a delivery driver, or a contractor – then they may make a claim against you.

In this case, public liability insurance may cover legal defence costs  that may arise, along with any compensation payments that may be due subject to the policy terms and conditions.

Public liability insurance can also respond to claims arising from accidental damage to third party  property. So, if you accidentally spill a cup of coffee over a visiting client’s laptop, for example, your public liability insurance may  cover  required repairs or replacements where cover applies.

Many public liability insurance policies will usually cover you for incidents that happen off-site, too, for example iff you accidentally damage a client’s property during a site visit subject to the policy terms & conditions.

What is Employer’s Liability Insurance?

While Public Liability insurance covers injuries or damages experienced by third parties, employer’s liability insurance covers accidents, injuries, or illnesses your employees may sustain while working for you.

The cover will also extend to other indivdiuals  for whom your business is responsible, such as  volunteers and trainees, subject to the policy terms and conditions.

An employer’s liability insurance policy will usually continue to provide cover for employees who no longer work for you. For example, your policy may cover your legal fees and compensation payments should some ex-employees develop long-term health conditions some years after leaving your business.

What is the Difference Between Public Liability and Employer’s Liability Insurance?

Both Public Liability insurance and Employer’s Liability insurance cover you for accidental damage and injury. But there are some key differences between the two policies:

  • Public liability insurance – This will cover your legal liability for accidental injury to third parties or damage to third party property arising from your business activities It should typically cover you for incidents that occur at your premises or whilst carrying our business activities elsewhere.
  • Employer’s liability insurance – This covers your legal liability for injury, illness or disease sustained by employees arising out of and in the course of their employment. Depending on the policy wording, cover may also extend to other indivduals for whom your business owes a duty of care, such as interns, volunteers, trainees, and temps.

What Insurance Does Your Business Need By Law?

Employers Liability Insurnace: If you employ any staff, you may be  legally required to have Employer’s Liability insurance. The Health and Safety Executive (HSE) has certain enforcement powers, and may impose certain penalties if a business fails to comply with its Employer’s Liability insurance obligations. This can include:

  • A fine of £2,500 per day, for every day your business operates without the required cover.
  • An additional fine of £1,000 if you are unable to present a valid liability insurance certificate when requested.

The HSE can impose these penalties regardless of whether or not an incident has taken place.

Public Liability Insurance: There is generally no legal requirement to purchase Public Liability insurance.  However, it is an important form of protection for two key reasons:

  1. Without Public Liability cover your business could be liable for legal defence costs , compensation awards and other associated expenses arising from claims for injury to third parties or damage to third party  property resulting from your business activities.
  2. Certain clients, local authorities and other commercial organisations may require you to have a Public Liability policy in place as part of a contractual agreement. They may even require you to supply a certificate of public liability cover before they agree to work with you.

Protect Your Business With Insurance Arranaged by  James Hallam

James Hallam is an independent Lloyd’s broker with a dedicated team of experienced insurance professionals who are committed to protecting your business.

We can help you arrange  the liability insurance cover your business needs, providing protection against  potential claims, whether they come from employees, customers, or other third parties , subject to policy terms, conditions and exclusions.

Get in touch for a free quote today.
 

Using AI For Travel Planning: Who is Liable If Things Go Wrong?

Using AI For Travel Planning: Who is Liable If Things Go Wrong? 1000 667 James Hallam

In recent years, a number of  travel agents and tour operators have started using AI tools to streamline certain processes. At the same time, some travellers have started trusting AI to plan certain aspects of their trips, bypassing tour operators and other travel specialists entirely.

The problem is that AI can make mistakes. And when people use AI for travel planning, who is liable if things go wrong?

When Using AI For Travel Advice That Goes Wrong

In July 2026, a couple of hikers were walking the Polish Tatra Mountains, when they asked ChatGPT for a shortcut. The AI sent them on a route that proved to be impassible, and they eventually needed a helicopter to rescue them.

Similarly, in 2025 some Canadian hikers decided to ignore some severe weather warning, and instead followed a route plotted by ChatGPT. They too needed help from a search and rescue team.

There have also been instances of AI recommending locations that simply do not exist. For example, some travellers were directed to the “Sacred Canyon of Humantay” (sic) in Peru when they asked ChatGPT for areas of local interest.

Any traveller heading to a non-existent location would be disappointed at best. But through heading to remote areas, they could also find themselves lost, stranded, and at risk from certain hazardous conditions.

How Is The Travel Industry Using AI?

Some travel agents and tour operators are using AI to:

  • plan trips
  • anticipate upcoming trends
  • tailor experiences for their customers
  • offer real-time round the clock customer service

Read our full guide to some of the ways travel agents and tour operators are using AI.

The situations we outlined above occurred when travellers either outright ignored official travel advice, or else turned to AI instead of professional travel guides. Yet it is easy to imagine situations where AI could cause headaches for travel agents, too.

As we have seen, AI can get things wrong. As well as sending travellers to destinations that may not exist, it might advise routes that are impractical or outright dangerous, or book connections that may  be impossible for anyone to make. AI could also recommend unsuitable accommodation, such as somewhere that is inaccessible for a customer with mobility issues.

If a travel agent or tour operator is using AI to plan trips and tailor packages, who would be liable for any losses or expenses should the AI make mistakes? Would it be the AI that made the mistake in the first place, or the tour operator that sold the trip to the traveller?

Using AI For Travel Planning: Who is Liable If Things Go Wrong?

In July 2026, the UK Jurisdiction Taskforce published a Legal Statement on Liability for AI Harms. This statement is not a treatise. It does not outline any proposals for legal reform, and it does not constitute legal advice. Rather, it aims to establish some guidance on which parties would be liable for any harms arising from AI use.

The statement suggests that the law should view AI liability in terms of negligence. If a business owes a duty of care to a customer, then they will be liable for any losses that arise should they fail to meet the necessary standards of care.

The statement also explores the issue of vicarious liability. While a business cannot be held vicariously liable for mistakes an AI system makes, it can be held vicariously liable for any losses that arise from an employee acting wrongfully while using AI.

In short, this implies that travel agents or tour operators would be held liable if something goes wrong when they use AI to plan a trip. While the AI itself made the mistake, if the travel agent or tour operator did not do the necessary work to check the AI’s recommendations, then they could be held liable for any losses or other incidents that arise as a result.

How To Reduce The Risks of AI Liability Claims

If you are using AI systems to plan trips or design experiences for customers, there are a few ways you can protect your business and your customers from potential issues:

  • Never take the AI’s recommendations for granted. Never present anything to customers without first applying sufficient human oversight. Be sure to check the AI’s recommendations for accuracy and practicality.
  • Train your staff. Ensure that any member of staff that uses AI modules is properly trained to do so. Make sure everyone understands that AI can and does make mistakes, and invest in due diligence training where necessary.
  • Revisit your terms and conditions. Make sure your contracts with your customers reflect the inherent risks of using AI to plan journeys. You might also specify that, if travellers wish to make any changes to the trips you plan for them, then they do so at their own risk. This could cover your liability should any customers choose to ignore your advice and turn to AI for recommendations instead.

Are You Covered For AI Liability?

At James Hallam, we specialise in providing bespoke insurance packages to UK travel businesses. We work closely with ABTA, AITO, ABTOT, Advantage, ABTOI, PTS and ITT.

These specialist travel bodies are actively exploring the potential of AI for transforming the world of travel, which includes the potential risks.

So, if you want to transform your business operations with advanced AI tools, these travel bodies  will certainly be able to help. And at the same time, we can help you arrange the appropriate  insurance cover to help protect you  and your customers interests should the unexpected occur, subject to policy terms, conditions and exclusions..

Find out how we can help you today.

Health and Safety Induction Checklist for New Employees

Health and Safety Induction Checklist for New Employees 1000 667 James Hallam

As part of their onboarding and induction process, all new employees should receive a thorough introduction to your company’s health and safety policies and procedures.

In this post we will outline what you should include in your health and safety induction for new employees, so you can cover all bases and stay compliant with the relevant health and safety legislation.

Why Health and Safety Inductions Matter

The Health and Safety Executive (HSE) makes it clear that employers have a legal responsibility to ensure that the workplace is safe and healthy for everyone.

One of your responsibilities under the Management of Health and Safety at Work Regulations 1999 is to take action to eliminate workplace hazards, or to control the risks.

Health and safety inductions are an essential component of this risk management process. Through introducing new employees to your various health and safety policies and procedures, you can equip them with the knowledge and skills they need to keep themselves and others safe.

You can also ensure that, in the event of an emergency, everyone knows what to do, where to go, and to whom they should report.

What to Include in Your Health and Safety Induction Checklist for New Employees

These are the key elements that all workplaces should include in their health and safety induction checklists:

  1. An introduction to the job, including instructions on how to carry out the role safely, and details of all necessary training requirements, welfare provisions, and emergency contacts.
  2. Emergency arrangements, including the fire evacuation procedure, accident and incident reporting procedures, and details of the first aid provisions.
  3. Manual handling procedures, including assessments (is the object too heavy to lift?) and the use of lifting aids.
  4. Hazard awareness: What sort of risks should the employee look out for, and how should they report any risks they spot?
  5. Housekeeping: What role can the employee play in helping to keep the working environment safe, clean, and free of clutter?

Industry Specific Requirements for New Employee Inductions

Beyond the key elements, you may have to introduce additional elements to your health and safety induction checklist depending on the specific risks in your workplace:

  1. Equipment, tools, and machinery: Safe use, training requirements, and awareness of health and safety risks.
  2. Personal Protective Equipment (PPE) policies, including the correct use and storage, and the procedure for reporting faults.
  3. Hazardous substance policies: Including risk assessments, and instructions on safe storage, handling, and disposal. Depending on the industry you work in, you may also require your new employees to receive certain vaccines before they can work with the hazardous materials you manage.

Health and Safety Induction Checklist Template

You can download a free health and safety induction checklist template from the Government’s website.

This particular checklist includes a box to tick to confirm that you have booked the new employee’s mandatory health, safety, and wellbeing awareness training. It also includes some useful guidance notes to explain various aspects of the checklist items.

You can also read our guide to writing a health and safety checklist for the office, and our guide to writing a health and safety checklist for warehouses.

Health and Safety Should be an Ongoing Priority

Running through a health and safety induction checklist will literally be a box-ticking exercise for both the employer and the employee. But this does not mean that you should treat it as a mindless “one-and-done” task.

You have an ongoing duty of care to all of your employees, and health and safety awareness and training should not stop at induction:

  • Make your health and safety policy easily accessible to all employees. This means writing it in clear language, and storing it in a place where any employee can reference it at any time, such as on the company intranet.
  • Provide routine refresher training, so that employees never lose sight of the essentials. Ongoing health and safety training can also help you to protect your employees and your business against new and evolving threats, such as the growing risk of cybercrime.
  • Place signage around the workplace to highlight key risks (such as steps, edges, and loading areas), and to remind employees of their responsibilities.
  • Thoroughly investigate any incidents to help you identify measures that could help prevent future risks.

Get The Right Cover For Your Business

If your business employs staff, Employers Liability Insurance is typically a legal requirement. This can provide protection for your  employees against  injury or illness claims that might take place in the workplace. Beyond this, you may want to consider insurance protection  for third party liabilities, property damage, business interruption  theft, and cybercrime depending on your circumstances.

James Hallam is an independent Lloyd’s broker with a dedicated team of insurance professionals who care about protecting your business. We can help you access  insurance cover designed against a range of workplace risks you may face.

Learn more about our specialist SME insurance services.

What is Tramping and Trunking in HGVs?

What is Tramping and Trunking in HGVs? 1000 667 James Hallam

In the haulage industry, the terms “tramping” and “trunking” refer to two different strategies for managing routes and contracts. In this post we will outline the key differences between tramping and trunking, along with the possible risks and rewards of each.

What is Tramping?

Tramping refers to the practice of transporting goods over long distances and long periods of time.

The long distances involved in tramping means that drivers are required to spend extended periods on the road away from home. A journey to the destination and back could take a number of days, during which time the driver may effectively live in their cab. They will drive for a limited number of hours before sleeping in their cab at the end of the day.

Benefits of Tramping

  • Long distance haulage contracts may be highly lucrative for haulage firms.
  • Tramping jobs tend to pay better than other driving roles.
  • The work can be more varied. The driver may be required to physically move the cargo at pick-up or drop-off, for example.

Downsides of Tramping

  • Tramping contracts typically involve larger quantities of goods, so they will also involve larger and heavier trucks. These can be more expensive to acquire, run, and insure.
  • Not all drivers enjoy being away from home for long periods, and some may struggle to manage their tachograph while spending days on the road.
  • European tramping contracts may require drivers to acquire certain travelling documents, while also familiarising themselves with overseas driving laws and customs.
  • Tramping may also require driving to remote locations on unfamiliar rural roads, which may make accidents more likely.

What is Trunking?

Trunking involves shorter distances and regular routes. Indeed, a driver may take the same route every day, and they will usually be able to return home once the delivery, or their shift, is complete.

Night trunking is also common, and some drivers may prefer this, as it would mean travelling on less busy roads, with less chance of traffic jams and other delays.

Benefits of Trunking

  • As drivers can return home at the end of each shift, trunking arrangements can lead to a much better work/life balance than tramping arrangements.
  • As drivers will stick to familiar roads, including motorways and dual carriageways, there may be less risk of accidents.
  • Haulage firms will likely find a trunking fleet much easier to manage than a tramping fleet, as all the vehicles and drivers will usually stay within a relatively small area.

Downsides of Trunking

  • In order to avoid traffic and meet strict delivery times, trunking contracts often rely on night shifts. Not all drivers appreciate unsociable hours, and driving at night could make driver fatigue more likely.
  • Trunking contracts may be more reliable and easier to manage, but they will probably not pay as much as long-distance or overseas tramping contracts.

Tramping vs. Trunking – Key Considerations For Fleet Managers

  • Compliance – Drivers are restricted to a set number of driving hours each day, all of which they must meticulously record on their tachographs. This can be relatively easy to manage and enforce with trunking arrangements, as fleet managers can set shifts in line with driving hours. But it will be up to the driver to manage their hours and their tachograph throughout a long distance tramping arrangement.
  • Fleet Management – Managing your fleet can be relatively straightforward when all of your vehicles and drivers stick to familiar routes that are no more than a day’s driving distance from your depot. But it can be more challenging to keep tabs on your fleet when your drivers spend days away from home, especially when they travel overseas.
  • Driver Welfare – Both tramping and trunking can place huge demands on drivers, particularly if the contract involves night driving. Beyond simple compliance, you will have to establish a means of helping drivers maximise their work/life balance while understanding and fighting the risks of driver fatigue.
  • Insurance – Tramping arrangements will generally require more extensive insurance coverage, to account for the long periods spent on unfamiliar roads, the potential for arranging for repairs and recovery overseas, and the involvement of heavier and more powerful trucks and trailers.

Tramping or Trunking, We Have You Covered

James Hallam is an independent Lloyd’s broker with a dedicated team of insurance professionals who care about protecting you and your fleet.

Whether you go for tramping or trunking contracts, we can help you ensure you have access to  cover that meets your needs  to protect your drivers, your vehicles, and your operations against potential risks your fleet faces.

Learn more about our HGV insurance services.

What is Insurance Premium Tax?

What is Insurance Premium Tax? 1000 643 James Hallam

Insurance premium tax (IPT) is a tax the UK Government applies to certain insurance products.

In this post we will explain how IPT works, including the types of insurance policies to which it applies.

What is Insurance Premium Tax?

The UK Government applies IPT to general insurance premiums. Rather than seeing IPT as a separate payment, it is built directly into the premiums you pay for certain forms of cover. Your insurer collects the tax in this way before passing it on to HMRC.

Insurance Premium Tax vs. VAT

Perhaps the best way to think of IPT is as a form of VAT that specifically applies to certain insurance products. When you buy applicable products or services, you will automatically pay the VAT as part of the overall cost. Similarly, when you pay your insurance premium, some of the payment will cover your insurance costs, while the rest will go to the UK Government as tax.

But while both VAT and IPT are indirect taxes collected by HMRC, there are some key differences between the two:

  1. Insurance products are actually exempt from VAT. The Government first introduced IPT in order to collect taxes on transactions to which VAT did not apply.
  2. The current VAT rate is 20%, which HMRC applies to most goods and services. But there are two IPT rates – a standard rate, and a higher rate.
  3. While businesses can reclaim VAT on their tax returns, they generally cannot reclaim IPT.

Insurance Premium Tax Rates

HMRC applies two different IPT rates. At the time of writing, they are:

  • Standard Rate – 12%
  • Higher Rate – 20%

The standard rate applies to some of the most common insurance products, such as home insurance, pet insurance, and car insurance.

Meanwhile, the higher rate generally applies to insurance products that are sold alongside other products or services – such as when airlines sell travel insurance alongside a flight, or when an electronics manufacturer allows customers to purchase cover for their appliances.

You can read a full breakdown of the current IPT rates.

Insurance Premium Tax Exemptions

Certain insurance products are exempt from IPT, including:

  • Cover for commercial aircraft and marine vessels.
  • Cover for commercial goods during international transit.
  • Most long-term insurance products, including life insurance and permanent health insurance policies.
  • Reinsurance (i.e. cover that insurance firms take out to cover risks relating to the policies they underwrite).
  • Cover for overseas risks – though these policies may instead be liable for taxes imposed by other countries.

You can read a full guide to IPT exemptions.

Who Pays Insurance Premium Tax?

Insurers apply IPT directly to their premiums, which means that they effectively collect the tax payments from their customers on behalf of HMRC. IPT is always paid directly by the policyholder, whether this is an individual or a business.

Can You Claim Back Insurance Premium Tax?

While businesses can claim back VAT, they generally cannot claim back IPT.

Even if your business is VAT-registered, you cannot list IPT as input tax on your VAT return. It is instead treated as an entirely separate tax.

As we mentioned above, certain insurance products are exempt from IPT, and you may be able to reclaim payments if you believe you were charged incorrectly. But this is a matter you will have to settle directly with your insurer. You will not be able to reclaim the payments from HMRC.

How Does Insurance Premium Tax Affect the Cost of Insurance?

The current IPT rates have been in place since 2017, and the rates have risen six times since the tax was first introduced in 1994. If the rate changes at all in the coming years, it will most likely be in the form of a further increase.

IPT means higher insurance premiums for policyholders. Depending on the type of insurance, you will either have to pay 12% or 20%, which will be applied directly to your premiums. This means there is simply no way to avoid it and, as we have seen, businesses cannot reclaim IPT either.

But if you do want to make savings on the cost of your business insurance, a good place to start is through working with an insurance broker. An experienced broker can advise you on key risk management procedures, and show you how to evidence these measures to your insurer in order to potentially save on premiums. Your broker can also help you access a tailored insurance package that will provide insurance solutions for the risks you  face.

Get The Right Cover For Your Business

James Hallam is an independent Lloyd’s broker with a dedicated team of insurance professionals who care about protecting your business. As well as offering cost-effective risk management advice, we can also help you source the  cover you need for your business.

Learn more about our specialist SME insurance services.


What Insurance Do Driving Instructors Need?

What Insurance Do Driving Instructors Need? 1000 668 James Hallam

Teaching people to drive is an inherently risky business. Beyond L-plates and a dual control car, you will need extensive insurance cover to protect you, your learner, your vehicle, and other road users.

If you work for a driving school, then your employer will likely sort out the necessary insurance on your behalf. But if you are a self-employed driving instructor, then you will be wholly responsible for arranging your own cover.

In this post we will outline the key insurance requirements for driving instructors, including the cover you need by law.

Can Driving Instructors Use Standard Car Insurance Policies?

An ordinary car insurance policy will not provide this cover, not even if you add “business use” to the policy. Only a dedicated driving tuition motor insurance policy will give you the specialist cover you need.

Legal Requirements For Driving Instructor Insurance

You have a legal requirement to get driving tuition motor insurance. This will cover you for the specific risks associated with driving a dual control car, and with providing paid tuition services.

Also, if you hire any employees, such as someone to provide admin support, then you have a legal duty to get employer’s liability insurance. This can provide protection against injury or illness claims that may take place in the workplace. You need to get this cover even if you hire one of your relatives, and even if they only work for you for a few hours a week.

Strongly Recommended Insurance Extras For Driving Instructors

Additional cover options unlikely to be covered as standard within your driving instructor’s insurance could include:

  • Public Liability Cover – This can be a coverage gap for driving instructors. Driving tuition motor insurance can cover your liabilities during your driving lessons. Public liability cover, on the other hand, can cover accidents, injuries, and damages to personal property that occur outside of your driving lessons.
  • Professional Indemnity Cover – If you deliver training to fleets, or if you are responsible for training other driving instructors, then professional indemnity insurance can cover legal fees and compensation payments following claims of professional negligence.
  • Contents Cover – This can cover the loss, damage, or theft of your belongings that you take outside your home, such as your smartphone, your laptop, and any other equipment you use to run your business.
  • Personal Accident Cover – If you are unable to provide driving lessons, then your income will stop immediately. Personal accident insurance can provide a lump sum in the event of an injury, such as loss of sight, limbs or permanent total disablement. It can also provide a weekly benefit for temporary disablement that prevents you from carrying out your work. (Personal Accident Cover is different to Accident, Sickness and Unemployment Cover, which provides a monthly benefit to cover your overheads.)

All covers included within the policy and optional extras are subject to policy terms and conditions, limits and endorsements.

Common Pitfalls with Driving Instructor Insurance

Above we mentioned that public liability can be a cover gap for driving instructors. But it is also a mistake to assume that your public liability insurance will cover you for anything that occurs outside of your driving lessons.

The same is true for the other additional extra covers, such as Professional Indemnity Insurance, Contents and Personal Accident. Your insurance policy will likely list a number of exclusions to the cover. Take the time to read your policy wording, along with the exclusions, so as to fully understand exactly what you are and are not covered for.

Also be aware that your work as a driving instructor may compromise certain other insurance policies you hold. For example, you may have to inform your home insurance provider if you are running your driving instructor business from home, and you may need to add business use to your car insurance policy in addition to getting a dedicated driving tuition motor insurance policy.

How Much is Insurance For Driving Instructors?

The amount you pay for your policy will depend on a number of factors:

  • The type of car you drive – Advanced and high performance models will cost more to insure, due to the increased risk of theft, and the potential high cost of repairs following an accident.
  • The type of training you provide – If you train fleet drivers or other driving instructors, then you will likely have to pay more for insurance owing to the need for professional indemnity cover.
  • The level of cover you choose – You may be able to specify the level of public liability or personal accident cover you receive, for example. The higher your cover limit, the more you should expect to pay.

How James Hallam Can Help You Get The Cover You Need as a Driving Instructor

James Hallam is an independent Lloyd’s broker with a dedicated team of insurance professionals who care about protecting you and your business.

We can advise you on the risks you may face as a driving instructor, and we can help you access a tailored policy that meets your cover needs. We can also help you ensure that your work as a driving instructor does not compromise any other insurance policies you hold.

Learn more about our specialist insurance services.

Does Home Insurance Cover Storm Damage?

Does Home Insurance Cover Storm Damage? 1000 666 James Hallam

The Met Office is predicting strong storms in the UK throughout the winter, with anticipated peaks in November and December 2026. If you are a homeowner, you might therefore be wondering whether your home insurance will cover you for storm damage.

In this post we will explain what insurers mean when they refer to “storm damage”, and explore what sort of cover usually comes as standard in home insurance policies.

What is the Definition of Storm Damage?

Storm damage is any damage that occurs to your property as a result of stormy weather, including high winds and heavy rain or snow.

Different insurers may have their own definitions of storm damage. But generally speaking, when they refer to “storm damage”, they are referring to:

  • Roof damage from strong winds.
  • Damage from debris, including fallen trees and power lines.
  • Broken windows or other damage as a result of hail.
  • Flooding as a result of overwhelmed drains.
  • Fire or electrical disruptions as a result of a lightning strike.
  • Structural damage as a result of snow.

What About Long-Term Storm Damage?

Sometimes, the damage may be more long-term, and not be as a direct result of the storm. For example, high winds could blow some tiles from your roof, compromising its integrity. When it rains again, water may enter your property, which over time could lead to damaged ceilings, electrical damage, and mould growth.

For cover to be applicable and for a claim to be valid, the damage needs to be easily linked back to the storm.  Gradual deterioration or maintenance issues that have built up over a period of time are not covered by insurance.

Does Home Insurance Cover Storm Damage?

Yes, most home insurance policies will cover storm damage as standard. However, there may be some exceptions to the cover, so be sure to read the policy details to get a full idea of what exactly is and is not covered.

It is also important to differentiate between buildings insurance and contents insurance. Your buildings insurance will cover most types of storm damage to your home, whereas your contents insurance will cover any items of furniture or other belongings that may get lost, destroyed, or damaged as a result of a storm.

What Storm Damage is Not Covered By Home Insurance?

There may be some exceptions or limits to your storm damage cover, including:

  • Storm definition – Some insurers will specify the exact conditions that constitute a storm. They may specify, for example, that wind speeds must exceed 55 mph in order for a spate of bad weather to qualify as a storm. If the weather does not meet this threshold, then it may not trigger your home insurance storm cover.
  • Maintenance issues – Your home insurance policy will not cover you for general wear and tear. For example, if elements of your home, such as your roof or your windows, were already in a poor condition, then your insurance will probably not cover you for any further damage caused by a storm. Nor will it cover you for water damage from overflowing gutters if your gutters were blocked to begin with.
  • Gradual damage – If a long period of relatively high winds or wet weather leads to slow and gradual deterioration, then it is very unlikely that you will be able to claim for storm damage. Your insurer will probably point out that you could have taken steps to secure your property against an extended spell of bad weather.
  • Flood damage – Storms can often contribute to flooding, but your insurer may not consider damage from flooding as “storm damage”. You may need dedicated flood insurance to cover any issues arising from water entry.
  • The garden – Your home insurance policy may not cover you for storm damage to your fences, gates, or garden furniture, and it may not extend to outdoor structures such as sheds, greenhouses, and decking.

Protecting Your Home Against Storm Damage

You will find a full guide to protecting your home against storm damage on our site. This includes steps you can take to manage or mitigate any potential storm damage should the Met Office issue a storm warning.

Beyond this, there are certain things you can do to help reduce the impact of storm damage, while making it more likely that you can make a successful claim on your home insurance policy:

  • Stay on top of your home maintenance, so as to ensure that everything is as secure and watertight as possible in case of severe weather.
  • Following a storm, thoroughly inspect your home inside and out. Document any damage you find, and take pictures just in case you ever need to provide any evidence.
  • Act quickly to repair any storm damage, no matter how mild. This will help to prevent any further issues from developing, for which you may not be able to claim.

We Can Help You Protect Your Home From Storm Damage and Other Risks

James Hallam is an independent Lloyd’s broker with extensive experience in helping individuals protect their assets. We can help you find suitable home insurance  cover to protect your property against  storm damage, and other risks.

Get in touch for a free quote today.
ESG in Shipping: Reporting and Requirements

ESG in Shipping: Reporting and Requirements 1000 560 James Hallam

ESG has become a major priority for the global shipping industry. While ESG strategies used to be largely voluntary, they are now a core requirement for most insurers and regulators.

In this post we will outline the key elements of an ESG strategy for shipping, along with your reporting requirements.

What is ESG, and What Does It Mean for Shipping?

ESG stands for Environmental, Social, and Governance. When we talk about ESG in shipping, we are referring to a number of measures shipping businesses can take to address the environmental and social impacts of their operations, along with the governance strategies that could contribute to more efficient practices.

Why ESG Matters in the Shipping Industry

According to the International Maritime Organization (IMO), international shipping accounts for around 2% of all global emissions.  A report published by the International Council on Clean Transportation (ICCT) found that global shipping generated approximately 900 million tonnes of CO₂ emissions in 2023. Container ships were the largest contributor, responsible for around 20% of emissions, followed by bulk carriers (16%) and oil tankers (14%). Together, these three vessel types accounted for approximately half of shipping-related CO₂ emissions, highlighting the importance of decarbonisation across the commercial shipping fleet.

Yet the global shipping industry has environmental impacts beyond these emissions. Ships could introduce invasive species to new habitats. They could pollute waterways, and the underwater noise they produce can disturb marine habitats.

Insurers and regulators set ESG requirements as a means of managing and mitigating the damage vessels can cause to the atmosphere, along with waterways and ecosystems.

Who Is Responsible For ESG In Shipping?

ESG is a shared responsibility across the entire shipping industry. Ship owners and operators may be responsible for ensuring their ship meets applicable environmental standards, and they may also be responsible for safeguarding their crew.

Meanwhile, directors and other stakeholders will be better positioned to ensure compliance when it comes to management, recruitment, financial reporting, and other aspects of governance.

Key ESG Requirements in Shipping

Environmental requirements:

  • Reducing harmful emissions while addressing marine pollution
  • Increasing energy efficiency both onboard and onshore
  • Promoting recycling and biodiversity wherever possible

Social requirements:

  • Prioritising crew wellbeing with training and support
  • Choosing supply chains that comply with labour standards while reducing potential abuse
  • Treating workplace equality as standard

Governance requirements:

  • Accuracy and transparency in all reporting
  • Introducing anti-corruption measures
  • Making managers and decision-makers accountable for risk-management and performance outcomes

ESG Reporting and Requirements in Shipping

You can read our full guide to the environmental regulations in shipping, which outlines many of the reporting requirements, including:

Beyond this, The International Chamber of Shipping suggests a number of ESG reporting frameworks and standards, including:

There is no legal requirement for marine businesses to adopt any of these ESG reporting standards. But the International Chamber of Shipping acknowledges that these frameworks are internationally recognised, and can thus provide detailed, measurable, and specific targets and reporting techniques for businesses across the shipping industry.

You can read the full International Chamber of Shipping guide to ESG reporting frameworks and standards. You can also access their detailed guide to designing and implementing an ESG reporting system.

The Consequences of Poor ESG Performance

Prioritising ESG can bring a number of benefits. If you can accurately report your performance outcomes, you may have better access to financing and credit options. You will improve your operational efficiency, and through evidencing your risk management you could even make savings on the cost of marine insurance cover.

Yet beyond high emissions and inefficiency, poor ESG performance can bring a range of consequences:

  • Regulatory Action – Regulators such as the IMO have certain enforcement powers. For example, if your ship gets a poor CII rating, the IMO will require you to submit a Ship Energy Management Plan to outline your intended decarbonisation roadmap.
  • Reputational Damage – The IMO encourages administrations, port authorities, and other stakeholders to provide incentives to ships with good CII ratings. This implies that any ships with poor ESG performance can expect to get penalised. Lenders and investors may also be less willing to work with you if you cannot evidence your compliance.
  • Insurance Implications – Insurers increasingly require marine businesses to evidence their risk management procedures, along with certain other ESG metrics. If you cannot provide the information they request, you may struggle to get the insurance you need, which could create contractual issues with other parties involved in your operations.

How James Hallam Can Support You in Ensuring Good ESG Performance

Everard Insurance Brokers are the specialist marine trading division of James Hallam Limited who are accredited Lloyd’s insurance brokers.

We are just as committed to ESG as you are, and we can support you in your journey towards good ESG performance. For example, we can show you how to evidence your risk management procedures in order to demonstrate your commitment to safe and efficient operations both onshore and at sea. We can also help you access a cost-effective insurance package to get you the specialist cover you need that will best meet your insurance requirements

Find out more about our specialist marine insurance and risk management services.

What Does The Super El Niño Mean For Travel Destinations?

What Does The Super El Niño Mean For Travel Destinations? 1000 667 James Hallam

A Super El Niño event means that the average sea surface temperatures in certain parts of the Pacific Ocean rise by 2°C or more. Such an event will bring a significant climactic impact, which could severely disrupt the global travel industry.

Scientists have suggested that the world might see a Super El Niño event in the next couple of years. In this post we will explore what the Super El Niño could mean for travel destinations, with some tips on how travel agents and tour operators might prepare.

The Potential Impact of Super El Niño

Rising sea temperatures can lead to a host of climate impacts, including:

  • Severe flooding
  • High temperatures
  • Drought, and an increased risk of wildfires and cyclones
  • Food shortages
  • Disruption to water supplies

How Will a Super El Niño Affect the UK?

The impacts of a Super El Niño will vary considerably at different times of the year, and in different parts of the world. In the UK, for example, an El Niño event usually leads to warmer summers and colder winters.

Which Countries Are Most Affected by the Super El Niño?

A Super El Niño event will have the biggest impact on countries that are close to the particularly warm areas of the Pacific Ocean. Some of these countries may see unusually hot and dry conditions, while others may see extremely wet conditions, with an increased risk of flooding.

Many of these countries are popular travel destinations in the winter months. Below we will take a closer look at some of the areas that travellers may choose to avoid outright in the coming years, so as not to face severe disruption and other risks.

What Does The Super El Niño Mean For Travel Destinations?

The following travel destinations are likely to be particularly affected:

  • California – Heavy rains can lead to flooding, and even mudslides, which could result in road closures and other disruption.
  • Peru and Ecuador – As these countries are the closest to the excessively warm areas of the Pacific Ocean, they could see the biggest impact from a Super El Niño event. Both countries could see extreme rainfalls and a critical risk of flooding.
  • Australia – Queensland and the wider northeast area of Australia could see soaring temperatures with a potential for drought.
  • Southeast Asia – Countries such as Indonesia and Thailand may also experience drought conditions, with a risk of wildfire and water shortages.

How Should Travel Agents and Tour Operators Prepare For a Super El Niño Event?

Travel agents and tour operators should take steps to manage the risks of a Super El Niño event, while ensuring that their customers are aware that high Pacific temperatures can lead to significant travel disruption and other risks.

Look For Alternative Destinations

Some areas may actually benefit from a Super El Niño event. As we mentioned above, it usually means hotter summers for the UK, so many travellers may simply choose to stay closer to home.

Super El Niño is unlikely to affect snowfall in The Alps, so any travel agents or tour operators who usually sell packages to North American ski resorts may choose to focus on European resorts instead.

Also, the effects of Super El Niño can vary wildly across individual countries, too. Travel agents and tour operators may not have to look very far when seeking alternative travel destinations. For example, while drought may hit southern Thailand, northern Thailand may experience relatively cooler temperatures.

How to Stay On Top Of Developments And Keep Travellers Informed

The UK Government routinely provides travel advice for over 200 overseas countries or territories. During a Super El Niño event, this advice could cover the risks of drought, flooding, wildfires, and other climate impacts.

Find a way to stay on top of the latest travel advice, and take steps to keep your customers updated on any developments. Aim to communicate frequently and consistently, and try to establish an expectation that situations can change quickly.

Read our full guide to communicating travel advice to customers.

Contingency Planning and Insurance

Risk management and contingency planning can give you a clear course of action to follow in the event of an emergency situation, whether this is a simple cancelled flight, or mass disruption following a flash flood or a wildfire.

Outline the immediate steps you would take in order to support your customers and ensure they can stay safe. For example, how would you stay in touch with overseas travellers in situations where established lines of communication may be affected?

Also be sure to advise your customers on the cover they might expect from their travel insurance, along with the limits to the cover. For example, travel cover may not apply if a customer ignores the travel advise and intentionally travels to a high-risk area.

Specialist Insurance Services For Travel Agents and Tour Operators

At James Hallam we have provided dedicated insurance services for travel agents and tour operators for over 35 years. In this time, we have provided advice from our experienced team and cover throughout numerous Super El Niño events.

Find out more about our bespoke insurance services for travel agents and tour operators or call us on 0203 967 1923 or email david.mcgregor@jameshallam.co.uk.