Insights

How To Protect Your Business From Extreme Weather Events

How To Protect Your Business From Extreme Weather Events 1000 781 James Hallam

In recent years, the UK has faced heatwaves, floods, and a number of severe storms.

In this post we will explore the risks that your business might face should extreme weather events become more common in the UK, before discussing how you can manage and mitigate these risks.

Key Risks of Extreme Weather To Businesses

Heatwaves
High temperatures can lead to increased health risks for your staff and your customers.

The risk could be particularly high for anyone who works in a role that demands a lot of physical activity, or in environments where temperatures are already high, such as factories, warehouses, and industrial settings.

Storms
Storms can lead to travel disruption, which could affect your supply chain or your deliveries.

A storm could also lead to property damage, such as from falling trees or branches, and it could even lead to power cuts.

And a power cut could affect your business in a number of ways: You could lose your temperature controlled stock if your fridges or freezers fail, and if your security systems go down you may be more vulnerable to theft or vandalism.

Floods
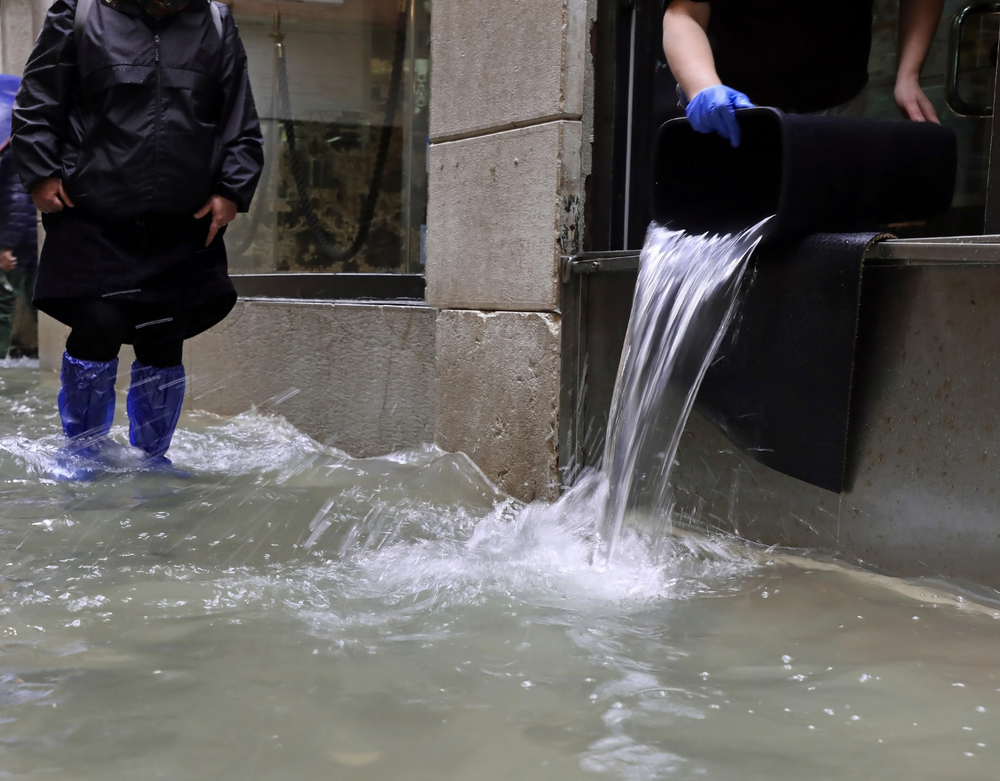
Violent storms can also lead to flash floods, which could cause devastating damages to any kind of business.

And it is not just businesses located on flood plains that need to consider the risk of flood. Heavy rains could overwhelm drainage systems, which could lead to floods in areas that are not usually at risk of flooding.

How To Protect Your Business From Extreme Weather Events

If extreme weather events are becoming more common in the UK, below are some strategies that you could implement to safeguard your business against all kinds of weather-related risks, including:

  • Pay attention to Government warnings and weather alerts
  • Manage extreme temperatures
  • Flood planning and protection
  • Storm planning and protection
  • Insurance cover

We’ll explore each of these in more detail below.

Forecasts and Government Weather Warning Notifications

Pay attention to the weather forecast, and pay particular attention to any Government warnings about extreme weather events, and the possible risks they may bring.

When it comes to floods, take a look at the Flood Hub’s flood risk maps, which provide both a five-day flood risk forecast, along with potential long-term flood risks. You can also sign up for official Government flood warnings, which means you can get a call, text, or email if there are any particular risks in your area.

How to Manage Heatwaves in the Workplace

The Health and Safety Executive (HSE) does not specify a maximum working temperature for any workplace. This is because all workplaces are different, and some employees may routinely experience high temperatures as part of their work, such as those who work in factories, industrial settings, and warehouses.

However, the HSE does provide guidance on “thermal comfort”, outlining how high temperatures could encourage staff to exercise less caution and take more risks. For example, they may struggle to focus or concentrate, they may choose not to wear certain items of PPE, and they may cut certain corners that could put themselves, or others, at risk.

If you are worried about how a heatwave might affect your employees or your business, there are certain policies you could introduce to help your staff keep cool. The British Safety Council has published advice on staying safe at work during heatwaves, which includes:

  • Relaxing dress codes
  • Allowing staff to take more frequent breaks
  • Providing a supply of cold drinks
  • Introducing more flexible working policies

Protecting Your Business From Flooding

Sign up for alerts: Above we mentioned how signing up for flood alerts can give you an advanced warning that could give you time to prepare. However, a severe storm could lead to flash flooding, which could strike your business without warning.

Consider stock and equipment placement: There are some measures you could introduce that could help to limit the damage of any flooding on your premises. This can include storing any high-value stock or equipment on high shelves or upper floors.

Invest in drainage: You could also invest in systems that could help reduce the risks of flash flood affecting your business. For instance, you can install non-return valves on your business’s drains, along with the inlet and outlet water pipes. With these in place, even if the local drainage systems get overwhelmed, it will be less likely that any flood water will enter your premises.

Create a flood response plan: Beyond this, it is worth taking the time to design a flood response plan for your business. This could include steps staff should take to keep themselves safe, along with contingency plans to limit disruption to supply lines, deliveries, and other aspects of your operation.

Read our full guide to preparing your business for a flood. Though this guidance refers specifically to retail businesses, it features tips that could help to keep any business safe.

Protecting Your Business From Storms

Unless high winds cause a tree to fall on your business premises, then it is unlikely that a storm itself will threaten your business. However, long periods of heavy rain could make flash floods more likely, and stormy weather could lead to power cuts and other disruptions.

The best way to protect your business from storms is through assessing all the possible risks that a storm could bring, before designing a risk management plan to help you mitigate these risks:

  • Back-up generators to help you deal with power cuts. You could also ensure that there will always be backup power for your fire and security systems, so that power outages will not put your business at increased risk of fire, theft, or vandalism.
  • Continuity plans for dealing with disruption and business interruption. How would you manage any delayed deliveries or shipments, for example? Who would you notify, and what measures would help you manage operations until you get back on track?
  • Working arrangements: If your staff are temporarily unable to travel due to adverse weather conditions, could you introduce temporary flexible working arrangements that would enable them to work from home?
  • Safety protocols: Would a storm put any of your employees at risk on the job? Your employee safety procedures should specify the conditions in which employees should stop working and instead vacate to a place of safety, particularly if they work in a high-risk environment such as a construction site.

How Insurance can Protect Your Business From Extreme Weather Events

James Hallam is an independent Lloyd’s broker with a team of insurance professionals who are dedicated to protecting your shop from the risks you face from extreme weather.

We can help you understand the specific risks your business faces, and we will ensure that your business insurance will give you the cover you need when you need it most. For example, we can help you access specialist business insurance that will cover you for flood risks, and we will make sure that your business interruption insurance will help cover costs while you get back on track.

Learn more about our tailored insurance solutions for SMEs, and get a free quote today.
 

How to Secure High-Theft Items in Retail

How to Secure High-Theft Items in Retail 1000 572 James Hallam

In 2025 – 2026, police recorded 507,100 shoplifting offences in England and Wales. The annual figures suggest that shoplifting has become increasingly common every year following the 2020 – 2021 lockdowns, and there are significantly more annual recorded incidents now than there were just 10 years ago.

In this post we will outline the sort of products shoplifters are most likely to target, before exploring some strategies to help you protect the high-theft items in your store.

Why Do Thieves Target Some Products More Than Others?

There are a few things that might make a certain item particularly attractive to thieves:

  1. Its value. A lot of the time, shoplifters steal items not because they want or need them, but because they intend to sell them. Some items have a higher demand and thus fetch a higher price on the black market than others.
  2. Its size. The smaller the product, the easier it is for thieves to discreetly lift it from the shelves and hide it.
  3. Its security. Shoplifters may be more likely to attempt a theft is an item is located in a part of the store where they are unlikely to be seen.

What Are The Most Commonly Stolen Items From Shops?

These are some of the most common items shoplifted in the UK:

  1. Baby formula. Unfortunately, this may be the most commonly stolen item in the UK simply because it is essential, it is expensive, and many new parents may be struggling to make ends meet.
  2. Steak, lamb, bacon, and other premium cuts of meat. Some thieves will steal meat for their own personal use. Others will aim to sell it to pubs and other establishments via online marketplaces.
  3. Cosmetics and beauty products. This might include makeup, fragrances, and razor blades. These items are small and lightweight, and thus relatively easy to hide, and they tend to sell for high prices online.
  4. Some thieves may lift bottles of wine or vodka from the shelves for their own use. But others may intentionally target premium spirits, such as whiskey or artisan gin, in order to sell them online.

Of course, even if you do not sell any of these items in your store, you may still sell certain high value items, such as electronics, tobacco, and vaping products, that thieves may target with the intention of selling them online.

How to Secure High-Theft Items in Retail

We recently published a guide to how you can help prevent shoplifting in your store. We also have a guide to dealing with the increased risk of shoplifting at busy times of the year, such as Christmas.

There are some special measures you can introduce to protect the high-theft items in your shop, such as:

  • Rethink your store layout
  • Locked display cabinets
  • CCTV
  • Security Tags
  • Staffing

We’ll explore each of these in more detail to identify exactly how they can help you to reduce and deter theft.

Rethink Your Store Layout

Aim to keep any high value items behind the till, so that customers have to actually request them from staff. Some stores have taken to keeping high-theft items such as baby formula and alcohol behind the till.

When thinking about your store layout, consider lines of sight, and aim to remove any blind spots where thieves could operate unobserved. Also try to make sure there are clear sight lines at your entrance, so that customers would not be able to enter or leave without your staff noticing.

Locked Display Cabinets

If you cannot keep all of your high value items behind the till, then store them in locked display cabinets, so that once again, customers will not be able to access them without asking a member of staff.

Again, consider your store layout. Try to keep these locked display cabinets in a well-lit area as close to the till as possible.

CCTV

You should ensure you have CCTV coverage of your entire shop floor, with a particular emphasis on areas that might be out of sight from the till. You could also position CCTV so that it is always monitoring any locked display cabinets, with signs notifying customers that they are being recorded.

Security Tags

Attach security tags to your high value, high-theft items, which members of staff would have to remove at purchase.

These can act as a strong deterrent, as even if they do not prevent thieves from lifting the products from your shelves, they may not be able to remove the security tags without damaging the product. This would make the product harder for them to sell.

Staffing

Train your staff to understand the common shoplifting techniques, so they know what sort of behaviours to look out for, and what sort of items thieves are most likely to target. Good customer service can also help prevent many thefts. If your staff make a point of greeting every customer as they enter, then any potential thieves will know that their presence has been noted, which may make it harder for them to act.

You should also consider your staffing levels and your staff rotas. If possible, you should aim to limit the times when there is just one single member of staff on the shop floor. This is because shoplifters often work in groups. One person will distract a member of staff while the other attempts to lift a high value item, unobserved.

Get The Right Cover For Your Retail Store

Shoplifting affects retail businesses in a number of ways. Beyond the financial losses, you also have to consider the costs of installing new security systems, the damages to staff morale, and an overall less pleasant retail experience for everyone. If your customers have to contend with security tags, locked cabinets, and extensive CCTV coverage, they may start to feel like you do not trust them.

But no matter how much your security systems cost, they may help you save money in the long-term through reducing your losses due to theft. Plus, if you can evidence your anti-theft measures to your insurers, it may help you to make a saving on the cost of cover.

While insurance cannot itself prevent shoplifting, a specialist retail insurance policy can cover your store for many of the losses you may experience as a result of theft and other incidents.

James Hallam is an independent Lloyd’s broker with a dedicated team of insurance professionals who care about protecting your store.

Find out how we can help your shop today.

Do Shop Owners Need Cyber Cover for POS and Card Payments?

Do Shop Owners Need Cyber Cover for POS and Card Payments? 1000 668 James Hallam

Cyber insurance has become essential for all businesses, and this includes brick and mortar shops. Even if you do not sell any products online, your point of sale (POS) and card payment systems may still leave you vulnerable to attack.

How Can Hackers Target POS and Card Payments?

Cybercriminals know how to target your POS and card payment systems. Some cyberattacks are carried out in person and on your premises. A cybercriminal might use a USB or a similar device to install malware on an unattended terminal, or they may use your guest Wi-Fi to access your POS devices. But cybercriminals can also hack these systems remotely.

What Are The Risks of POS and Card Payment Breaches?

Once cybercriminals gain access to your POS and card payment systems, they can harm your shop and your customers in a number of ways:

  • Cybercriminals might gain access to the data of any cardholder who uses a compromised machine. They could lead to identity theft and other forms of fraud, and it could even result in chargebacks for certain purchases. You may even face some legal action yourself as part of a wider fraud investigation.
  • Cybercriminals may gain remote access to your systems, where they may steal your personal data or your customers’ personal data, or else cause some prolonged system downtime that could seriously compromise your operations.
  • Cybercriminals may install malware that will encrypt your POS systems as part of a ransomware attack. You will not be able to process any payments until you meet their demands. If you fail to meet their demands, they may choose to steal your data outright, or they may simply delete it, which will lead to further downtime. All the while, you will miss out on revenue, and your reputation with your customers and suppliers may suffer.

What Does Cyber Insurance For Shops Cover?

Cyber insurance may not prevent POS and card system cyberattacks from occurring. But if you are the victim of a cyberattack, your cyber insurance policy can provide invaluable cover for your liabilities and recovery:

  • Investigation – You will be covered for the costs of the IT forensics investigation, in which insurers will work to determine the cause of the breach, and identify the scope of the damage.
  • Response – Your policy will cover certain crisis management procedures, such as notifying and supporting any customers who may have been affected by the breach. If necessary, your policy may also cover your PR, which could help you retain your reputation following an attack.
  • Business Interruption – If your POS and card payment systems are compromised or offline, then your revenue will inevitably suffer. Your cyber policy can include business interruption insurance, which can cover any lost revenue while your systems recover.
  • Other expenses – Your cyber insurance policy can cover any other expenses you might encounter during your response and recovery, which might include chargeback and card replacement costs, and the costs of replacing or restoring your terminals and other equipment.
  • Legal Expenses – Finally, your cyber insurance can cover any legal fees that may arise if you are involved in any fraud investigations as a result of the breach.

What is Not Covered By Cyber Insurance For Shops?

While cyber insurance can provide invaluable cover should you find yourself a victim of a cyber attack, there are some circumstances where you might not be covered.

Prior Known Circumstances
You may not be covered from losses arising from problems arising from “prior known circumstances” – for cyber breaches that occurred even though you were aware of a certain vulnerability.

For example, if you notice a customer behaving suspiciously in your store, and you suspect that one of your terminals may have been compromised, then you may not be covered for any subsequent incidents should you fail to act on your suspicions.

Poor Security System Maintenance
Similarly, when you take out your policy, your insurer may ask you to specify any cybersecurity systems and procedures you currently have in place. If you make a claim on your policy, and your insurer finds that you failed to maintain these systems, then they may turn down your claim.

Cover Exclusions
Some cyber insurance policies may list a number of additional exclusions. You may not be covered for incidents arising from “acts of foreign enemies”, for instance, or for data loss that occurs as a result of a wider issue with your provider.

For more information about exclusions to your cyber insurance cover, be sure to read your policy wording.

How To Protect Your Shop From Cyber Attacks

Cybersecurity is a complex issue, and cybercriminals are getting smarter all the time. But here are some essential tips that could help you keep your shop and your customers safe:

  • Updates
    Keep all of your systems updated. Cybercriminals are constantly looking for vulnerabilities to exploit, and security updates are vital for closing these loopholes.
  • Wi-Fi access
    Think twice about offering guest Wi-Fi. Set strong password protection, and never share your login credentials with anyone.
  • Training
    Train your staff to understand the risks of cyberattacks, and the sort of warning signs they should look out for.
  • Physical awareness
    Remember that some retail cyberattacks occur in person. Do not leave any terminals or other devices unattended at any time, as cybercriminals may be able to compromise your systems while your back is turned.

Get Specialist Cyber Insurance For Shops From James Hallam

James Hallam is an independent Lloyd’s broker with a dedicated team of insurance professionals who care about protecting your shop. We can help you access specialist retail insurance for your store, which can include cyber insurance.

Find out how we can help you today.


How Are Extreme European Temperatures and Wildfires Changing Travel Trends?

How Are Extreme European Temperatures and Wildfires Changing Travel Trends? 1000 667 James Hallam

In summer 2026, countries across Europe faced record temperatures along with widespread wildfires. In this post, we will explore how such extreme weather events change travel trends, should they become more common.

Increasing Extreme Summer Temperatures in Europe

The 2026 European wildfires hit some of the most popular travel destinations in France, Spain, Greece, Italy, and Portugal. By early 2026, over 1,000 wildfires had been recorded, affecting over 155,000 hectares of land across the continent.

It may be too early to say how such disasters will affect European tourism in the long-term, but we are already seeing certain trends emerge.

How Wildfires and Heatwaves Are Changing Travel in Europe

Travellers have traditionally booked Mediterranean breaks for late July or August. In the past years, temperatures have soared to the high forties, and travellers already seem to be on the lookout for alternative arrangements:

  • Travelling in spring and autumn, rather than during the high season.
  • Choosing cooler mountain retreats, or locations in northern Europe such as the Baltic Coast and Brittanny.
  • Opting for UK breaks instead of European holidays.

The Rise of Ecotourism

In response to rising temperatures, many travellers are now seeking greener travel arrangements. One recent survey found that “sustainability” is a major priority for the majority of travellers. Another recent report revealed that around 75% of travellers are actively looking for more sustainable travel options.

Growing numbers of hotels and travel operators are rising to meet this demand, through offering greener, and less impactful travel experiences.

Read our full guide to how travel agents can offer more sustainable travel options. We also have a guide to hotel sustainability, which outlines a number of steps hotels can take to attract the next generation of eco-conscious travellers.

How Should Travel Agents and Tour Operators Respond to Heatwaves and Wildfires?

Travel agents and tour operators should look to accommodate changing travel preferences.

  • You might expect an increase in off-season trips, as more people choose to travel in spring or autumn instead of the summer.
  • You could also prioritise destinations with more comfortable temperatures where there is less of a risk of wildfires. This might include UK locations, mountainous regions and coastal areas across Northern Europe
  • You should also aim to offer more sustainable travel options, with a focus on smaller, independent, and boutique accommodation providers.
  • You should be on top of changes and travel guidance. If travellers are concerned about extreme temperatures or wildfires, they may look to their travel agents and tour operators for guidance and reassurance. You should pay attention to international travel advice, and you should know how and when to communicate this advice to your customers. Read our full guide to responding to government travel advice.

Travel Insurance Has Never Been More Important

Extreme temperatures can lead to more than wildfires. Travellers may experience temporary road closures, disrupted connections, closed attractions, and even evacuation orders.

Travellers may ultimately get used to the idea that their trip could be severely curtailed, or even cancelled outright, at a moment’s notice. So, in the coming years, growing numbers of travellers may start to view travel insurance as an absolute necessity, rather than a “nice to have”.

Travel agents and tour operators should also take the time to review their insurance policies to ensure they have all the cover they need for an increasingly uncertain travel industry.

At James Hallam, for over 35 years we have provided dedicated insurance services for travel agents and tour operators. We can help you manage your risks while providing total peace of mind to your customers, and we can also help you access the specialist cover you need at a truly competitive price.

Find out more about our bespoke insurance services for travel agents and tour operators.

Key Risks in Cold Chain Shipping and How to Mitigate Them

Key Risks in Cold Chain Shipping and How to Mitigate Them 1000 667 James Hallam

Cold chain shipping is an integral part of the global shipping industry. In this post, we will outline the key risks in cold chain shipping and how to manage them, so as to guarantee maximum efficiency while maintaining the integrity of your goods.

What is Cold Chain Shipping?

Cold chain shipping is the specialist transport of goods that must be kept at a certain temperature to retain their integrity. This can include food, horticultural products, chemicals, and pharmaceuticals. These goods are stored in a temperature controlled environment, and they are packed in specialist containers that will keep them at the desired temperature during transit, usually with the use of dry ice, gel packs, or liquid nitrogen.

Real time monitoring and specialist handling techniques are required throughout the goods’ journey to their final destination. The goods are stored in cold warehouses at every stop of the journey, and they are transported in temperature controlled vehicles, such as refrigerated trucks.

The specific temperature requirements will depend on the goods being shipped. Some goods will simply require refrigeration at temperatures between 2°C and 8°C. Other goods must remain frozen at temperatures of around -18°C throughout their journey. Some goods require transporting at ultra-low temperatures, around -80°C.

Key Risks of Cold Chain Shipping

Any issues with the cold chain shipping process can result in spoilage, which will invariably lead to significant losses, and damaged customer trust. But in cold chain shipping processes involving chemicals and pharmaceuticals, any issues could lead to additional health risks, and even death.

Below we will outline some of the key risks of cold chain shipping, before exploring how you might address these risks, including:

  • Poor temperature management
  • Inadequate packaging
  • Poor training
  • Lack of contingency planning

Poor Temperature Management

Unless you act to ensure that all goods are kept at the required temperature throughout the entire shipping process, there will be a strong risk of spoilage, deterioration, and even the potential for pathogen growth.

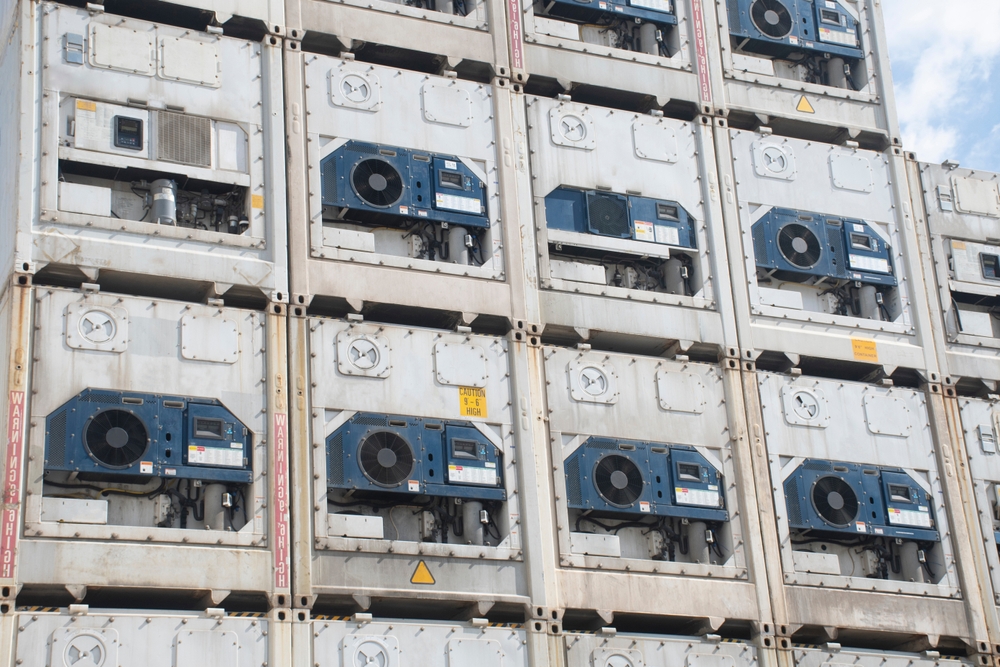
This is a particular issue when goods are shipped overseas in refrigerated containers (reefers). If reefers lose power during a voyage, either as a result of mechanical breakdown or human error, then the temperature control can fail, which could cause entire shipments to be lost.

Issues with reefers during overseas cold chain shipping processes can lead to additional issues, as it is often difficult to determine just who is liable for the container losing power. This can lead to costly disputes between shippers and carriers.

Inadequate Packaging

The packaging used in a cold chain shipping process should do more than keep the goods cool. It should also protect them from humidity, light, and impact.

Poor Training

Employees may assume that all products involved in a cold shipping process have the same temperature storage requirements, which may not necessarily be the case. Some products may carry additional storage or handling requirements beyond the temperature requirements. If your employees are not familiar with these procedures, it could lead to losses, and even certain health risks.

Poor training could also lead to inconsistent labelling and recording, which could lead to compliance issues, along with considerable delays to the end-to-end shipping process.

Lack of Contingency Planning

Many things could go wrong during the cold shipping process. Power outages, equipment failures, traffic delays, and other factors could compromise the integrity of your goods. If you are not prepared for such unforeseen circumstances, then the slightest setback could lead to severe problems down the line.

How To Mitigate the Risks of Cold Chain Shipping

There are a number of ways you can start mitigating the risks of cold chain shipping to reduce spoilage and potential risks, including:

  • Risk assessments and contingency planning
  • Staff training
  • Packaging
  • Technology

We’ll address each of these in more detail below, covering how you can follow these processes and reduce risk.

Risk Assessments and Contingency Planning For Cold Shipping Issues
Take the time to consider anything that could go wrong at every stage of the cold shipping process, and outline how you would address each issue. Create a document that describes the actions that should be taken in the event of each specific setback, along with who is responsible for taking these actions.

Staff Training for Monitoring and Handling Shipments
Any employee involved in a cold chain shipping process should be trained to treat each specific shipment as its own unique case, with specific temperature, storage, and handling requirements. To ensure compliance and operational efficiency, employees should also be trained in the correct labelling and documentation procedures.

Packaging Best Practice
Never cut corners when it comes to your packaging solutions. Always choose the most durable solutions that are validated for the specific temperature ranges required for the process.

Invest in Tech for Real-Time Temperature Monitoring
Do not rely on outdated tools to monitor your temperatures and record your shipments. Instead, invest in advanced tools to allow for continuous real-time temperature monitoring, so that you can respond to any issues as soon as they become apparent.

Get Specialist Marine Insurance for Cold Chain Shipping

Everard Insurance Brokers provides specialist cargo insurance solutions, which can include dedicated cover for cold chain shipping operations. We can help ensure your cargo is properly protected from origin to destination.

Your specialist marine insurance could include parametric cargo insurance cover. If a temperature fluctuation takes place during the shipping process, GPS sensors in the container can automatically notify your insurer. As well as helping to avoid liability disputes between the shipper and the carrier, you may also be able to get a settlement even before the container is opened and the damage is discovered.

Find out more about our specialist marine insurance services.


Right of Light Insurance Explained for Property Developers

Right of Light Insurance Explained for Property Developers 1000 667 James Hallam

A right to light claim can delay or derail any development project, and it could result in significant financial losses. This is why it is important that everyone involved in any property development project takes the time to understand what right to light is, along with the possible implications of a claim.

What is Right to Light?

Right to light is a legal easement that gives landowners a right to receive light through any defined aperture, such as a window or a skylight, on any building on their land.

This is an extremely old law, based on measures first outlined in the Ancient Lights Law of 1663, and further developed in the Prescription Act 1832. The Prescription Act 1832 stipulates that a property owner obtains an absolute and indefeasible right to light after 20 years of uninterrupted access through a buildings window or opening.

What are the Purpose of Right to Light Laws?

These laws are put in place to prevent developers from building extensions or structures that block or reduce natural light below acceptable levels.

If a landowner has been receiving natural daylight through windows or other apertures for 20 years or more, then they can prohibit any development that would deprive them of this light

In practice, this means that neighbouring properties cannot build anything that would obstruct this light.

What is a Light Obstruction Notice (LON)?

Often a Light Obstruction Notice (LON) is issued by the developer to the neighbouring properties. A LON is a legal tool used in England and Wales to stop a neighbour from gaining a legal right to light. It acts as a virtual barrier which pauses the 20-year time limit to claim that light and lasts for 12 months if registered correctly.

How Does the Right to Light 20 Year Rule Work?

Imagine a landowner who has been living in their property for 20 years or more and they have always received light through the large windows in their living room. However, one of their neighbours builds an extension which blocks a lot of this light. As a result, their living room is not as bright as it used to be.

In this instance, the claimant could make a right to light claim by verifying their entitlement by hiring a specialist surveyor / solicitor to investigate. Most disputes end in financial compensation or adjusted building plans, but it could also end up with a court-ordered cut back, demolition or an injunction stopping the development altogether.

This is why it is crucial for property developers to have a financial contingency plan.

The Role of Insurance in Right to Light Claims

An insurance policy can provide you with the necessary financial contingency plan. Whilst it doesn’t remove the issue, it provides peace of mind that if a claim occurs then the insurance policy will indemnify the insured for financial losses covered in the policy.

What does a Right to Light Insurance policy cover?

  • Court costs and out of court settlements
  • Loss in market value of the property
  • Abortive costs of works and alteration, demolition and reinstatement of a property
  • Professional fees associated with the above
  • Defence costs, legal fees and other expenses

Additionally, you can add the following to the insurance policy if required:

  • Delay costs: The costs associated with the suspension of works pending a court order or resolution of a claim
  • Business interruption: Loss of rental income and service charges in the event of an injunction
  • Re-location costs: costs of relocating tenants in the event of an injunction or court order pending resolution
  • Service provider costs: utilities and other services can be covered by the insurer if there is a delay in a development due to the defect. Some insurers provide delay costs as standard in their policies.

When to Arrange Right to Light Insurance

If you are developing and think that you could be infringing onto the neighbouring properties right of light, then it would be best to first speak with a right of light surveyor and an insurance broker. The earlier you seek insurance the easier it is to obtain a policy which fully protects the developer.

Get in Touch for Insurance Advice

At James Hallam we work with your surveyor to ensure you have a strategy that suits your needs as a developer and make sure that insurers structure this into the policy wording.

If you would like us to obtain a Right of Light quotation for you, we would need the following information:

  • The Rights of Light Report (with Equivalent First Zone Figures EFZ)
  • Gross Development Value
  • Details of neighbourly matters e.g party wall / crane oversail
  • Details of whether any light obstruction notices have been served
  • Planning officers report if cover is required post planning

get in touch for a free quote today.

What Home Insurance Do I Need For an Airbnb?

What Home Insurance Do I Need For an Airbnb? 1000 667 James Hallam

If you want to let your property on Airbnb, then your standard home insurance policy will not give you the cover you need. Instead, you will need some specialist home insurance for your Airbnb.

Why Won’t Home Insurance Cover an Airbnb?

If you let your home to paying guests, then you will expose yourself and your property to many risks that will not be covered by a standard home insurance policy.

These include:

  • Accidental or intentional damage to your property, or to neighbouring properties and common areas.
  • Loss or damage of guests’ property.
  • Accidents or injuries sustained by guests on your property.

As the property owner, you could be held personally liable in any of these situations, and your standard home insurance policy simply would not give you the cover you need. But a dedicated home insurance policy for an Airbnb would cover any legal fees and compensation payments that may arise in the event of a claim.

Other Common Exclusions in Home Insurance Policies

Most home insurance policies will not cover you for accidental damage or wear and tear. But there are certain other common exclusions that would make a standard home insurance policy unsuitable for an Airbnb property.

For example, most home insurance policies will not cover you if your home is left unoccupied for an extended period, which is usually between 30 and 60 days. The cover will not apply if your home is unoccupied for longer than this.

There are many different ways to use a property as an Airbnb.

If you are letting a separate room or building on your property, such as a shepherds hut, or annex in your house, then it is unlikely that your property will be unoccupied for too long. Though it’s important to note that regular checks doesn’t always qualify as ‘occupation’.

However, if you want to list an entire property on Airbnb, then the property may be unoccupied for long periods throughout the year. Some parts of the world will only attract visitors during certain times. And there may be long periods where, for one reason or another, you simply struggle to attract any guests.

In any case, if your property is unoccupied for these extended periods, then your standard home insurance policy would not give you the cover you need.

What Home Insurance Do I Need For an Airbnb?

Specialist home insurance for your Airbnb should include the following core areas of cover:

  • Host liability Liability – Cover for any accidents or injuries your guests may experience while staying on your property. This can also include cover for losses arising from your guests’ actions. For example, a guest might accidentally leave a door unlocked before they vacate your premises, which could put you at greater risk of theft or vandalism.
  • Unoccupied property insurance – A dedicated Airbnb policy could cover your property for any periods where it might be unoccupied, even if you need to shut down your property completely at the end of the holiday season.
  • Buildings Insurance – Cover for your property, along with any neighbouring properties and common areas, for any accidental or intentional damage from guests.
  • Contents Cover – As well as covering your property’s fittings, furniture, and fixtures, your insurance can cover any items you purchase specifically for your guests to use, including bedding, cutlery, games etc.

How Much is Home Insurance For an Airbnb?

The amount you pay for your Airbnb insurance will depend on a number of factors:

  1. The type of letting – Are you letting a single room, or annex, of your house? Or is it a separate building on your property? Or are you letting your entire property? Each arrangement will bring different risks and considerations, all of which will affect the cost of your cover.
  2. The size of your property – The more people who will be using your property at any one time, the greater the chances are that something might go wrong. It will cost more to insure an entire property for six guests than it would, for example, a single shepherd’s hut for two guests.
  3. Your location – You may have to pay more for cover if you are based in an area with relatively high crime rates, for instance. Yet in this case, you may be able to make savings on your cover if you invest in extra security systems.

We Can Help You Get The Insurance You Need For Your Airbnb

If you are looking for home insurance for an Airbnb, we are here to help.

We can help you access the specialist insurance you need to cover your property on Airbnb, including host liability insurance, host damage protection, and comprehensive second home or holiday home insurance.

Find out how we can help you with Airbnb insurance today.

How to Calculate Business Interruption Cover

How to Calculate Business Interruption Cover 1000 660 James Hallam

Business interruption cover can help your business recover from an incident such as a fire, a flood, or a break-in.

Yet it is one thing to have a business interruption policy in place. It is just as important to ensure that your business interruption insurance will give you the cover you need should you ever make a claim on your policy.

According to one report by the Chartered Institute of Loss Adjusters, around 40% of businesses with business interruption policies are underinsured. This means that their policy would not stretch to cover all their expenses if they ever needed to make a claim.

In this post we will explore how you can calculate your business interruption cover to ensure you will have the cover you need when you need it most.

What is Business Interruption Insurance?

Following an unexpected event, such as fire, flood, or theft, you may be forced to temporarily halt or modify your business operations. In this case, business interruption insurance can cover your overheads for as long as it takes for your business to recover.

A good business interruption insurance policy should give you enough cover to restore your business to the exact position it was in before the incident took place. Plus, the policy should provide enough to cover your business throughout the entire recovery period, even if it takes years.

What Does Business Interruption Insurance Cover?

  • Loss of Gross Profits – Business interruption insurance may cover for loss of gross profit, which will cover your business’s net profit loss following an insured event. This type of cover is most suitable for businesses with multiple variable costs.
  • Loss of Revenue – Alternatively, a business interruption insurance policy may cover for loss of revenue, meaning it will cover your loss of turnover or income following an event. This form of cover is more suitable for businesses with more fixed costs, which must be paid regardless of whether the business is operational.
  • Increased Cost of Working (ICOW) – This is cover for any extra investments you may need to make in order to continue operating as normal following an unexpected event. This might include cover for renting alternative working spaces, for hiring temporary staff, and for acquiring new stock or equipment.

How to Calculate Business Interruption Cover

There are two key things to consider when calculating your business interruption cover:

  • Sum Insured – This is essentially the settlement you would get if you made a claim on your policy. As we outlined above, your sum insured may be based on your loss of profits, your loss of revenue, or your increased cost of working.
  • Maximum Indemnity Period – This is the maximum period for which your business interruption insurance policy will cover you. Think of it as an estimate of the time it would take your business to fully recover from the unplanned event.

How to Calculate Your Sum Insured

Depending on the nature of your business, your sum insured may be based on:

  1. Your loss of gross profits or your loss of revenue
  2. Your increased cost of working

When it comes to calculating your gross profit or your annual turnover, it is not enough to simply look at figures from previous years. You should also consider possible future trends, along with the potential impact of inflation.

Whether you are calculating your gross profit or your gross revenue, you should always factor in ongoing expenses such as:

  • Purchases
  • Utility costs
  • Staff wages

While accountants may deduct these expenses when calculating gross profit, your business interruption insurance will need to cover you for these expenses, and more.

When calculating your increased cost of working, as well as calculating any additional costs your business may incur, such as through renting alternative premises or hiring temporary staff, you might also consider how you might save on certain expenses throughout your recovery. For instance, if your employees are able to temporarily work from home, you could make savings on ongoing operational costs such as utilities.

How to Calculate Your Maximum Indemnity Period

One of the most common mistakes businesses make when calculating their business interruption cover is in underestimating just how long it would take their business to recover from an unplanned event such as a fire or a flood.

In a business interruption insurance policy, the maximum indemnity period is a hard line: Once you reach your policy’s maximum indemnity period limit, you will cease to receive any further claim payments, even if you have not yet received the maximum amount of your sum insured.

It will likely take you much longer than you think to recover from an event, and you will need your business interruption insurance to cover you for the entirety of your recovery period. So, you should aim to make the maximum indemnity period as long as possible.

Some insurers offer a 12 month indemnity period as standard. But others have started to offer a 24 month indemnity period as standard, so as to help businesses avoid a common underinsurance trap.

We Can Help You Calculate Your Business Interruption Cover

An insurance broker can help you determine what kind of business interruption policy is right for you, based on how your business operates, whether this is a loss of gross profit policy, a loss of revenue policy, or a dedicated ICOW policy. They can then help you calculate your sum insured, based on your past and projected profits and revenue, along with any extra costs or contingencies you may need to consider.

James Hallam is an independent Lloyd’s broker with a dedicated team of experienced insurance professionals who are committed to getting you the cover you need at a price you can afford. We can help you get tailored business interruption insurance while avoiding some common underinsurance pitfalls, so that you will have all the cover you need when you need it most.

Get in touch for a free quote today.

Welcome to James Hallam: Supporting Anthony Jones Business and Personal Insurance Customers

Welcome to James Hallam: Supporting Anthony Jones Business and Personal Insurance Customers 500 334 James Hallam

When your insurance arrangements move to a new broker, it’s understandable to have questions. Will your service change? Who do you contact? Will you still receive the same expert advice?

If you’re an Anthony Jones business or personal insurance customer, you can be reassured that you’re moving to a broker with a long-standing reputation for delivering specialist insurance advice and outstanding customer service.

James Hallam is proud to be the official nominated insurance broker for Anthony Jones customers, providing continuity, expertise and access to an even broader range of insurance solutions.

A broker you can trust

Insurance isn’t just about policies. It’s about having experienced people who understand your circumstances and are there to help when you need them most.

As one of the UK’s leading independent insurance brokers, James Hallam has been arranging insurance for businesses and private clients for more than four decades. We work with a wide panel of leading insurers, enabling us to recommend cover that’s tailored to each client’s individual needs rather than a standard, one-size-fits-all solution.

Whether you’re protecting your family home, your car, your business premises or your professional liabilities, our advisers take the time to understand what’s important to you.

Looking after both personal and business insurance

One of the advantages of working with James Hallam is the breadth of expertise available under one roof.

For personal customers, we can arrange insurance for homes, vehicles, travel, valuable possessions and many other everyday risks.

For business owners, we support organisations across a wide variety of industries, arranging cover for property, liability, professional risks, cyber threats, fleets and much more.

Many of our clients appreciate having a single trusted broker who can look after both their business and personal insurance requirements, making it easier to review cover, identify potential gaps and ensure their insurance evolves alongside changing circumstances.

Making the transition straightforward

We understand that changing brokers can seem daunting, but our priority is making the process as seamless as possible.

Our experienced advisers are available to answer questions, explain your options and support you throughout your renewal and beyond.

You’ll continue to receive personal service from knowledgeable insurance professionals who are committed to helping you make informed decisions about your insurance.

Insurance advice that grows with you

Insurance requirements rarely stay the same for long.

Businesses expand, employ more people, purchase new equipment or enter new markets. Families move home, buy new vehicles or acquire valuable possessions.

Regular reviews help ensure your insurance continues to reflect your current circumstances, providing appropriate protection without unnecessary complexity.

As an independent broker, James Hallam can work with you over the long term, adapting your insurance programme as your needs change.

Welcome to James Hallam

We’re delighted to welcome Anthony Jones customers to James Hallam.

Our focus is simple: providing expert advice, excellent service and tailored insurance solutions that give you confidence in the protection you have in place.

Whether you’re renewing an existing policy, reviewing your insurance portfolio or looking for advice on future cover, our team is here to help.

We look forward to building a long-term relationship and helping you protect what matters most, both in business and in your personal life.

If you have any questions or would like to speak to a member of the dedicated Anthony Jones team, please don’t hesitate to get in touch.

What is Contractors’ All Risk Insurance and Who Needs It?

What is Contractors’ All Risk Insurance and Who Needs It? 1000 666 James Hallam

If you are a building contractor, contractors’ all risk insurance can cover almost every aspect of an ongoing construction or development project, including the equipment and materials you are using, and any people involved in the project.

What is Contractors’ All Risk Insurance?

Contractors’ all risk insurance is specialist insurance cover for building contractors. As the name suggests, it is designed to cover all of the risks you might face throughout a building and development project.

Core areas of cover include:

  • Insurance for contract works on construction sites, including cover for demolition and excavation projects.
  • Plant and equipment insurance.
  • Business interruption insurance, to cover project overheads in the event of delays.
  • Insurance for any temporary buildings you use throughout the project.
  • Liability and personal injury insurance for any individuals involved in the project, including workers and other members of the public who might spend time on or near the construction site.

Once the project is complete, contractors’ all risk insurance can also provide some cover for your completed buildings while they are unoccupied and awaiting tenants.

Contractors’ all risk insurance should not be confused with contract works insurance. For more information, read our guide to the difference between contractors’ all risk insurance and contract works insurance.

Who Needs Contractors’ All Risk Insurance?

Contractors’ all risk insurance can provide essential comprehensive cover for many parties concerned with construction projects, including:

  • Building contractors and construction firms.
  • Subcontractors, such as those who provide specialist services during a building project, including electricians, plumbers, and roofers.
  • Property developers, should a renovation require extensive construction work.
  • Property owners arranging for construction of renovation work.
  • Civil engineering contractors.

In most cases, the main building contractor will take out a contractors’ all risk insurance policy to cover the project, and they may take out a joint policy with a second party, such as a property owner.

Each of the parties we have listed above should ensure they are covered by the main contractor’s all risk insurance policy. If not, then they may have to get a policy of their own to cover their own materials, equipment, employees, and liabilities.

Is Contractors’ All Risk Insurance a Legal Requirement

Though contractors’ all risk insurance is not always a legal requirement in the UK, many large scale construction or renovation projects will require such cover to be in place. The contract may also specify who is required to arrange for the cover, whether this is the main contractor, or the employer.

Why You Need Contractors’ All Risk Insurance

Yet even without a legal obligation, and even if there are no contractual obligations, you should still view contractors’ all risk insurance as an absolute necessity, particularly when it comes to certain kinds of construction or renovation projects:

  • Large projects involving extensive complex works, in which the costs of any potential damage or delays would be significant.
  • Development projects organised by the property owner, for which they would be liable for all financial risks.
  • Joint projects involving numerous contractors, subcontractors, and other parties.

In any of these situations, a single incident could lead to significant costs which could jeopardise not just the project, but also your business. Contractors’ all risk insurance would cover these costs, providing essential protection for the project itself, and for all parties involved.

Get The Specialist Construction Insurance You Need With James Hallam

James Hallam is an independent Lloyd’s broker with a specialist team of experienced insurance professionals who are committed to protecting construction business.

We will take the time to understand your construction project so that we can advise on the specific risks you are facing. We can then help you access a specialist contractors’ all risk insurance package that meets all of your needs at a competitive price.

Find out how we can help you today.